

Entergy Paid for Its $67bn Build With Shares and Its Earnings Per Share Fell to $1.03
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two regulated utilities fell together in September on the same rate shock, and their June quarters have almost nothing in common. Entergy grew revenue 5.9% and sold more power to industrial customers, yet its diluted share count rose 4.6% and per-share earnings went backwards: the equity funding a $67bn build is now showing up in the printed number.
ONE Gas did the reverse — revenue fell while net income rose 46%, because riders and weather normalization sever its earnings from volumes, and it raised full-year guidance in August. Entergy's multiple has come down since May, a de-rating its own arithmetic explains. ONE Gas's contraction, to 16.1x trailing earnings from 20.2x, has nothing in its numbers behind it.
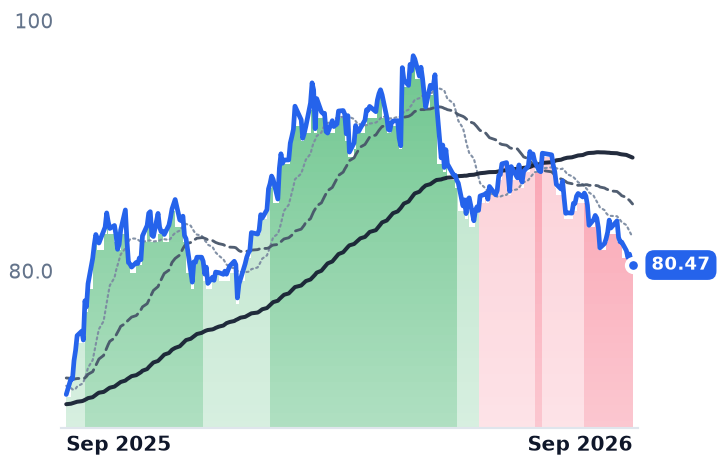
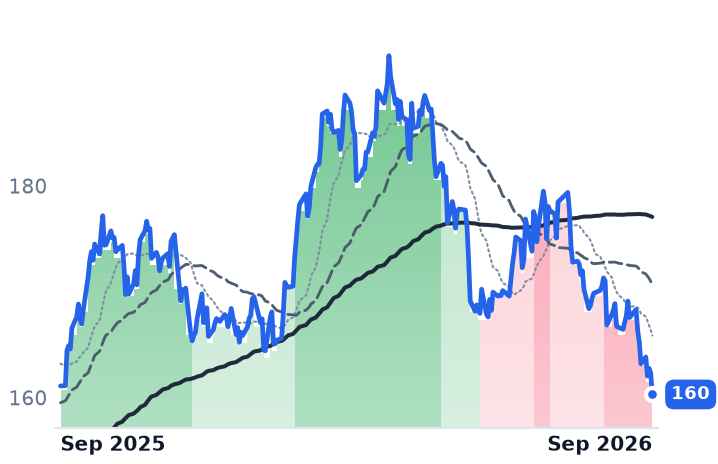
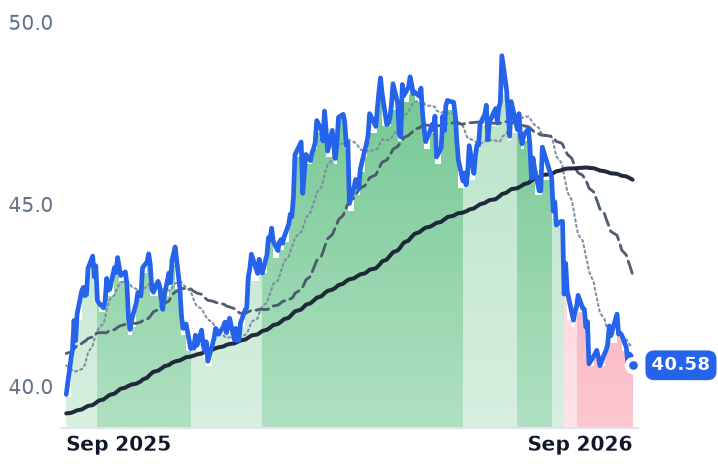
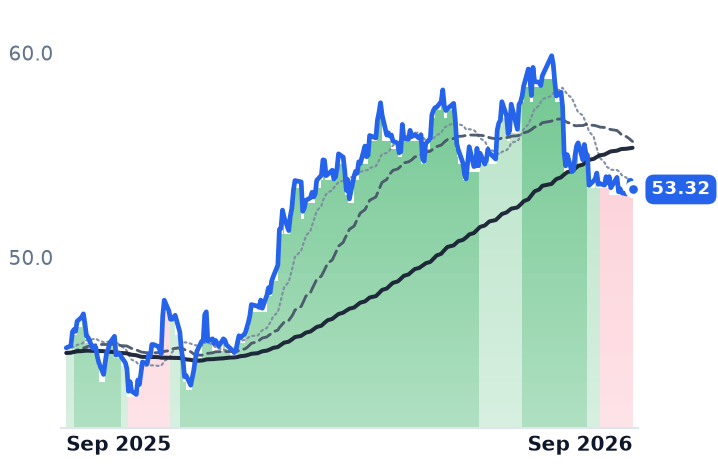
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
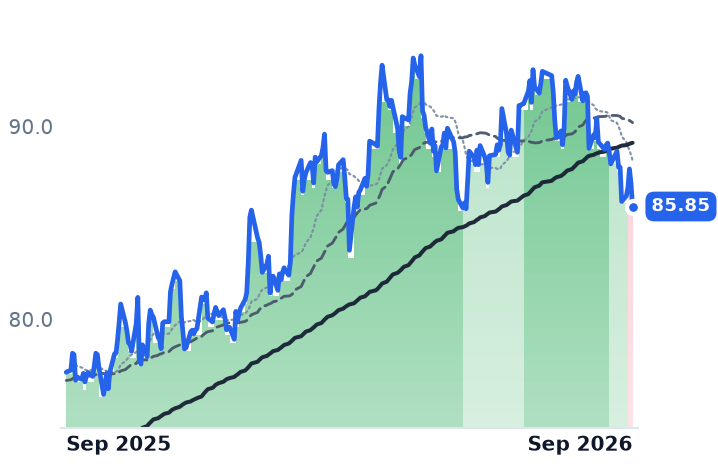
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.2% | +16.6% |
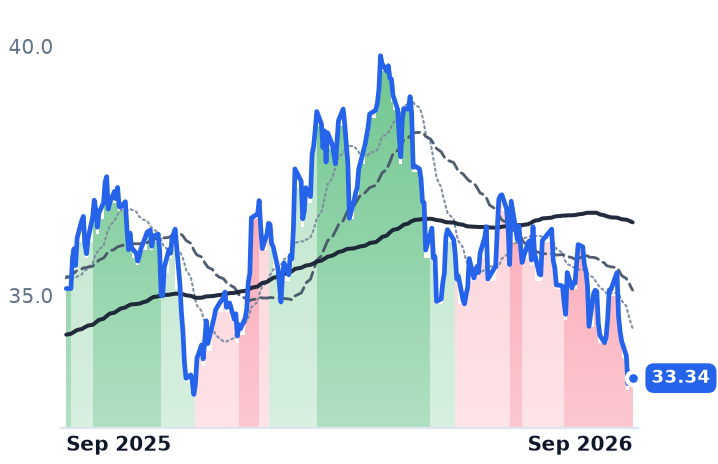
OGS | ONE Gas | Natural Gas Distribution | ⚠️ Emerging Bear | −8.0% | +0.9% |
| Compared against · context, not the story | |||||
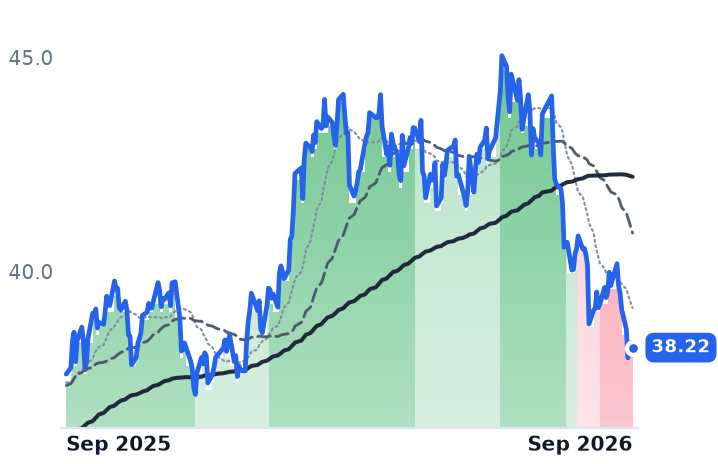
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.8% | +13.9% |
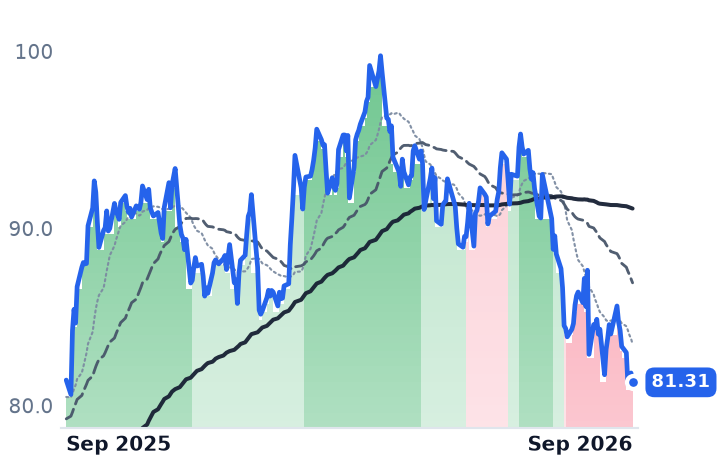
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −6.5% | +8.6% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.6% | +14.8% |
ATO | Atmos Energy | Natural Gas Distribution | ⚠️ Emerging Bear | −6.3% | −0.5% |
NI | NiSource | Natural Gas Distribution | ⚠️ Emerging Bear | −2.9% | +2.0% |
NJR | New Jersey Resources | Natural Gas Distribution | 🟢 Cont. Bull | −3.0% | +17.0% |
SWX | Southwest Gas | Natural Gas Distribution | 🟢 Cont. Bull | −6.2% | +11.1% |
PPL | PPL | Transmission & Distribution Only | ⚠️ Emerging Bear | −5.3% | −5.1% |
CNP | CenterPoint Energy | US Electric & Gas Utilities | ⚠️ Emerging Bear | −4.8% | +1.6% |
SRE | Sempra | US Electric & Gas Utilities | ⚠️ Emerging Bear | −7.2% | −0.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +15.4% |
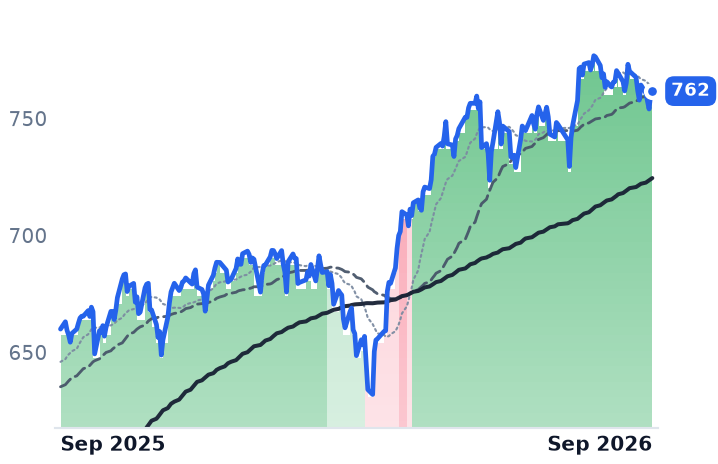
12-month price & trend
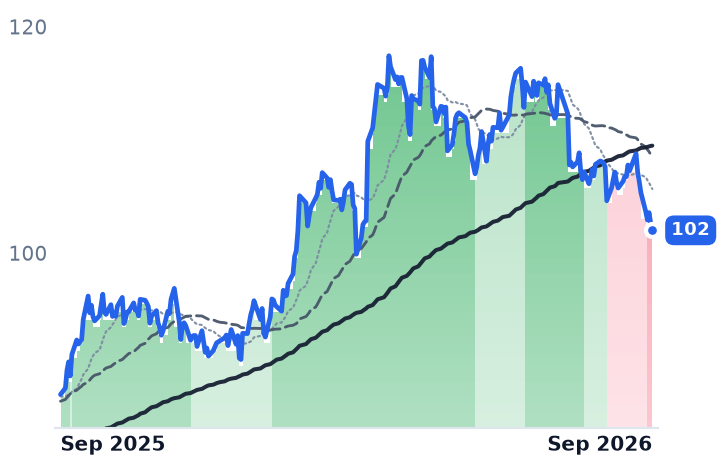
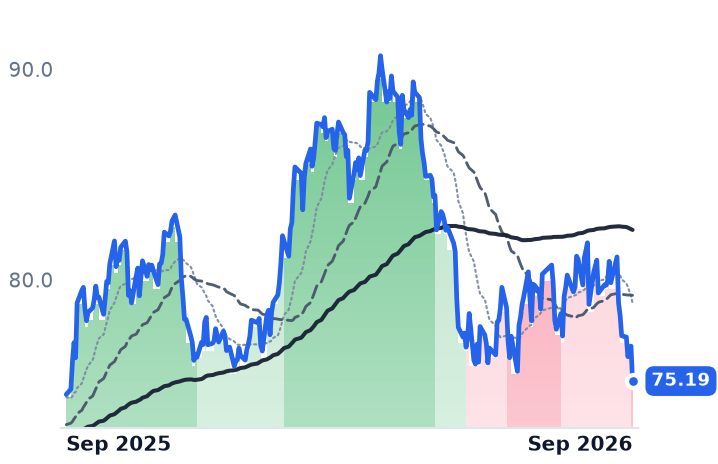
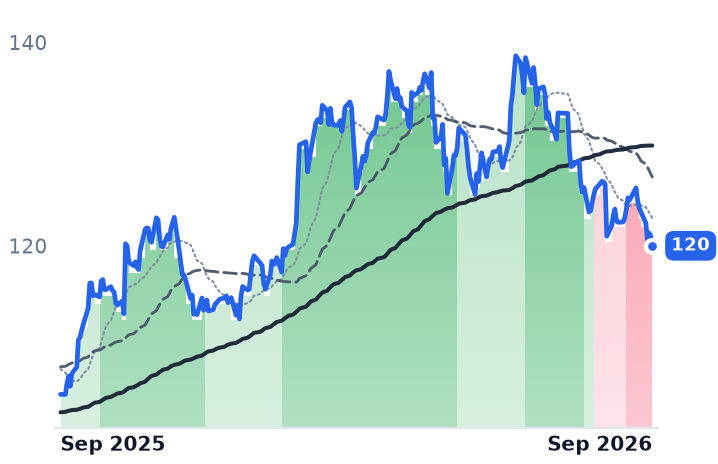
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETR | $47.6B | 25.8x | 23.2x | 3.5x | 3.4x | 9.1x | 8.8x | 14.0x | -6.6% |
OGS | $4.7B | 16.1x | 15.4x | 2.0x | 1.9x | 2.7x | 2.6x | 10.4x | -3.7% |
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
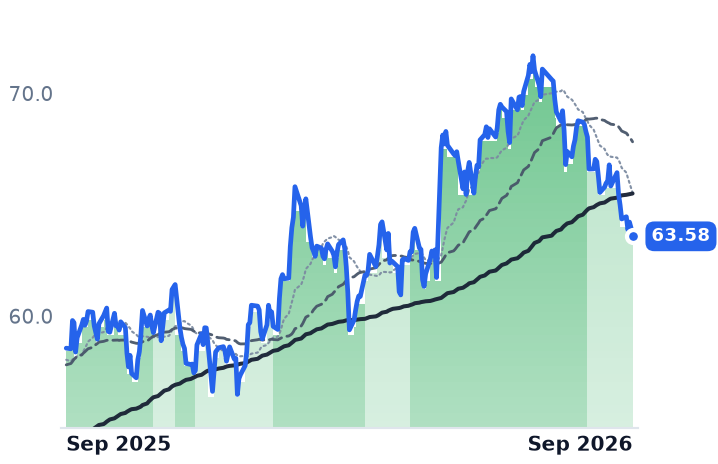
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
D | $57.4B | 22.6x | 18.2x | 3.1x | 3.1x | 6.4x | 6.4x | 15.0x | -11.9% |
NEE | $172.8B | 18.5x | 20.6x | 6.0x | 5.6x | 8.3x | 7.8x | 15.8x | -5.9% |
ATO | $28.0B | 19.8x | 19.8x | 5.7x | 5.4x | 9.3x | 8.9x | 14.1x | -7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NI | $19.7B | 21.7x | 20.0x | 2.9x | 2.8x | 5.6x | 5.5x | 11.6x | -5.5% |
NJR | $5.4B | 14.7x | 14.9x | 2.4x | 2.4x | 8.5x | 8.6x | 11.7x | 1.4% |
SWX | $6.4B | 12.3x | 20.7x | 3.7x | 3.3x | 6.5x | 5.8x | 11.0x | -13.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PPL | $25.6B | 27.1x | 17.5x | 3.6x | 2.6x | 10.5x | 7.6x | 13.7x | 1.0% |
CNP | $25.5B | 22.8x | 20.3x | 2.7x | 2.6x | 4.9x | 4.8x | 12.6x | -10.6% |
SRE | $55.1B | 24.3x | 16.5x | 4.0x | 4.0x | 9.7x | 9.7x | 14.1x | -10.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ETR | Revenue | +8.5% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.5% | |
OGS | Revenue | −3.2% | +3.5% | +2.9% |
| EPS | +11.8% | +3.3% | +8.4% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
D | Revenue | +13.7% | +6.5% | +5.8% |
| EPS | +5.0% | +6.3% | +7.0% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% | |
ATO | Revenue | +6.8% | +7.7% | +8.7% |
| EPS | +14.2% | +6.8% | +8.4% | |
NI | Revenue | +15.3% | +5.6% | +6.3% |
| EPS | +9.0% | +9.7% | +10.2% | |
NJR | Revenue | +12.2% | −2.8% | +4.5% |
| EPS | +10.1% | −5.1% | +8.2% | |
SWX | Revenue | −46.4% | +5.8% | +6.2% |
| EPS | −22.1% | +15.6% | +19.4% | |
PPL | Revenue | +10.9% | +5.8% | +5.4% |
| EPS | +7.7% | +8.7% | +8.5% | |
CNP | Revenue | +9.0% | +3.9% | +5.0% |
| EPS | +8.5% | +9.1% | +9.2% | |
SRE | Revenue | −3.7% | −1.8% | +1.7% |
| EPS | +11.6% | +8.0% | +8.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Entergy sold 9.9% more power to industrial customers in the June quarter, on a weather-adjusted basis, and still reported lower earnings per share than a year earlier. Revenue at the New Orleans-based utility, which serves about 3 million electric customers across Arkansas, Louisiana, Mississippi and Texas, grew 5.9% to $3.52bn. Diluted earnings came in at $1.03, against $1.05.
The gap between those two facts is the whole business. A regulated utility is not paid for demand; it earns an allowed return on equity applied to a rate base of poles, wires and generation that state commissions approve years after the concrete is poured. Building that rate base faster means funding it, and Entergy's five-year capital plan now runs to $67bn, raised from $57bn earlier this year, peaking near $16.8bn of spending in 2027. Its trailing free cash flow yield is minus 6.6%: operations do not cover the build. The company's second-quarter filing puts the equity requirement at roughly $7bn through 2030, with about $4.1bn already settled or under forward sale agreements as of 30 June. Share count rose 4.6% year on year to 466m. Net income grew 3.4%. Dilution took all of it.
The market priced that on the day: the shares fell 4.0% on 29 July, when adjusted earnings of $1.03 missed a consensus near $1.13 and the company blamed milder weather, higher operating expense and the settlement of equity forwards, while affirming full-year guidance of $4.25–$4.45.
What the load is worth, and when
"We continue to have seven to 12 gigawatts of hyperscale data center potential in our pipeline, as well as three to five gigawatts of interest from traditional industrial segments," chief executive Drew Marsh told analysts on the 29 July call, adding that the figure is already probability-weighted and that many of those opportunities remain indications of interest rather than signed proposals. What is signed comes with terms: Entergy's "Fair Share Plus" framework requires prepayment, multi-year contracts, credit and collateral, and early-termination penalties, with data centers paying the full cost of connecting. And a contract only becomes earning assets when a commission says so — the Louisiana Public Service Commission approved the investments tied to Meta's Richland Parish campus.
The lag between spending and recovery is measurable. In Arkansas, Entergy's February rate application covers a rate base of $11.7bn and asks for a 9.85% return against an 8.43% earned return for calendar 2025, with a decision targeted for December and new rates in January. Asking is getting harder everywhere: US utilities requested $18.6bn of rate increases in the first half of 2026 alone, against $29bn for all of 2025, which Fitch reads as rising political risk to cost recovery.
The other way to earn the same dollar
ONE Gas, a pure-play distributor operating as Oklahoma Natural Gas, Kansas Gas Service and Texas Gas Service, ran the arithmetic backwards in the same quarter. Revenue fell 2.9% to $411.6m; net income rose 46.1% to $46.8m and operating margin widened 3.1 points. Weather normalization and decoupling detach earnings from therms sold — first-half adjusted earnings rose 16% with weather 25% warmer than normal. "This performance gives us the confidence to raise our adjusted earnings expectations for the full year," chief executive Robert McAnnally said on 5 August, lifting guidance to $4.89–$4.95. Its growth comes from replacing pipe, recovered through riders rather than rate cases: a $36.9m Texas infrastructure increase approved in July, $28.7m in Oklahoma, a $14.3m Kansas surcharge due in October, with no full case planned before 2027. A Texas law allowing deferral of depreciation and carrying costs between in-service date and rate inclusion is worth about $0.42 of this year's earnings — a legislated cure for exactly the lag Entergy is living with. Its equity need for the year: forward sales of $41.5m, roughly half of it.
What the month hid
Every regulated name in the sector fell 3.7% to 7.3% over the past thirty days against a 0.75% decline in the S&P 500, with ONE Gas (-7.2%) falling harder than Entergy (-5.6%) — a common shock, dated to the Federal Reserve's quarter-point hike to 3.75%–4.00% on 16 September and a 10-year Treasury above 5%, the same move this paper has described all week. Nothing separates the two meters inside it. The year does: Entergy is up 16.1% over twelve months, ONE Gas down 0.5%, and over six months the gas distributors de-rated hard while Entergy barely moved.
So the September selling is duration, and the de-ratings underneath it are not one thing. Entergy at 25.8x trailing and 23.2x forward earnings, down from 29.9x in May, is being marked for something real: the plan is funded with stock, the printed per-share number went down while the business went up, and the Arkansas gap says the return arrives late. ONE Gas at 16.1x trailing and 15.4x forward, against 20.2x in May and 1.3x book, raised guidance into its own contraction. Nothing in its numbers went the way of its multiple.
On the August call, ONE Gas management declined interest-rate hedging structures, citing complexity and an expectation that the Fed would be cutting in 2027 through 2029. Six weeks later the Fed raised rates for the first time since 2023.