

Nucor Guided Third-Quarter Profit Below Consensus With Its Metal Spread Still Widening
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A steelmaker whose earnings more than doubled in a year was priced more cheaply at the end of it than at the start — and then one guidance release erased a month of gains in a session.
Nucor told investors third-quarter earnings would come in at $5.55 to $5.65 a share against a consensus near $6.17, and the shares fell 7.1% the next day. The business underneath did not crack: the electric-arc mills sold outside steel at $1,145 a net ton in the June quarter while melted scrap cost the equivalent of about $377, shipments hit a record 7.1m tons and utilisation reached 91%.
The two halves of the steel heading are paid by opposite machines. Nucor's 85% year was bought with earnings — trailing profit per share rose 126% while its price-to-earnings ratio fell to 19.8x. ArcelorMittal's 109% year was bought with expectation: reported earnings per share fell 27%, and the price now books a European import quota that took effect in July.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NUE | Nucor | Integrated Steelmakers | 🟢 Cont. Bull | +2.2% | +88.4% |
MT | ArcelorMittal | Integrated Steelmakers | 🟢 Cont. Bull | +1.6% | +107.7% |
| Compared against · context, not the story | |||||
STLD | Steel Dynamics | Long Products & Rebar | 🟢 Cont. Bull | +6.2% | +70.6% |
CLF | Cleveland-Cliffs | Flat-Rolled Steel | 🟢 Cont. Bull | +16.4% | +7.7% |
RS | Reliance Steel & Aluminum | Diversified Metal Services | 🟢 Cont. Bull | +1.6% | +36.7% |
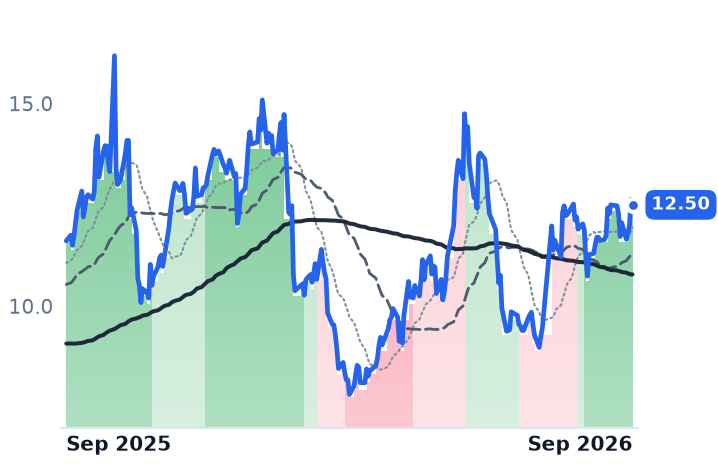
CMC | Commercial Metals | Long Products & Rebar | ⚠️ Emerging Bear | −1.6% | +11.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NUE | $56.6B | 19.8x | 13.0x | 1.6x | 1.4x | 10.1x | 9.0x | 10.9x | 2.8% |
MT | $55.2B | 30.3x | 16.3x | 0.9x | 0.8x | 9.1x | 8.6x | 9.9x | -2.5% |
STLD | $34.7B | 21.9x | 14.4x | 1.7x | 1.5x | 11.6x | 10.0x | 12.9x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLF | $5.9B | n/m | — | 0.3x | 0.3x | — | — | 101.5x | -17.0% |
RS | $18.5B | 23.2x | 18.4x | 1.2x | 1.1x | 4.6x | 4.2x | 14.5x | 3.3% |
CMC | $7.9B | 15.6x | 11.1x | 0.9x | 0.9x | 5.3x | 4.9x | 11.9x | 5.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NUE | Revenue | +23.9% | +1.9% | +0.0% |
| EPS | +140.4% | +2.7% | −4.8% | |
MT | Revenue | +8.0% | +5.3% | — |
| EPS | +7.0% | +67.9% | — | |
STLD | Revenue | +29.2% | +0.5% | +0.2% |
| EPS | +111.9% | +15.0% | −5.4% | |
CLF | Revenue | +9.2% | +2.3% | +0.6% |
| EPS | −78.7% | −155.5% | +40.0% | |
RS | Revenue | +12.8% | +0.2% | +0.9% |
| EPS | +33.5% | +7.7% | −5.3% | |
CMC | Revenue | +18.3% | +7.4% | +1.2% |
| EPS | +105.5% | +5.0% | −5.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
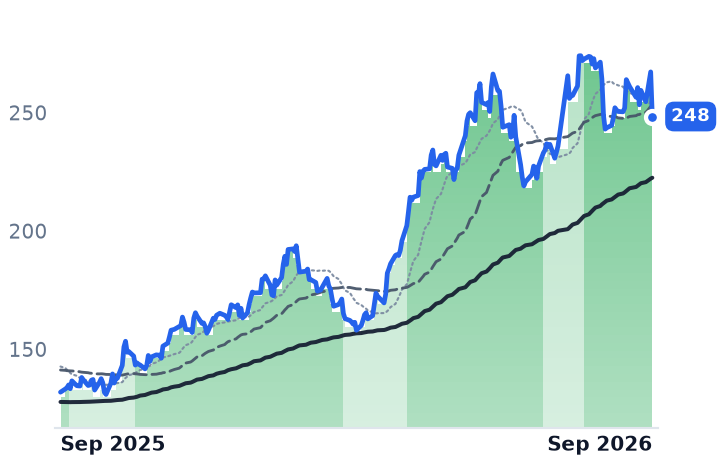
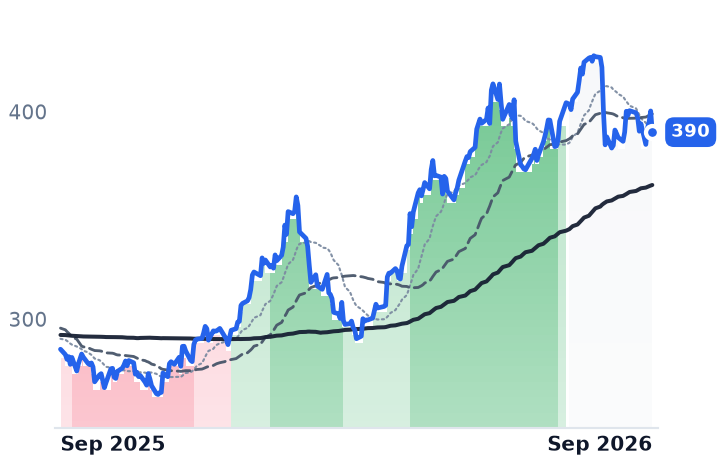
Nucor told investors on September 17 that third-quarter earnings would land between $5.55 and $5.65 a diluted share. Analysts were carrying roughly $6.17. The next session the Charlotte electric-arc-furnace producer — it melts recycled scrap into sheet, plate, bar and structural steel and fabricates joists, deck, racking and tube downstream — fell 7.1% on roughly three times normal volume, its sharpest single-day drop of the year and the first gap in a twelve-month advance that had otherwise been a grind. Its shorter moving average has stayed above its longer one every session for a year.
The guide missed expectations, not the business: the midpoint is about 11% above the $5.04 Nucor earned in the June quarter and more than double the $2.63 it earned a year earlier. What matters is which meter moved, because Nucor is not paid for "the steel price." It is paid the metal spread — realized price per ton minus the cost of the scrap it melts — times tons shipped, against a largely fixed conversion cost of power, electrodes and labor.
The spread, measured
In the June quarter the steel mills sold to outside customers at $1,145 a net ton, up 7% sequentially, while scrap and scrap substitutes cost $422 a gross ton, up 4-5%. Converted to the same 2,000-pound ton, the melt cost about $377, leaving a spread near $768. Output rose into it: a record 7.1m tons shipped and 91% mill utilisation, a second consecutive quarterly record. Group revenue grew 23% year on year while operating income grew 77%, and gross margin has climbed four quarters running, from 11.2% to 19.6%. The mills segment alone earned $1.6bn, nearly double the year-ago quarter. "The demand drivers across the spectrum are incredible," chief executive Leon Topalian said on the July 28 call.
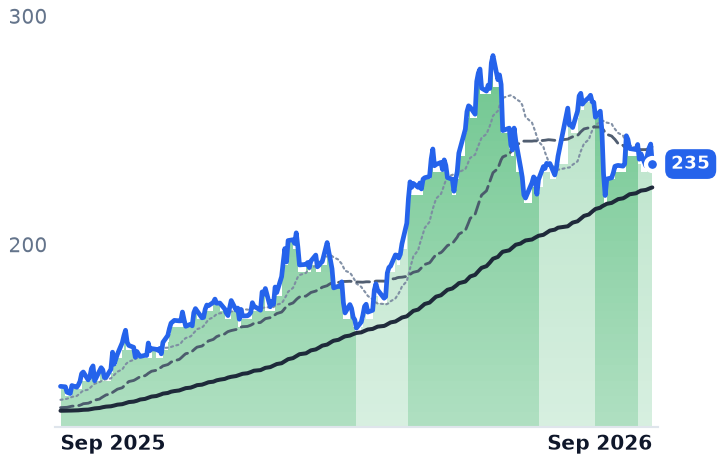
The same rising mill price is a cost inside Nucor. Steel Products earnings fell year on year as higher steel input costs more than offset volume and price; those plants ran at about 65% utilisation against 88% in the mills. The backlog still grew 10% sequentially, with joist and deck visibility into 2027 above realized pricing on warehouse, data-center and advanced-manufacturing work. And the scrap arm, which earned $146m in the quarter, is the one guided lower — Steel Dynamics split its own guide the identical way, steel operations significantly higher on metal margin, recycling lower, and fell 3.6% alongside.
The other side of the heading
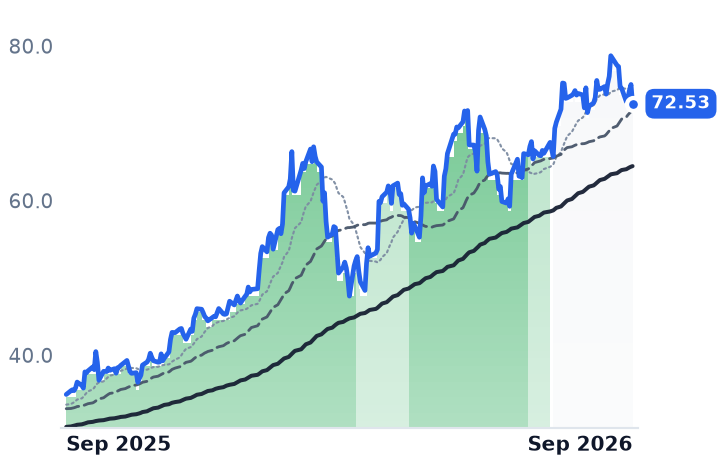
ArcelorMittal, the Luxembourg group that mines much of its own iron ore and runs blast furnaces across Europe and the Americas, is on the opposite meter. Its June-quarter EBITDA was $2.1bn, or $155 a tonne, with European EBITDA per tonne at a three-year high of $98 against $70 in March — real, and still far below Nucor's per-ton economics. Reported operating income fell 45% and net income 62%; trailing free cash flow is negative. "The implementation of the new tariff rate quota alongside CBAM is creating a more balanced competitive environment," chief executive Aditya Mittal said with those results. That quota, live since July 1, is expected to cut EU imports from 22.0m to 12.2m tonnes.
That is the whole difference. Nucor's 85% year came with trailing earnings per share up 126%, to $12.54, and its price-to-earnings ratio down to 19.8x from about 24x — below the 23.05x it carried in May. ArcelorMittal's 109% year came with trailing earnings per share down 27%, a ratio at 30.3x, and book value at 1.01x: payment in advance for a 2027 recovery consensus has not yet seen, 16.3x this year's estimate collapsing to 9.7x next year's. Nucor's 13.0x forward carries its own warning — the same consensus has earnings plateauing at $19.64 in 2027 and drifting to $17.44 by 2030.
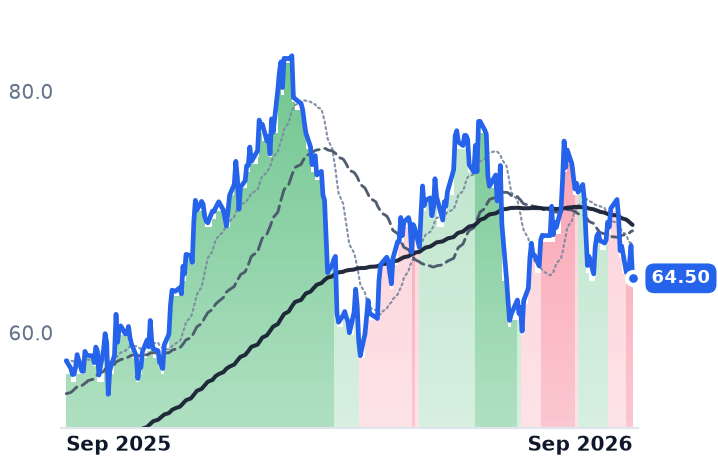
So the guidance day did not break the spread. Scrap settled flat at $420 in September, hot-rolled coil futures sit above $1,200 and maintenance outages will take about 1m tons out of the market this fall. What broke was the assumption that it keeps widening at June's pace, and the domestic mills had already given ground before the release: Nucor is down 6% over thirty days, Steel Dynamics 5.8%, Commercial Metals 9.1%. ArcelorMittal, whose earnings case is a regulation rather than a spread, barely moved.
Nucor repurchased about 2.03m of its own shares during the quarter at an average of $247.04. The close that followed its own guidance was below it.