

onsemi Promised $2.5bn of AI Data-Center Revenue by 2030 and Investors Marked It Down 7%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A company making its best long-term case was sold anyway, and so was everything standing next to it. onsemi used its investor day to raise its 2030 model — a 53% non-GAAP gross margin against roughly 40% this year, and more than $2.5bn of artificial-intelligence data-center revenue — hours before the Federal Reserve's first rate increase since 2023.
All six power-analog names peaked within days of June 18 and all are lower. The order of the falls tracks how far each had run rather than its exposure to AI sockets: the most automotive-levered name fell hardest, and Analog Devices, fresh off its first $4bn quarter at a 67.3% gross margin, fell least. Monolithic Power's data-center revenue more than doubled last quarter, and it is still the group's most expensive name on forward gross profit.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | −6.3% | +33.4% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +0.7% | +51.9% |
| Compared against · context, not the story | |||||
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | −11.6% | +30.7% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | −1.7% | +47.8% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −7.7% | +8.9% |
VICR | Vicor | Other | ⚠️ Emerging Bear | −0.4% | +301.9% |
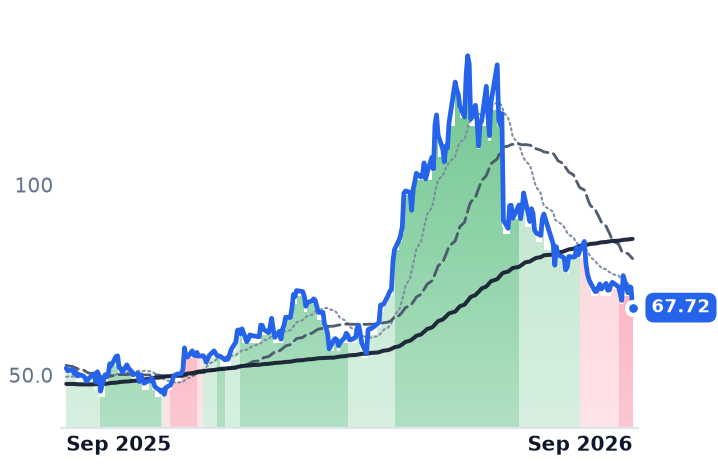
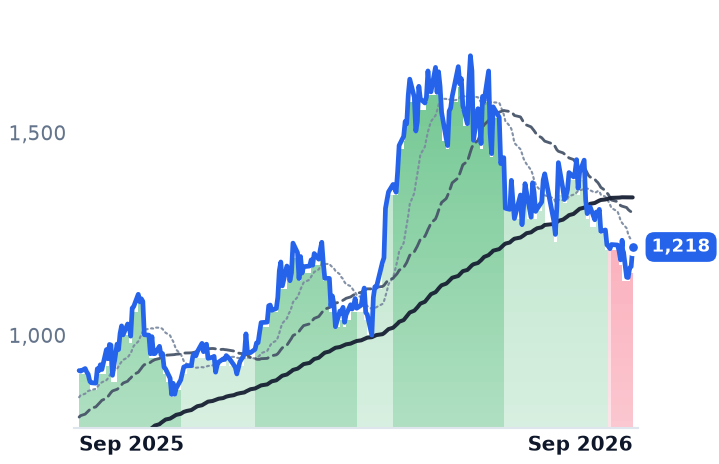
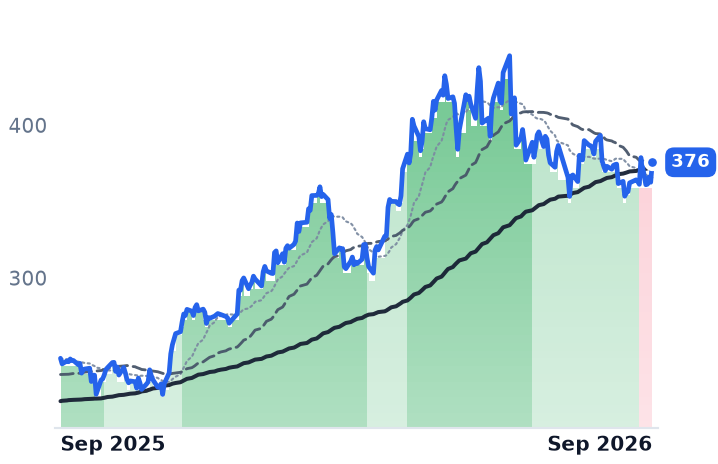
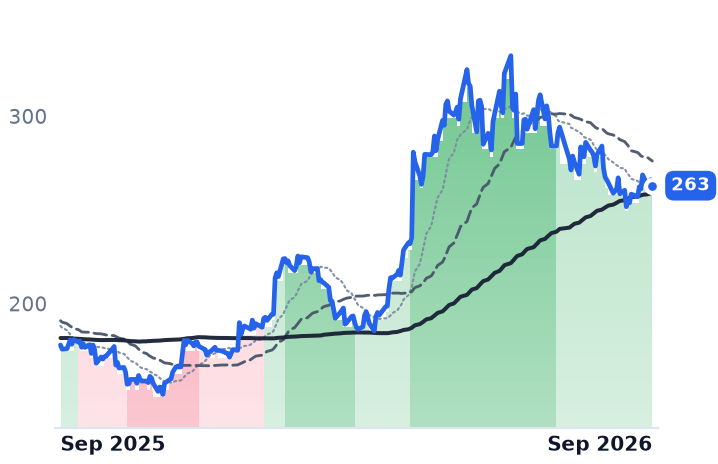
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $27.2B | 44.3x | 21.9x | 4.4x | 4.2x | 11.7x | 11.1x | 22.3x | 6.5% |
MPWR | $59.8B | 74.3x | 44.4x | 18.3x | 14.4x | 33.1x | 26.1x | 58.1x | 1.0% |
ADI | $183.0B | 44.4x | 29.2x | 13.2x | 12.1x | 20.0x | 18.4x | 29.1x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $240.6B | 39.9x | 31.0x | 12.4x | 11.0x | 21.2x | 18.8x | 27.6x | 2.2% |
MCHP | $40.3B | 102.8x | 20.4x | 7.9x | 6.3x | 13.1x | 10.5x | 27.0x | 2.8% |
VICR | $8.3B | 57.7x | 53.5x | 17.6x | 13.8x | 31.1x | 24.4x | 61.8x | 0.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.6% | +30.5% | |
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.2% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
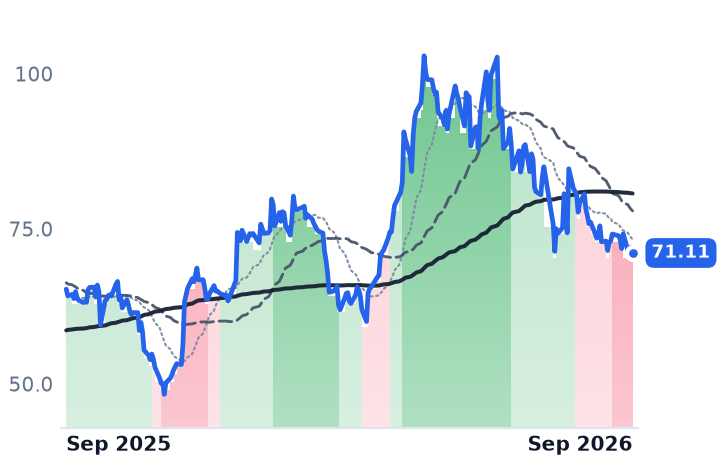
onsemi spent September 16 telling investors it would be a larger and far more profitable company by the end of the decade. The maker of power and sensing silicon — metal-oxide field-effect transistors, silicon carbide modules and image sensors sold into electric vehicles, charging infrastructure, solar and industrial power — targeted roughly $11bn of 2030 revenue on a 12–14% annual growth model raised from 10–12%, a 53% non-GAAP gross margin against about 40% this year, and more than $2.5bn of AI data-center revenue against roughly $500m in 2026. The same afternoon, the Federal Reserve raised its benchmark rate a quarter point to 3.75%–4% on a 12-0 vote, its first increase since 2023. By the following close onsemi had fallen 7.3%, to $67.73.
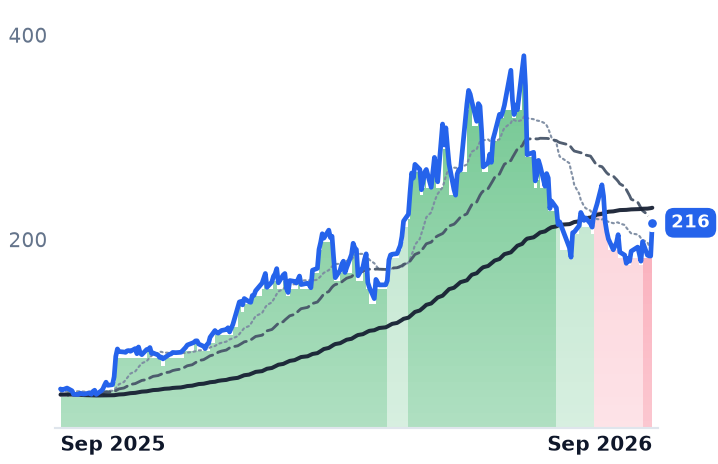
That pairing is the whole story of the analog power complex this quarter. Every one of the six names that supply voltage regulation and signal chain into data centers, cars and factories peaked within days of June 18, and every one is lower: onsemi is down 44.3% over three months, Vicor — which builds power modules and converters — 34.7%, Microchip Technology, the microcontroller and mixed-signal maker, 28.7%, Monolithic Power Systems 25.2%, Texas Instruments 18.6% and Analog Devices 16.5%. The ranking does not follow AI exposure. The most automotive- and industrial-levered name fell hardest; the name whose data-center line is growing fastest fell least. It follows how far each had run and how much current earnings sit underneath the price — which is what a discount rate does. The 10-year Treasury yield climbed back to 5% after the decision, and this is a group carrying 22x to 44x forward earnings.
The per-socket name kept accelerating
Monolithic Power designs the multi-phase controllers, power stages and vertical power modules that feed current to accelerators, and it is paid dollar content per platform rather than by volume of a catalog. Its second quarter, reported July 30, was the third straight acceleration — revenue up 47.6% to $980.6m after 26.1% and 20.8% growth in the prior two quarters. Enterprise data revenue reached $380.6m, up 164.3% from a year earlier, and 38.8% of the company against 32.7% three months before. Management raised its full-year enterprise-data growth target to 130% from 85%, citing new socket wins and higher module content. Gross margin sat flat at 55.2% while operating margin went from 26.6% to 31.0%, and inventory fell to 140 days of current-quarter revenue from 157.
"We focus on growing the revenue and growing the net profit, EPS," chief executive Michael Hsing told investors on the July 30 call, describing a shift from chip supplier to full solution provider.
The shares nonetheless moved from a strong uptrend as recently as June to a decisive downtrend, their 50-day average now below the 200-day. The one dated, name-specific cause inside the window is a September 14 Edgewater Research note questioning whether Monolithic Power keeps its slot on Nvidia's next platform, which took the stock down 7.39% that session. It remains an allegation: no confirmation of a lost socket has been published, and secondary accounts differ on which platform is at issue. Estimates have not moved down with the price — consensus calls for FY2026 earnings of $27.42 a share, up 54.8%, and 25 analysts carry an average target near $1,830 against a September 17 close of $1,169.58. What compressed was the multiple: trailing price-to-gross-profit is 33.1x, against 38.5x on August 18.
The catalog name printed the best quarter and fell least
Analog Devices sells tens of thousands of long-lived data converters, amplifiers and power parts, mostly through distributors, into industrial, automotive and communications customers. Its July quarter was the first $4bn quarter in company history, revenue up 39.6% to $4.02bn, with GAAP gross margin at 67.3% and operating margin at 40.1% against 31.5% two quarters earlier. Industrial grew 53% and is 49% of revenue; communications grew 84%, and data center is now 80% of that segment. Book-to-bill is above one but, management said on the August 19 call, "not unusually elevated," with distributor channel weeks deliberately held below the 6-to-7-week target. Pressed on durability, the chief financial officer grounded the outlook in "bookings momentum, design activity, and pipeline visibility" rather than "hopes and dreams."
Texas Instruments, which owns its fabs and earns on loading them, shows the same pattern: June-quarter revenue up 22.8% to $5.46bn, gross margin recovered to 61.4% from 57.7%, operating margin 42.3% — and shares down almost a fifth in three months.
What the falls earn
On forward gross profit, the comparable measure when margins run from onsemi's 38% to Analog Devices' 67%, Monolithic Power is still the most expensive of the four at 26.1x, ahead of Texas Instruments at 18.8x, Analog Devices at 18.4x and onsemi at 11.1x. That ordering is the verdict. Monolithic Power's quarter-long fall is a level correction on a premium that survived it, not a response to anything in the print — the open question there is a research allegation about a future platform, which no filing has yet answered. Analog Devices was marked closest to its own numbers. onsemi is the one the market treated hardest while pricing it cheapest, and it is the name promising AI content it has largely not booked, with 9.2% revenue growth and a 38.4% gross margin last quarter; sell-side cuts after the investor day, Stifel to $75 and Truist to $91, both still sit above the price.
The common factor is the cost of money, and a group that re-priced together on a rate decision is a group that will not sort itself by socket content on the way back. Sixteen of eighteen Fed participants project at least one further increase. On September 18 both Monolithic Power and Analog Devices rose, the first session since the hike in which the direction was genuinely in doubt.