

Home Depot's $1,000-Plus Purchases Grew 2.4% as Existing-Home Sales Fell to a 14-Month Low
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
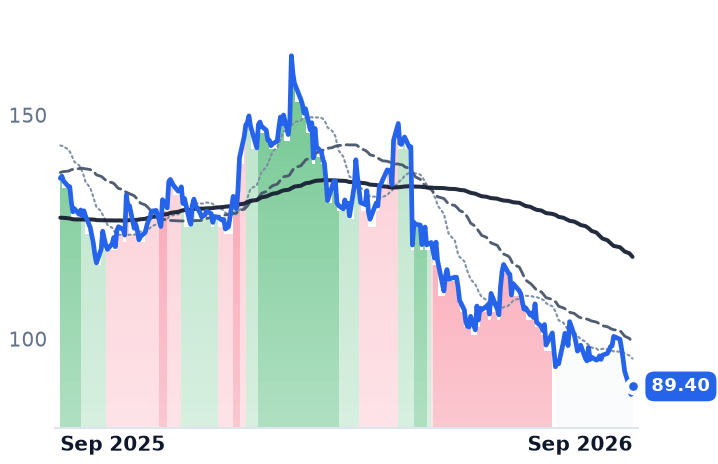
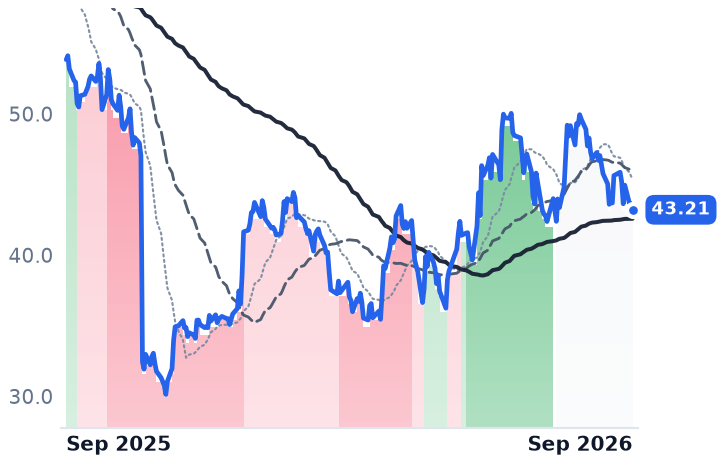
The first thing a household is supposed to defer when mortgages stop being originated is the big-ticket purchase — and at Home Depot it grew. Comparable transactions over $1,000 rose 2.4% in the August quarter, 13 of 16 merchandising departments comped positive, and the full-year guidance issued in December has not been touched. The shares are down about a quarter over twelve months anyway.
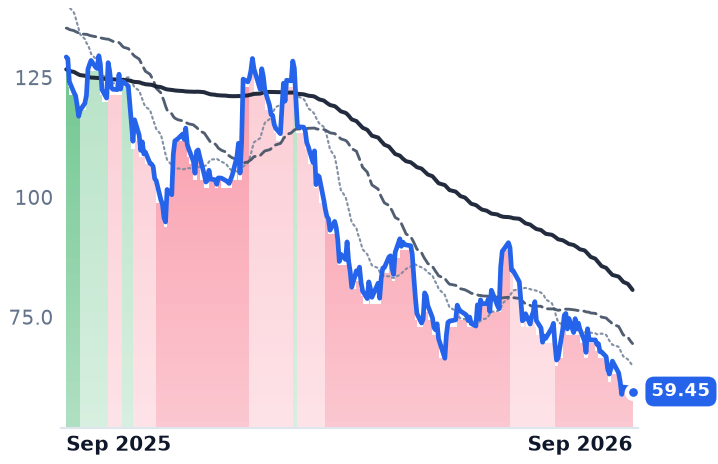
The repricing is being done on housing turnover, which management put at roughly 3% of the stock, not on these income statements: Lowe's fell almost exactly as far as Home Depot on visibly weaker comparable sales of 0.2%. Only one growth engine actually broke. Floor & Decor cut planned 2026 openings to 20 stores from 25, and its adjusted earnings of $0.58 a share were flat year over year once a one-time tariff refund is stripped out.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
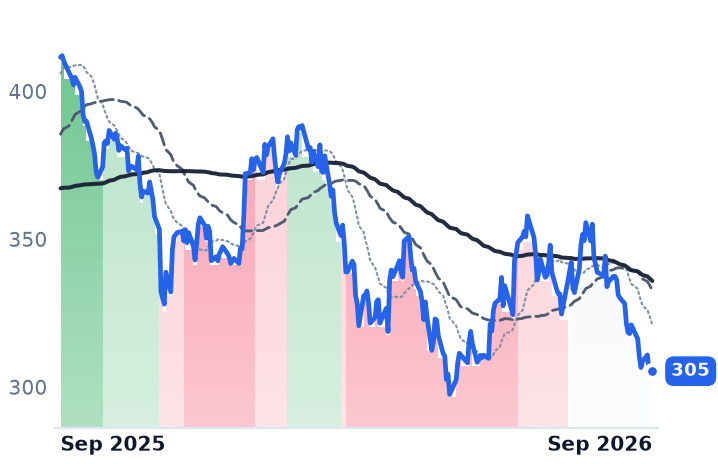
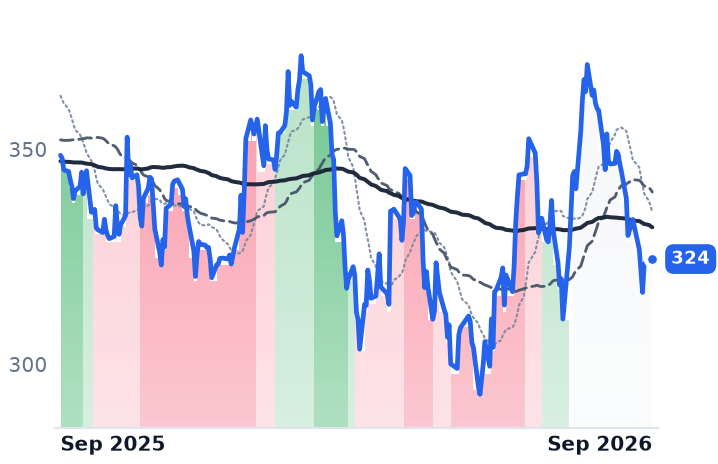
HD | The Home Depot | Home Improvement | 🔴 Cont. Bear | −9.5% | −25.8% |
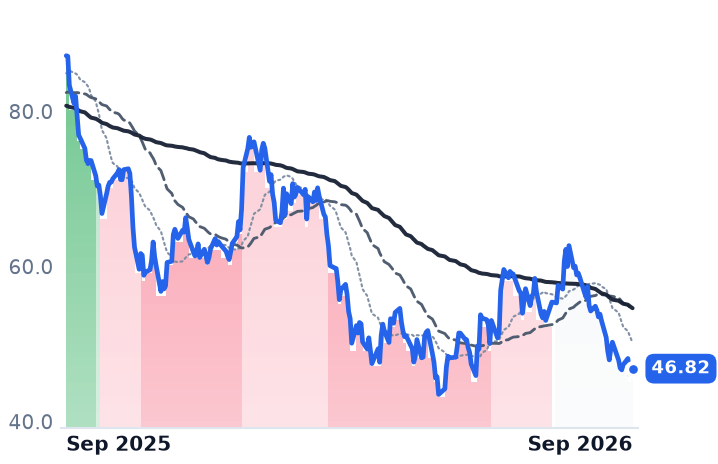
FND | Floor & Decor | Home Improvement | 🔴 Cont. Bear | −16.5% | −46.3% |
| Compared against · context, not the story | |||||
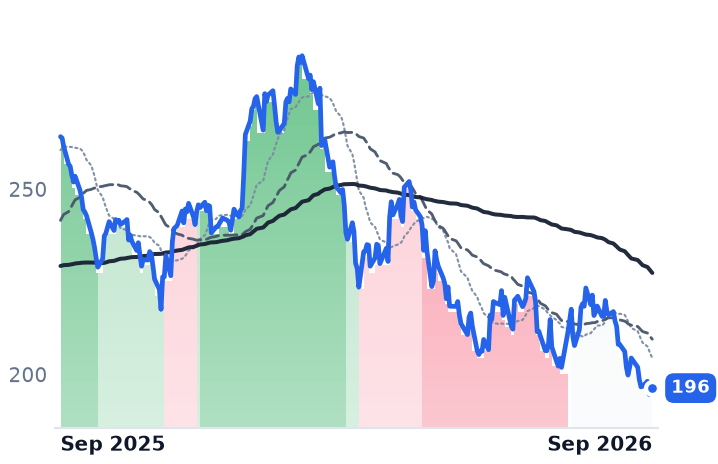
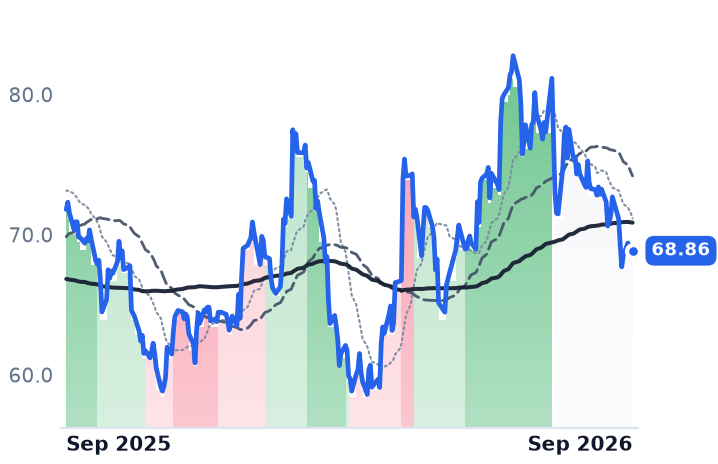
LOW | Lowe's Companies | Home Improvement | ⚠️ Emerging Bear | −9.0% | −25.7% |
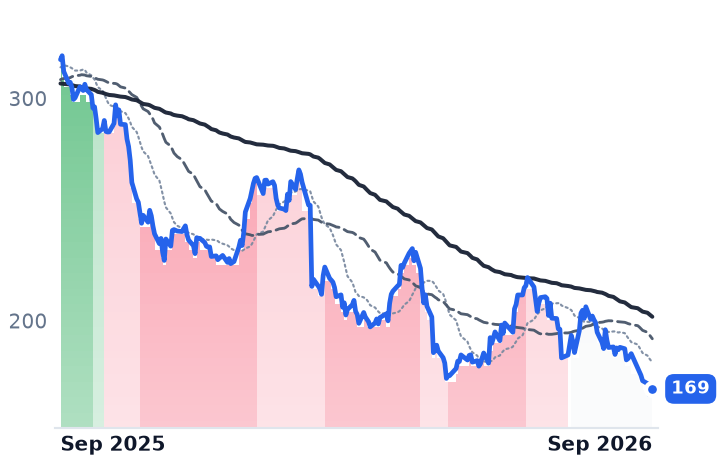
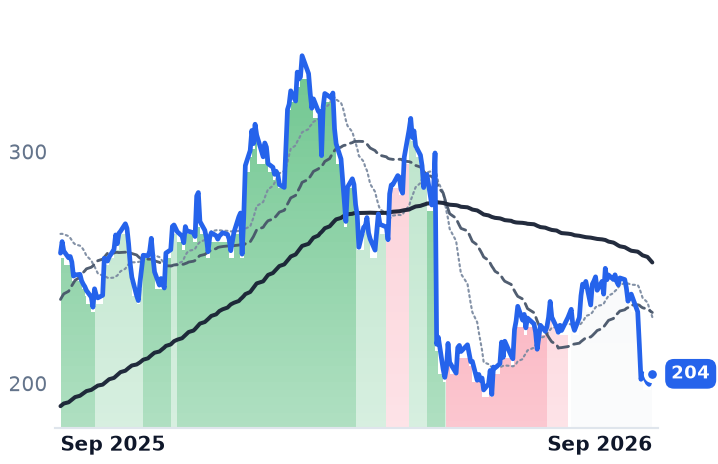
POOL | Pool | Specialized Building Products | 🔴 Cont. Bear | −9.7% | −46.7% |
SITE | SiteOne Landscape Supply | Specialized Building Products | ⚠️ Emerging Bear | −6.0% | −34.2% |
BLDR | Builders FirstSource | Building Envelope & Insulation | 🔴 Cont. Bear | −12.1% | −54.0% |
IBP | Installed Building Products | Building Products & Installation | ⚠️ Emerging Bear | −14.4% | −20.3% |
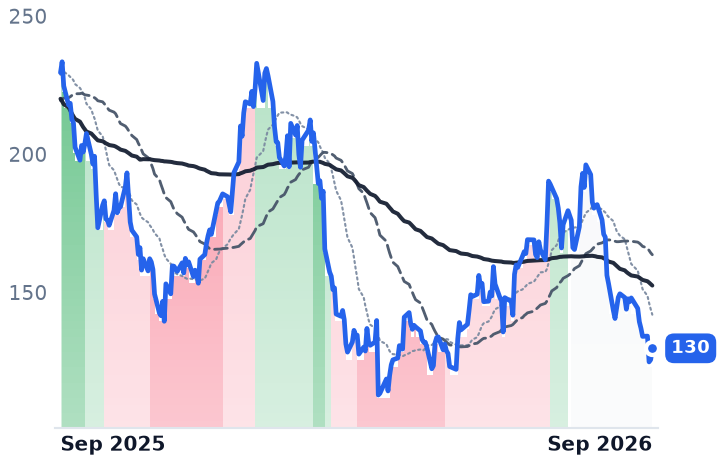
RH | Rh | Home Furnishings & Decor | 🌱 Emerging Bull | −24.1% | −43.5% |
TREX | Trex | Outdoor Living & Specialty | 🌱 Emerging Bull | −9.5% | −19.7% |
SHW | The Sherwin-Williams | Paints & Coatings | 🔴 Cont. Bear | −6.0% | −6.9% |
MAS | Masco | Plumbing & Bath Fixtures | 🌱 Emerging Bull | −6.2% | −4.1% |
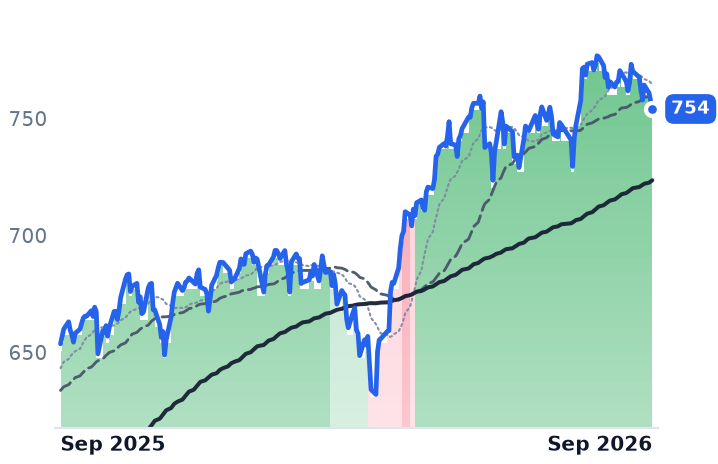
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.7% | +15.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HD | $304.5B | 21.3x | 20.3x | 1.8x | 1.8x | 5.4x | 5.3x | 15.3x | 5.0% |
FND | $5.0B | 21.8x | 23.7x | 1.1x | 1.0x | 2.4x | 2.3x | 11.9x | 4.2% |
LOW | $109.9B | 16.6x | 16.0x | 1.2x | 1.2x | 3.7x | 3.6x | 12.2x | 6.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POOL | $6.4B | 15.7x | 15.8x | 1.2x | 1.2x | 4.0x | 4.0x | 12.4x | 9.5% |
SITE | $5.2B | 34.4x | 27.1x | 1.1x | 1.1x | 3.2x | 3.0x | 16.4x | 4.7% |
BLDR | $6.5B | 65.6x | 19.3x | 0.4x | 0.5x | 1.5x | 1.6x | 11.3x | 9.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IBP | $5.6B | 22.0x | 20.5x | 1.9x | 1.9x | 5.7x | 5.7x | 9.1x | 1.1% |
RH | $2.3B | 18.5x | 23.4x | 0.7x | 0.6x | 1.5x | 1.5x | 12.5x | 10.8% |
TREX | $3.9B | 20.6x | 22.3x | 3.3x | 3.2x | 8.4x | 8.2x | 13.2x | 6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHW | $79.3B | 29.8x | 27.0x | 3.2x | 3.2x | 6.6x | 6.4x | 20.9x | 4.1% |
MAS | $13.1B | 15.8x | 15.2x | 1.7x | 1.7x | 4.8x | 4.8x | 11.6x | 7.2% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HD | Revenue | +3.6% | +4.2% | +3.4% |
| EPS | −4.2% | +3.6% | +6.4% | |
FND | Revenue | +3.6% | +5.2% | +8.4% |
| EPS | +3.5% | +11.4% | +20.4% | |
LOW | Revenue | +3.2% | +7.1% | +2.5% |
| EPS | +2.8% | +0.2% | +5.7% | |
POOL | Revenue | +2.4% | +3.8% | +4.7% |
| EPS | +1.9% | +8.6% | +9.8% | |
SITE | Revenue | +5.0% | +5.0% | +4.9% |
| EPS | +18.1% | +21.7% | +19.4% | |
BLDR | Revenue | −6.1% | +4.0% | +4.4% |
| EPS | −55.7% | +42.4% | +25.0% | |
IBP | Revenue | −0.4% | +4.5% | +7.0% |
| EPS | −6.9% | +10.7% | +18.3% | |
RH | Revenue | +8.5% | +4.3% | +9.3% |
| EPS | +19.8% | −24.0% | +74.2% | |
TREX | Revenue | +4.7% | +6.0% | +8.9% |
| EPS | −8.2% | +10.5% | +21.0% | |
SHW | Revenue | +6.8% | +4.5% | +4.6% |
| EPS | +6.5% | +12.3% | +10.9% | |
MAS | Revenue | +2.4% | +3.2% | +3.6% |
| EPS | +8.7% | +9.9% | +10.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Home Depot's biggest baskets are still being rung up. Comparable transactions over $1,000 — the roof replacement, the kitchen, the riding mower — rose 2.4% in the quarter reported on 18 August, according to trade coverage of the results, and 13 of the retailer's 16 merchandising departments posted positive comparable sales. Monthly comps improved through the quarter, from 0.5% in May to 2.2% in July.
That is not the record of a business the market has marked down by roughly a quarter in a year, and the gap is the story of the whole repair-and-remodel complex right now. What has been repriced is the rate at which American houses change hands, not what the two largest home-improvement retailers reported. Inside that repricing, exactly one of the two growth engines investors paid up for has actually been impaired — and it is not the $18bn one.
The basket has two halves
A home-improvement dollar is earned per basket, and the halves move independently. Home Depot's comparable transactions fell 1.0% while comparable average ticket rose 2.8% — fewer projects, each costing more, with the average transaction at $92.50. Lowe's, the more do-it-yourself-weighted of the two, saw transactions fall 2.1% as customers chose repair and maintenance over renovation.
What opens a big basket is a house changing hands, and houses are not changing hands. Existing-home sales fell 2.0% in August to a 3.98m annual rate, a third straight monthly decline and a 14-month low. Home Depot management puts turnover at roughly 3% of the housing stock. Financing moved the wrong way through the period: Freddie Mac's 30-year fixed averaged 6.76% in the week to 10 September against 6.35% a year earlier, with daily screens above 7%, after the 10-year Treasury crossed 5% and the Federal Reserve raised rates a quarter point on 16 September.
"While consumer uncertainty and housing affordability continue to pressure demand for larger home improvement projects, we remain focused on what we can control," chief financial officer Richard McPhail told investors on 18 August.
The engine Home Depot bought is running
SRS Distribution, acquired for $18.25bn in 2024, is not a store: it sells roofing, pool and landscape materials per job to contractors on trade credit and delivers to the site from hundreds of branches. SRS then bought drywall distributor GMS for $5.5bn, closing in September 2025, taking Home Depot's spend on stapling a wholesale distributor onto a retailer's income statement close to $24bn. Revenue growth has accelerated for three quarters, from −3.8% to 4.8% to 5.7%, and SRS comped above the company average with positive sales in every vertical.
The acceleration is bought, and the price shows. Acquired distribution diluted gross margin by 60 basis points, operating margin slipped to 14.29% from 14.48%, return on invested capital fell to 24.8% from 27.2%, and inventory turns eased to 4.5x. A $730m refund of tariffs collected under the International Emergency Economic Powers Act added 145 basis points to gross margin and masked input-cost pressure; McPhail told the same call he expects fourth-quarter gross margin "to be relatively flat versus last year." The full-year outlook first issued in December 2025 — comparable sales flat to 2%, earnings per share flat to up 4% — has not been cut.
Floor & Decor slowed the compounding
The hard-surface flooring specialist is the genuine growth-engine casualty. Comparable store sales fell 2.1% in its quarter ended June, and the reported blowout — 48.2% gross margin, operating income up 51.4% — is a $56.2m tariff refund worth 450 basis points. Adjusted gross margin was 43.9% against 43.8%. "We are pleased to have delivered adjusted diluted earnings per share of $0.58, unchanged from the prior year period, despite a 2.1% decline in comparable store sales driven by continued softness in large discretionary flooring projects," chief executive Brad Paulsen said on 30 July.
Operating expenses rose to roughly 38.3% of sales from 37.1% — the fixed occupancy and pre-opening cost of putting up warehouses into negative comps. So the company cut the opening rate to 20 new stores for 2026 from 25 in 2025, on a 281-store base against a stated 500-store target, and shrank the format to about 55,000 square feet. Capitalized at roughly 45x earnings a year ago, it trades at 21.8x trailing and 23.7x forward — the forward multiple sits above the trailing one because the market is discounting an earnings base inflated by refunds. Guidance still contemplates comps anywhere from down 4% to flat.
The market did not discriminate
Lowe's comped 0.2% against Home Depot's 1.7% and moved full-year adjusted earnings to about $12.25 a share, the low end of its range; its shares fell 27.0% over twelve months against Home Depot's 26.8%. Home Depot trades at 21.3x trailing and 20.3x forward against roughly 28x a year ago; Lowe's at 16.6x and 16.0x. Over the trailing month Builders FirstSource fell 14.2%, Installed Building Products 17.2% and RH 28.7%, against 2.4% for the S&P 500 tracker. Home Depot's own slide from $344.30 on 19 August to $305.48 on 15 September came in nineteen sessions with none worse than about 2%, and no company news to pin it on beyond a Bernstein target cut to $344 on 9 September and chief executive Ted Decker's temporary medical leave announced on 12 August.
Floor & Decor's de-rating is earned: flat adjusted earnings, negative comps and a self-cut unit-growth rate are what a compounder losing its compounding looks like. Home Depot's is not earned on the quarter it reported — but consensus has it earning $15.01 in the year to February 2027 against $14.23 actually earned last year, so 20x is cheap only against its own history, not against the growth being guided to. The sharper tell sits outside both names: POOL Corp and SiteOne, the listed pure-plays in two of SRS's three verticals, are down 47.9% and 34.2% over twelve months. Per-job contractor distribution is being marked down harder in public than Home Depot's own disclosure of it suggests.
The November quarter is the test of whose meter is right. Home Depot has kept a guidance range intact through three rate moves against it; if the transaction that triggers a renovation keeps not happening, the ticket half of the basket has to carry a second year alone.