

Select Water Signed a 12-Year Contract Covering 875,000 Permian Acres as Sand Prices Sank
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two Permian oilfield-services names that look like one trade are paid on two different meters, and over the last month the market has been paying the wrong one more. Select Water Solutions collects a fee per barrel of produced water gathered, recycled and disposed; its Water Infrastructure segment earned a record $101.6m in the June quarter at a 58% gross margin before depreciation, and on 18 August it locked a twelve-year dedication over more than 875,000 acres.
Atlas Energy Solutions is paid per ton of Permian sand, and sold 5.6m tons at $17.70 in the same quarter — its fourth consecutive operating loss. But Atlas is converting into contracted infrastructure too, through a 120-megawatt power agreement that books no revenue until the second quarter of 2027. Over the past thirty days the sand name rose and the water name fell.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
WTTR | Select Water Solutions | Water Services & Energy Solutions | 🟢 Cont. Bull | −3.7% | +115.2% |
AESI | Atlas Energy Solutions | Proppant & Logistics | 🔴 Cont. Bear | +7.3% | +22.8% |
| Compared against · context, not the story | |||||
SND | Smart Sand | Oil & Gas Equipment & Services | 🟢 Cont. Bull | +7.0% | +175.6% |
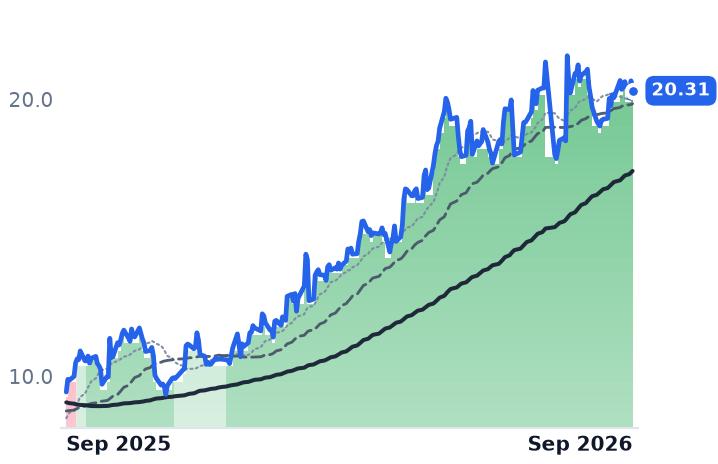
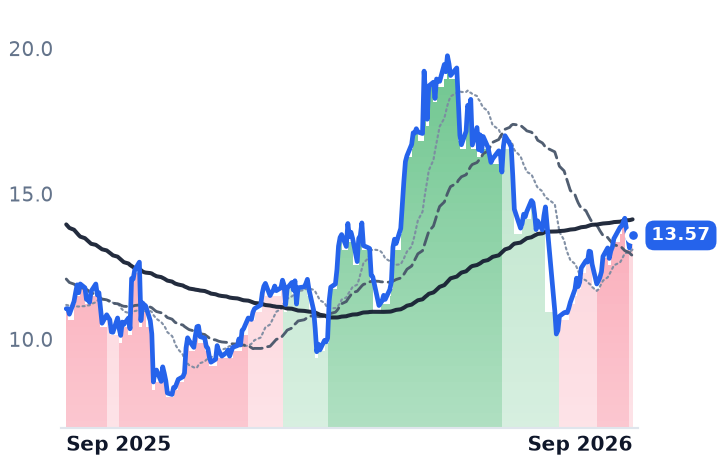
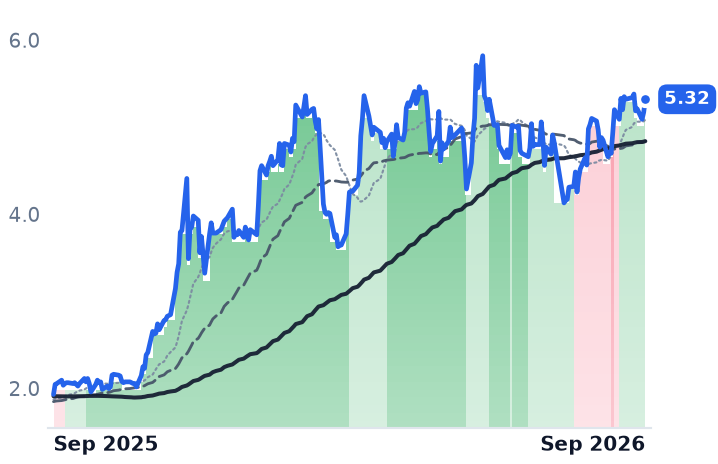
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WTTR | $2.2B | 75.0x | 30.9x | 1.6x | 1.4x | 8.2x | 7.6x | 10.5x | -3.7% |
AESI | $1.7B | n/m | — | 1.6x | 1.5x | 38.2x | 36.6x | 22.5x | -10.9% |
SND | $222.7M | 19.2x | 52.3x | 0.6x | 1.0x | 4.4x | 7.6x | 8.1x | 15.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WTTR | Revenue | +12.0% | +4.8% | +6.2% |
| EPS | +169.0% | +11.4% | +59.6% | |
AESI | Revenue | +2.5% | +14.8% | +18.8% |
| EPS | +109.2% | −80.1% | −299.1% | |
SND | Revenue | −25.4% | — | — |
| EPS | −47.9% | — | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
A fee per barrel, signed for twelve years
Select Water Solutions, which gathers, recycles and disposes of the water that comes up Permian oil wells alongside the crude, amended an agreement with a large investment-grade public operator on 18 August, stretching its term to twelve years and adding 256,000 newly dedicated acres. The combined agreement now covers more than 875,000 acres across Eddy and Lea counties, New Mexico and Culberson county, Texas, and commits Select to build roughly 100 miles of pipeline, three million barrels of storage and 60,000 barrels a day of recycling capacity for $100–120m, operational by the end of 2027.
That is not a drilling contract. Select earns a fee on each barrel of produced water it handles, and Permian wells lift three to four barrels of water for every barrel of oil, more as they age. The basin produced more than 20m barrels of water a day in 2024, a volume forecast to grow about 39% by 2035, while regulators restricting disposal wells for injection-induced seismicity shrink the cheap alternative. Completions, the meter everyone assumes an oilfield company runs on, are doing the opposite: Primary Vision's frac-spread count read 178 in the week to 4 September, its lowest since May, before recovering to 184 the following week.
The accounts show the mix working. June-quarter revenue of $395.8m rose 8.7% year on year while operating income more than doubled to $34.3m. Water Infrastructure posted record revenue of $101.6m, up 26%, at a 58% gross margin before depreciation, against roughly 23% in Water Services and 20% in Chemical Technologies. The same quarter brought a seven-year Northern Delaware deal backed by a 128m-barrel minimum volume commitment, under which the operator handed Select 14 saltwater disposal wells. "For that operator to give us the amount of disposal wells because of the really game-changing application of recycle first," chief executive John Schmitz told investors on 5 August.
None of it is free. Full-year capital spending was raised to $250–290m against maintenance needs near $60m, and trailing free cash flow is negative, a yield of minus 3.7%. Select trades at 10.5x trailing earnings before interest, tax, depreciation and amortization, and about 31x forward earnings on consensus that nearly triples 2025's depressed result. Measured against gross profit, the shares cost 8.18x, versus 5.34x in early May. Their 50-day average has sat above the 200-day since late December, but the stock has slipped 3.3% over the past thirty days.
The mirror, one asset class over
Atlas Energy Solutions mines and delivers frac sand in the Permian, largely over its own conveyor and truck fleet. In the June quarter it moved 5.6m tons at an average $17.70 a ton against $12.39 of plant operating cost — a 5.9% gross margin where a year earlier it was 18.1%, and a $20.0m operating loss, the fourth in a row. Third-quarter adjusted EBITDA is guided to $30–45m after $49.5m delivered, roughly 60% of that gap a deliberate choice. "What we're trying to do... is shine a light on the true productive capacity of the market," chief financial officer Blake McCarthy said on the 3 August call.
The tidy story would be contracted barrels against spot tons. It is wrong in one direction: Atlas is running the same conversion, in electricity. It suspended its dividend in November 2025 to fund the pivot, and its first behind-the-meter agreement covers 120 megawatts at Socorro, Texas on an initial five-year term with two five-year extensions, roughly $190m of capital for $50–55m of annualized adjusted free cash flow. Chief executive John Turner told investors on 3 August that "2 to 4 projects could contract our remaining uncommitted capacity compared with our previous assumption of 8 to 10." Revenue recognition begins in the second quarter of 2027.
Smart Sand, which ships Northern White sand into Appalachian gas basins, grew June-quarter revenue 34% to $115.1m at a 17.2% gross margin. The proppant squeeze is a Permian in-basin price war, not a collapse in sand demand.
What the businesses earn
Select's numbers earn the direction of its re-rating but not its pace: gross profit grew a third year on year while the multiple paid on that gross profit expanded by about half in four months. Atlas's decline has not made it cheap — trailing EV/EBITDA has widened from 14.2x in early August to 22.5x, because earnings fell faster than the share price. Over the last thirty days Atlas rose 6.9% and Select fell; the likelier reading is that the market has started paying for power contracts that have not yet billed, and stopped paying up for water contracts that already do.
Both companies are spending cash now against revenue that does not arrive until 2027 — Select's new pipe, Atlas's first permanent megawatts. The meters differ. The wait does not.