

Roper Put $3.2bn Into Its Own Shares Instead of Software Deals, on 5% Organic Growth
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Roper Technologies is an acquisition machine that spent this year buying itself. The company owns 29 businesses, 21 of them software, and normally recycles free cash flow into niche vertical-software companies; in 2026 it has retired 5.4% of its shares instead, while reported revenue growth slowed to 8.5% in the June quarter.
Management's own standard explains the choice: acquisitions must underwrite at roughly six to eight times year-five earnings before interest, taxes, depreciation and amortization, and few assets cleared it. Net debt has reached 3.4 times EBITDA, and the near-term priority is paying it down.
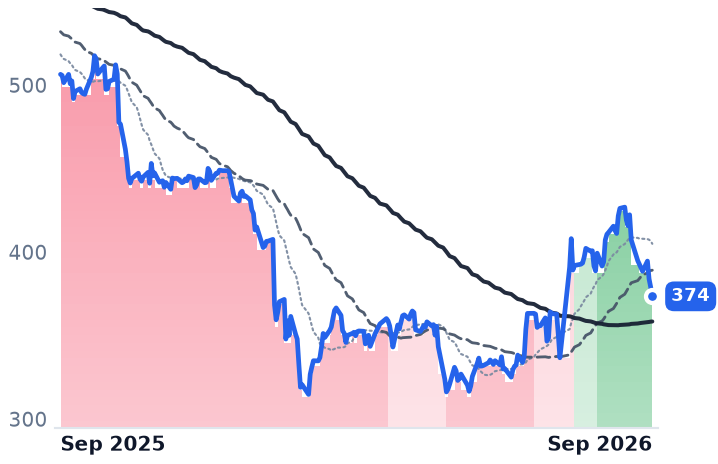
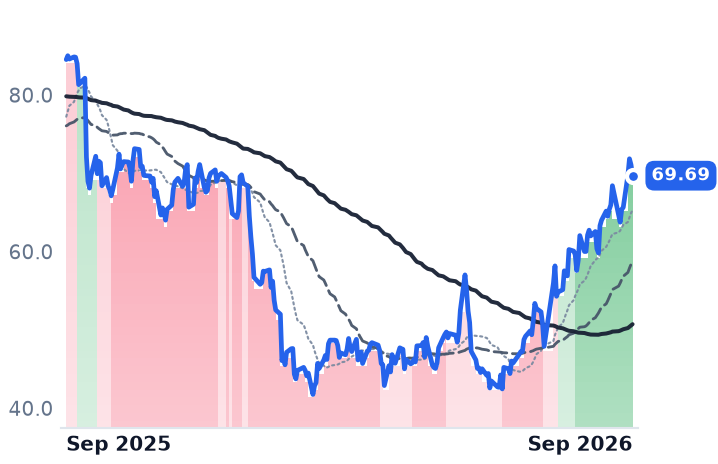
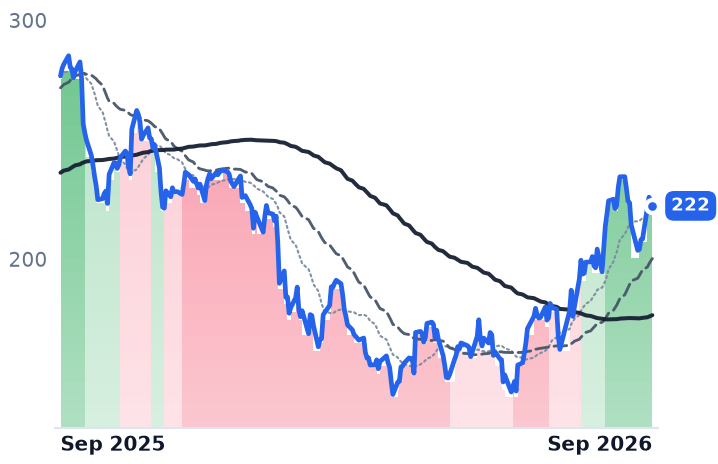
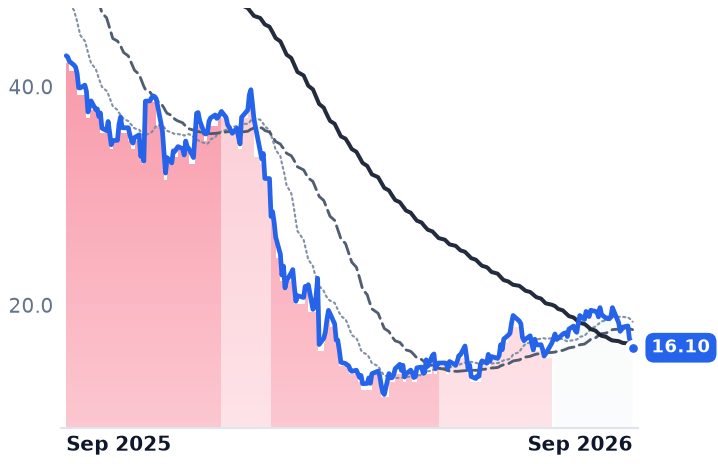
The shares have risen since June without re-rating at all — 16.9 times forward earnings against roughly 26.6 times on last year's average price. Investors are being handed a smaller denominator, and so far nothing more.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ROP | Roper Technologies | Specialized Enterprise Solutions | 🌱 Emerging Bull | −5.2% | −26.3% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🟢 Cont. Bull | −13.6% | −28.7% |
| Compared against · context, not the story | |||||
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +17.4% | −26.2% |
BSY | Bentley Systems, Incorporated | Specialized Enterprise Solutions | 🌱 Emerging Bull | −10.4% | −40.9% |
DOCU | DocuSign | Specialized Enterprise Solutions | 🌱 Emerging Bull | +16.1% | −17.5% |
INTA | Intapp | Specialized Enterprise Solutions | 🔴 Cont. Bear | −7.3% | −18.0% |
MANH | Manhattan Associates | Specialized Enterprise Solutions | 🔴 Cont. Bear | +6.7% | −1.5% |
PTC | PTC | Specialized Enterprise Solutions | 🔴 Cont. Bear | −11.0% | −36.1% |
APPF | AppFolio | Specialized Enterprise Solutions | 🌱 Emerging Bull | +9.0% | −19.7% |
BLKB | Blackbaud | Specialized Enterprise Solutions | 🌱 Emerging Bull | −0.0% | −35.8% |
DSGX | The Descartes Systems | Specialized Enterprise Solutions | 🔴 Cont. Bear | +5.1% | −20.9% |
AGYS | Agilysys | Specialized Enterprise Solutions | 🌱 Emerging Bull | −6.4% | −2.3% |
PAR | PAR Technology | Specialized Enterprise Solutions | 🔴 Cont. Bear | −17.1% | −62.4% |
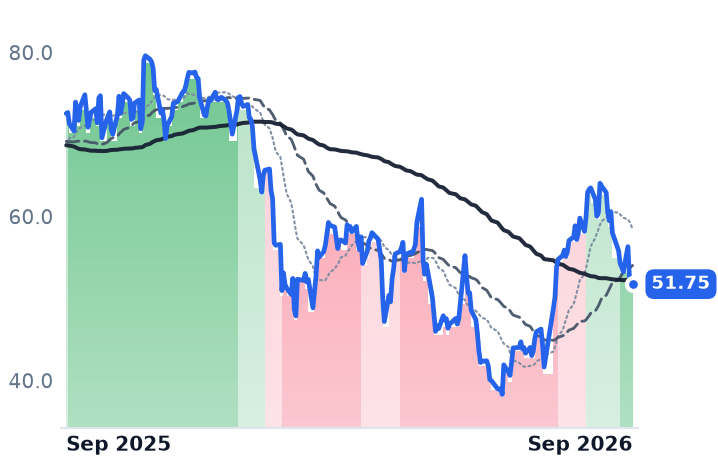
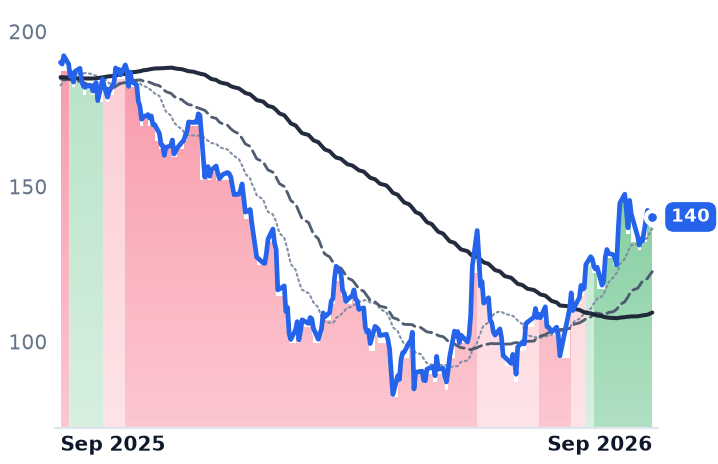
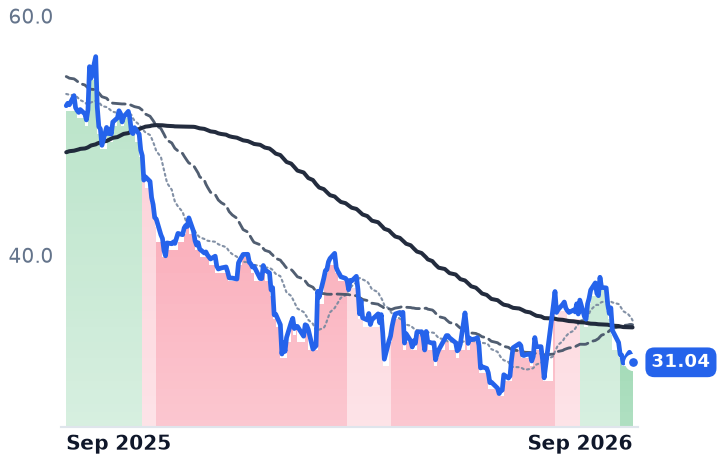
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ROP | $37.8B | 15.5x | 16.9x | 4.6x | 4.4x | 6.6x | 6.3x | 10.8x | 6.9% |
PCOR | $7.8B | n/m | 30.8x | 5.5x | 5.2x | 6.9x | 6.5x | 122.0x | 3.8% |
NOW | $143.2B | 86.0x | 34.0x | 9.7x | 8.8x | 13.0x | 11.8x | 42.7x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BSY | $9.2B | 34.1x | 22.4x | 5.7x | 5.4x | 7.0x | 6.6x | 20.5x | 5.4% |
DOCU | $13.5B | 42.3x | 15.3x | 4.0x | 3.8x | 5.0x | 4.8x | 20.8x | 8.9% |
INTA | $2.8B | n/m | 22.9x | 4.9x | 4.3x | 6.5x | 5.7x | n/m | 4.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MANH | $12.3B | 59.9x | 38.3x | 10.9x | 10.6x | 20.0x | 19.3x | 41.9x | 3.2% |
PTC | $15.5B | 13.0x | 16.4x | 5.3x | 5.7x | 6.3x | 6.8x | 10.0x | 6.0% |
APPF | $7.9B | 49.8x | 31.8x | 7.5x | 7.0x | 12.0x | 11.1x | 37.0x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BLKB | $2.0B | 13.3x | 8.3x | 1.7x | 1.7x | 2.9x | 2.8x | 9.6x | 14.2% |
DSGX | $6.8B | 36.2x | 34.3x | 8.8x | 8.2x | 12.5x | 11.7x | 19.1x | 4.4% |
AGYS | $2.9B | 66.8x | 41.6x | 8.7x | 7.8x | 14.0x | 12.5x | 43.1x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PAR | $659.1M | n/m | 20.8x | 1.3x | 1.3x | 3.4x | 3.3x | n/m | -2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ROP | Revenue | +8.1% | +5.9% | +5.6% |
| EPS | +11.5% | +9.5% | +9.2% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.1% | +46.2% | +20.2% | |
NOW | Revenue | +22.4% | +18.7% | +18.4% |
| EPS | +17.1% | +23.2% | +21.4% | |
BSY | Revenue | +13.6% | +10.5% | +10.2% |
| EPS | +18.4% | +12.2% | +16.3% | |
DOCU | Revenue | +8.4% | +9.2% | +8.0% |
| EPS | +6.9% | +22.1% | +12.8% | |
INTA | Revenue | +14.7% | +14.6% | +15.0% |
| EPS | +36.8% | +29.9% | +22.3% | |
MANH | Revenue | +8.3% | +8.6% | +8.8% |
| EPS | +10.3% | +11.8% | +15.3% | |
PTC | Revenue | +4.9% | +6.4% | +7.5% |
| EPS | +20.4% | +8.8% | +10.2% | |
APPF | Revenue | +18.5% | +17.4% | +18.7% |
| EPS | +33.8% | +22.8% | +28.6% | |
BLKB | Revenue | +4.5% | +4.6% | +3.2% |
| EPS | +18.8% | +13.8% | −37.2% | |
DSGX | Revenue | +15.0% | +12.7% | +12.8% |
| EPS | +15.8% | +24.5% | +15.1% | |
AGYS | Revenue | +16.5% | +16.6% | +16.9% |
| EPS | +26.9% | +49.3% | +30.3% | |
PAR | Revenue | +15.1% | +9.9% | +10.2% |
| EPS | +505.2% | +86.3% | +84.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Roper Technologies buys software companies for a living. This year, its largest purchase was itself.
The owner of Deltek (project accounting for government contractors), Vertafore (insurance agency systems) and Aderant (law-firm practice management) has put $3.2bn into its own stock in 2026, retiring 9.0m shares, including 3.6m for $1.2bn in the June quarter alone, according to its second-quarter disclosures. Diluted share count fell from 108.4m a year earlier to 102.6m. That 5.4% reduction, rather than any change in what the market will pay for the assets, accounts for most of what a shareholder earned per share.
This matters beyond one quarter of capital allocation because buying is the model. Roper describes itself as 29 businesses, 21 of them software, about $8.5bn of revenue, 40% EBITDA margins and free-cash-flow margins in the low 30s. Reported growth is capital deployment stapled to whatever the existing units produce on their own. Take deployment away and the underlying figure is visible: reported revenue growth has stepped down from 14.3% in the September 2025 quarter to 8.5% in June, of which five points were organic.
The arithmetic that pointed inward
Roper's stated test is that an acquisition must underwrite at roughly six to eight times year-five EBITDA, against a buyback that management frames as equivalent to about ten times. Few private assets met the standard this year. Net debt now sits at 3.4 times EBITDA, against roughly $5bn of annualized deal capacity, and the near-term plan is to rebuild that room by reducing debt. Chief executive Neil Hunn told the Goldman Sachs Communacopia + Technology Conference on 9 September that sponsor conversations have become "decidedly more constructive" as sellers accept the new valuation reality, and that he expects mergers and acquisitions to beat buybacks over a five- to seven-year horizon. At the same appearance management conceded that organic growth "has been harder to execute than hoped."
The operating business is not deteriorating. Second-quarter free cash flow rose 11% to $447m, trailing twelve-month free cash flow is $2.6bn, and full-year adjusted earnings guidance was raised for the second time, to $22.15–$22.30 a share with organic growth "in the 6% range." The Application Software segment grew 8% to $1.18bn on 5% organic growth, with enterprise gross retention in the mid-90s. Reported net income is less useful: the quarter's $1.169bn includes a $995.9m fair-value gain on Roper's stake in Indicor, whose instrumentation sale should bring about $1.3bn before tax, cash guidance excludes.
What the market has not done
Roper trades at 16.9 times consensus 2026 adjusted earnings of $22.22, against roughly 26.6 times on its 2025 average share price and 2025 earnings — a de-rating of about a third that this year's advance has not repaired. Measured against gross profit, the standard comparison when margins differ across a group, the shares cost 6.57 times trailing profit today versus 6.51 times in early May. The move off the June low is arithmetic, not appetite.
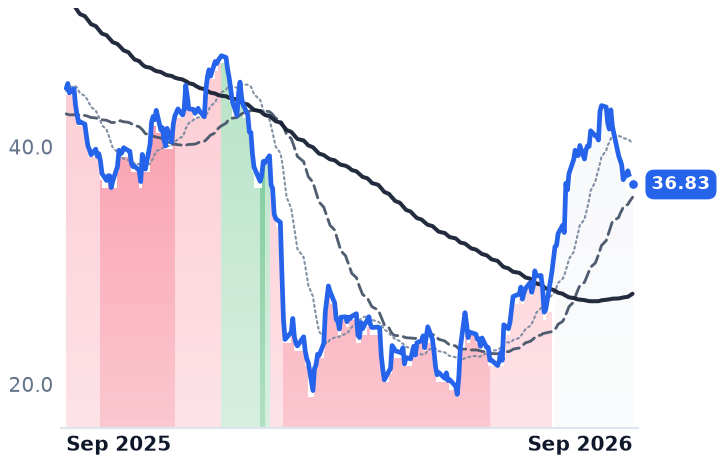
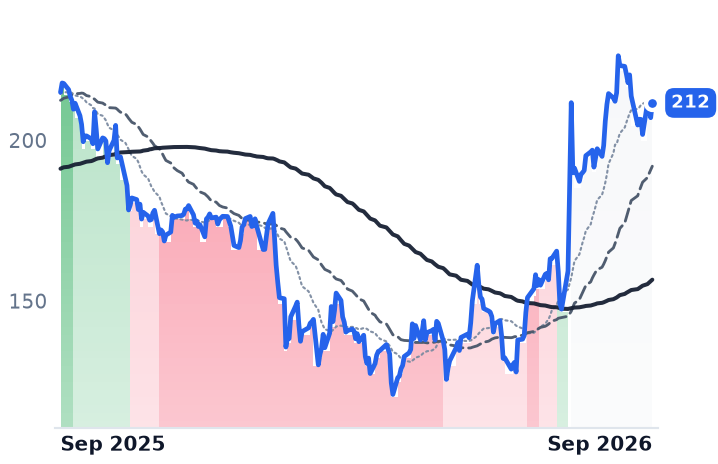
The de-rating was never about Roper. UBS downgraded ServiceNow on 10 April and cut its target to $100 from $170, arguing that artificial-intelligence infrastructure spending is crowding out core software budgets, with more than half of enterprise conversations now including talk of containing non-AI software spend. ServiceNow, which sells workflow automation to large enterprises, grew revenue 24% in the June quarter while its gross margin fell to 70.7% from 77.5% and operating income halved to $162m; at 34 times forward earnings it remains the most expensive name in this group. Hunn's answer is that Roper has seen no seat compression across its 21 software units, and that it is moving toward charging credits drawn down per task performed by software agents, on a use-it-or-lose-it basis.
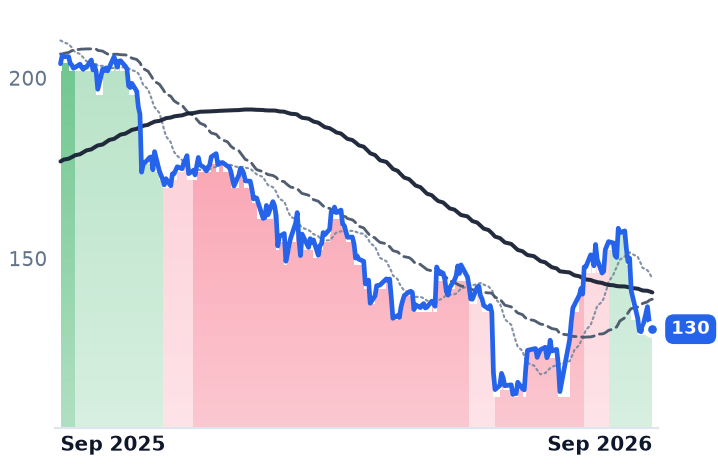
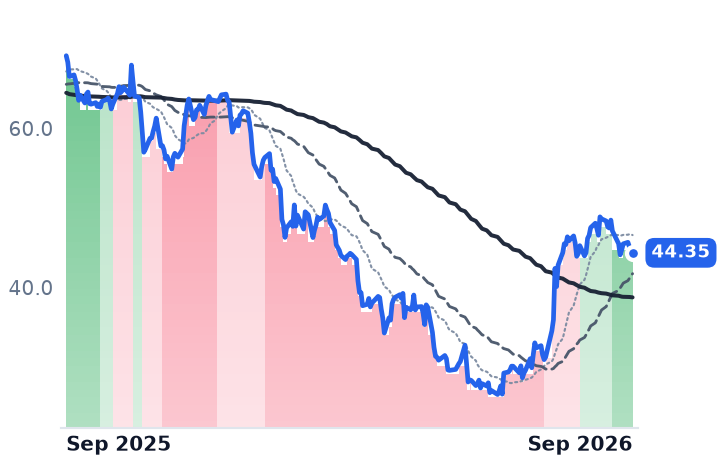
Contrast the meter at Procore Technologies, which prices construction-management software against the annual building volume a customer runs through the platform rather than by user: customers above $100,000 of annual recurring revenue rose 14% to 2,871 and now supply 68% of that revenue. Its shares cost less per dollar of gross profit than in the spring, 6.46 times forward against 7.96 times on 3 May. Improving disclosure, shrinking price.
So the honest reading of Roper's year is that the market has re-priced neither durability nor its absence. It has simply been handed fewer shares. Buybacks financed at these levels are accretive only while the de-rating persists, and 3.4 times leverage sets a limit on how long that can run. If sponsor prices come in where Hunn expects, capital swings back to deals and the compounding resumes on the old terms; if they do not, mid-single-digit organic growth is the entire story, and it is the number management has already called harder than hoped.
Roper reports third-quarter results on 22 October. The line to read first is not earnings per share — the denominator has been doing that work — but the organic growth beneath it.