

Tony Guzzi Said EMCOR Serves 50% to 60% of the US Data-Center Electrical Market
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
EMCOR put a number on its place in the artificial-intelligence buildout for the first time on September 17 — and did it on a day its shares sat a fifth below their 2026 high. Nothing in the order book explains the fall.
June-quarter revenue rose 19.8% to $5.155bn at a record 10.62% operating margin, remaining performance obligations reached $17.14bn, up 43.9%, and management raised full-year earnings guidance to $32.00–33.25 a share. Consensus at $32.95 sits inside that range: the estimate did not move, the multiple did, from roughly 26x forward in mid-August to about 22x now.
The exposure is duration rather than demand. Signed work now converts at 75–76% within twelve months against a historical 85%, pushing value into years a 5% ten-year Treasury yield discounts hard. Quanta fell nearly as far and still carries a 36.9x forward multiple.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
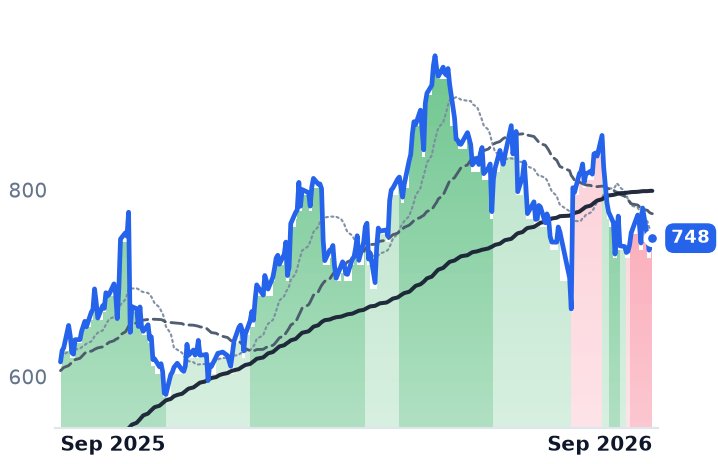
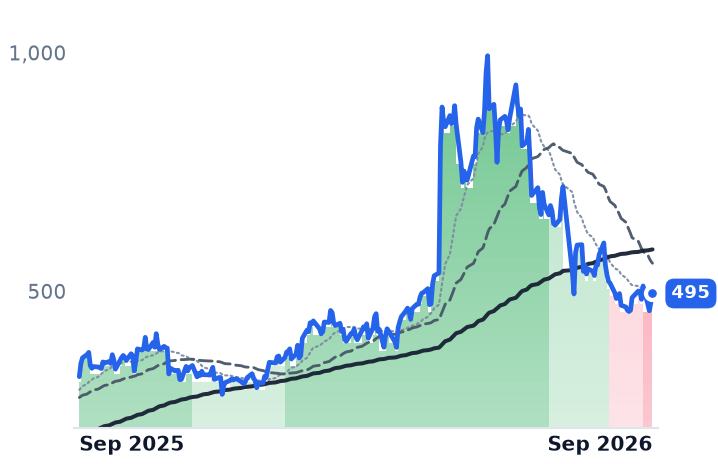
EME | EMCOR | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −9.2% | +21.5% |
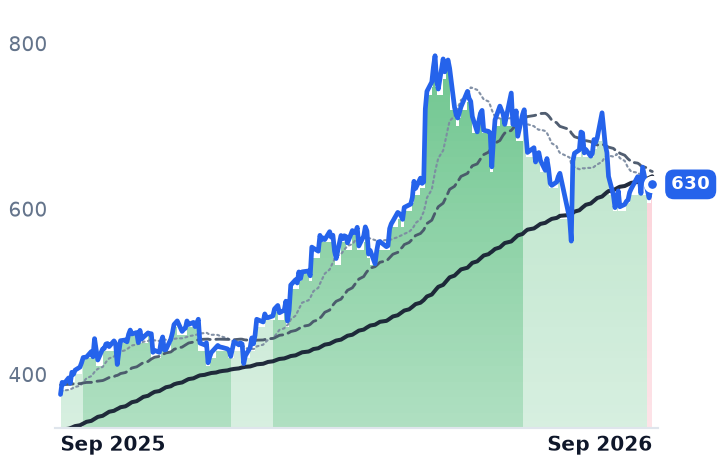
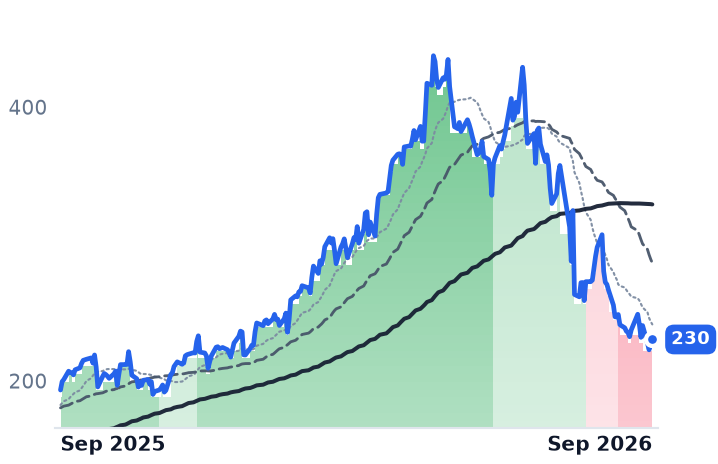
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | −9.5% | +67.6% |
| Compared against · context, not the story | |||||
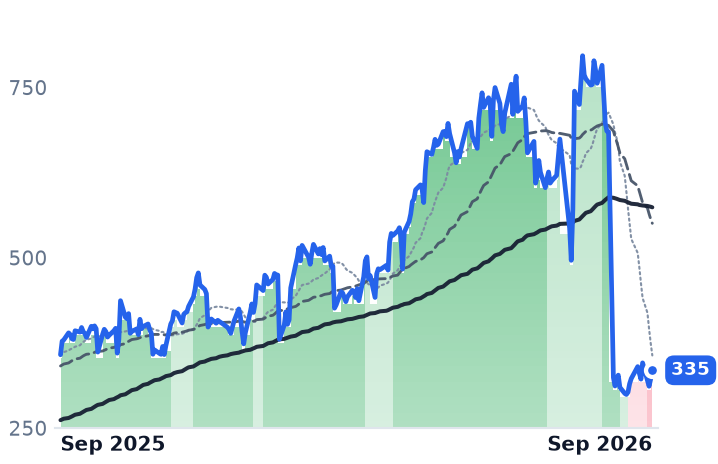
IESC | IES | MEP & Building Systems | 🟢 Cont. Bull | −54.7% | −6.4% |
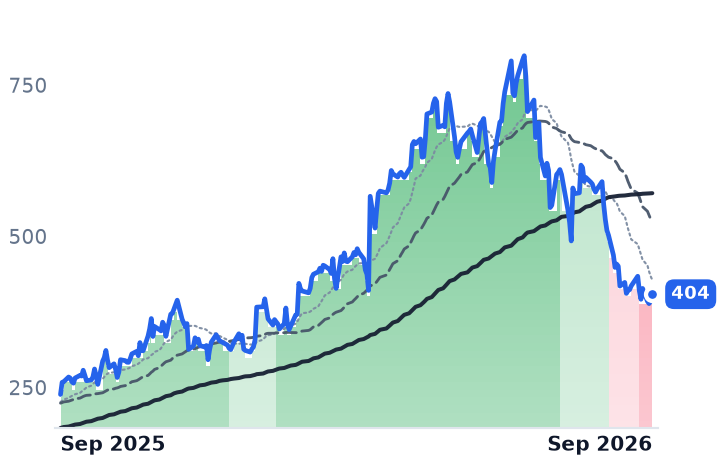
FIX | Comfort Systems USA | MEP & Building Systems | 🟢 Cont. Bull | −6.1% | +114.2% |
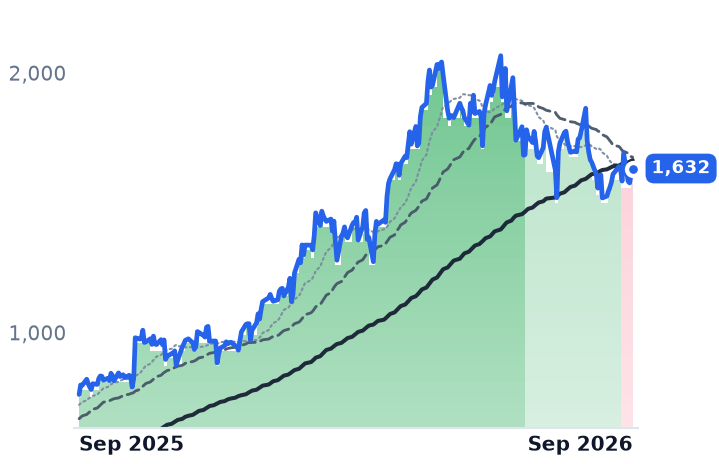
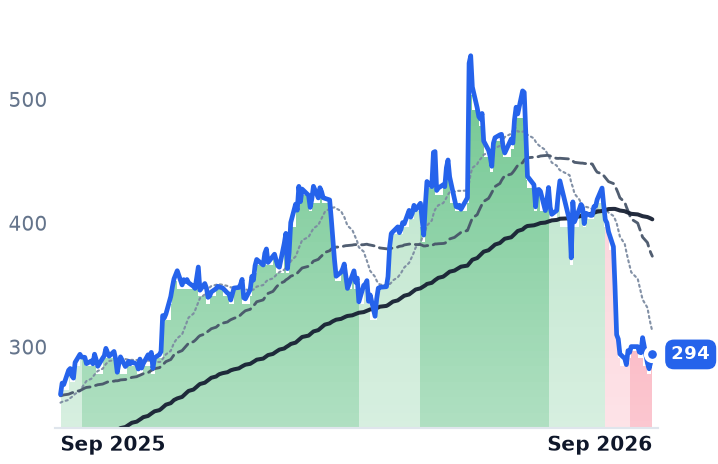
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | ⚠️ Emerging Bear | −10.7% | +54.3% |
MTZ | MasTec | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −17.8% | +19.1% |
DY | Dycom Industries | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −29.1% | +12.4% |
AGX | Argan | Energy & Power Project Solutions | 🟢 Cont. Bull | −26.9% | +69.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EME | $32.2B | 22.8x | 22.1x | 1.7x | 1.6x | 8.8x | 8.0x | 14.2x | 3.6% |
PWR | $92.7B | 69.7x | 36.8x | 2.8x | 2.4x | 19.6x | 16.3x | 32.5x | 2.6% |
IESC | $13.8B | 30.3x | 29.9x | 3.5x | 3.3x | 13.3x | 12.6x | 23.0x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIX | $59.5B | 41.5x | 34.5x | 5.3x | 4.6x | 20.6x | 17.9x | 29.6x | 3.6% |
STRL | $15.3B | 35.6x | 25.2x | 4.5x | 3.8x | 18.9x | 16.0x | 21.1x | 3.1% |
MTZ | $19.7B | 38.7x | 26.3x | 1.2x | 1.1x | 10.7x | 9.5x | 17.2x | 1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DY | $11.8B | 37.0x | 23.7x | 1.9x | 1.5x | 9.6x | 7.9x | 13.4x | 3.7% |
AGX | $7.0B | 43.1x | 41.9x | 6.7x | 5.5x | 32.3x | 26.3x | 35.6x | 6.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EME | Revenue | +21.4% | +10.9% | +8.3% |
| EPS | +30.1% | +13.0% | +13.2% | |
PWR | Revenue | +40.6% | +16.5% | +12.8% |
| EPS | +57.5% | +17.6% | +16.6% | |
IESC | Revenue | +27.7% | +48.1% | +18.8% |
| EPS | +76.1% | +16.3% | +17.1% | |
FIX | Revenue | +47.7% | +19.0% | +14.1% |
| EPS | +86.6% | +22.8% | +23.4% | |
STRL | Revenue | +71.5% | +21.2% | +17.3% |
| EPS | +91.2% | +28.0% | +20.6% | |
MTZ | Revenue | +29.2% | +19.1% | +15.4% |
| EPS | +45.5% | +34.3% | +30.0% | |
DY | Revenue | +17.1% | +40.1% | +11.3% |
| EPS | +39.5% | +47.1% | +20.3% | |
AGX | Revenue | +12.1% | +36.0% | +25.1% |
| EPS | +65.8% | +42.8% | +28.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
EMCOR Group, the Norwalk, Connecticut contractor that designs, installs and maintains the electrical and mechanical systems inside buildings — power distribution, cooling, clean-room ventilation, high-purity piping — told Morgan Stanley's Laguna conference on September 17 that it now serves about 50% to 60% of the electrically relevant data-center markets nationwide and 40% to 50% of the mechanically relevant ones. It is the first time the company has sized its own share of that work, and chief executive Tony Guzzi said it deep into a selloff in the shares.
The share matters because the content per site is rising. A traditional cloud data center runs 20 to 75 megawatts; an artificial-intelligence campus is often 200 megawatts or more across several buildings over three to five years, and at that scale EMCOR told the conference the mechanical scope runs 1.5 to 2 times a cloud project's and the electrical scope 1.25 to 1.5 times, mostly because of cooling. More than half a market, on jobs worth more per megawatt, is the whole investment case — and it is being marked down.
The book grew; the guide went up
June-quarter revenue rose 19.8% to $5.155bn, the fourth straight quarter near 20%, and operating margin reached a record 10.62%. Remaining performance obligations — signed, unbilled work — hit $17.14bn at June 30, up 43.9% and roughly 95% organic, with the largest gains in network and communications on data-center contracts. Against first-half revenue of $9.78bn, that is bookings running about 1.4 times billings. On July 30 the company raised full-year earnings guidance to $32.00–33.25 a share from $29.75–30.75. Consensus for the year sits at $32.95, inside the raised range. Estimates have not been cut.
The shares fell 12.8% in the thirty days to September 17 and sit 20.7% below their 2026 high, still up 21.4% over twelve months. What changed in the past week was the price of money and the mood around the buyer. The 10-year Treasury yield touched 5.014% on September 14, its highest since October 2023, and the buildout complex sold off after Anthropic chief executive Dario Amodei called for a global slowdown in frontier-model development — while Alphabet, Microsoft and Meta, the companies writing the checks, rose.
Where the business is genuinely exposed
Duration. EMCOR's chief financial officer told investors on the July 30 call: "Historically, we would say that 85% or so of our RPOs burn in 12 months. where we're sitting today, it's more like 75% or 76%." A longer book is a more distant cash flow, and a 5% long bond bites hardest there. Mix, too: mechanical construction margin fell 110 basis points to 12.5% as roughly a tenth of that book shifted toward guaranteed-maximum-price forms where equipment passes through at thin markup, even as electrical widened 210 basis points to 13.9%. And the recurring maintenance business is no ballast — US building services grew 5.6% to $837.7m at a 7.6% operating margin, against $3.96bn of construction trades earning 13.1%.
Quanta Services, the Houston utility contractor whose transmission and distribution work is billed largely under multi-year master agreements to regulated utilities, fell 12.1% over the same stretch on revenue up 41.1% to $9.557bn and a record $53.4bn backlog. Its 2025 annual report discloses no customer at 10% or more of revenue, the largest at 8% — so the fear that one hyperscaler's pause empties the book has no anchor in either company's filings.
The verdict
The business earns none of this drawdown and the estimate sheet proves it; what the market repriced is the rate at which a lengthening book of contracted work is discounted, plus its willingness to pay for anything with artificial intelligence attached. EMCOR's forward multiple has gone from roughly 26x in mid-August to about 22x — the same anchor it carried in May, after a year in which signed work grew 44%. On forward gross profit it trades at 8.1x against Comfort Systems' 17.9x, a gap that gross margins of 19.8% versus 25.9% only partly explain. Quanta, at 36.9x forward against EMCOR's 22.1x and Comfort's 34.5x, has come down a third from the roughly 53x it carried in May but remains the expensive one of the three.
Guzzi sized the franchise on the day the shares were the cheapest they had been since spring. The share of the market is not in doubt; what a dollar earned in the fourth year of a five-year campus is worth now is.