

Century Aluminum Guided on a $1.09 Premium That Now Trades at 95 Cents
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
An American smelter's margin is the gap between two numbers it does not set: the London metal price and a Midwest delivery premium that is largely a pass-through of the Section 232 tariff. The metal has held — London Metal Exchange cash aluminum settled at $3,252.90 a tonne on 15 September, near a two-month high — while the premium fell roughly 26% from early July on tariff headlines alone.
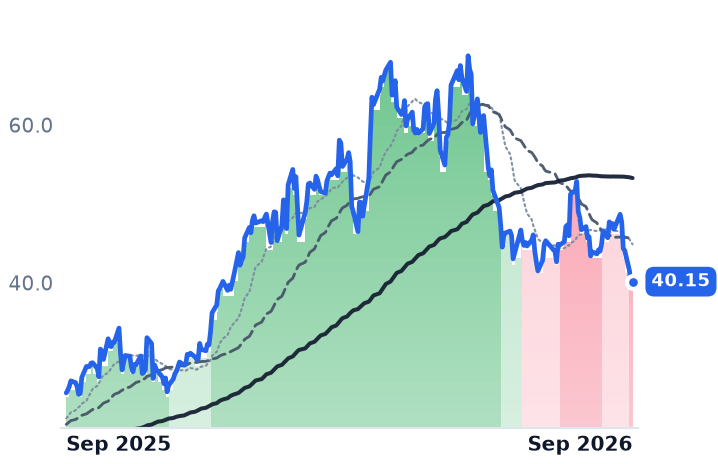
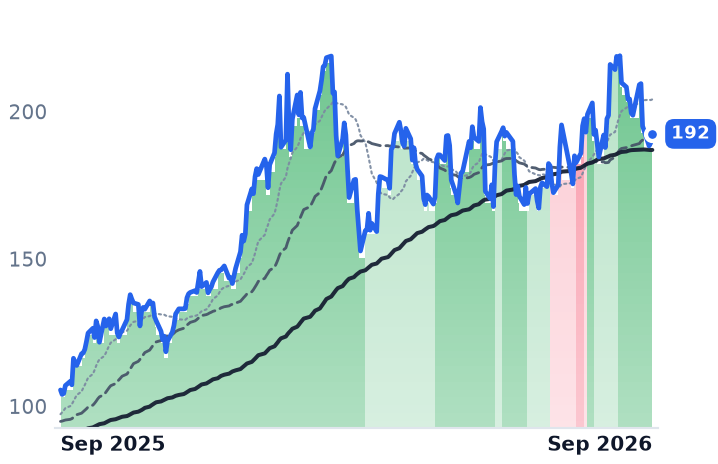
Century Aluminum, the purest listed bet on that premium, sits 41.6% below its June high even though second-quarter gross margin reached 30.3% against 5.8% a year earlier. Kaiser Aluminum, which converts metal on contractual pass-through terms and has no premium leg, lost most of its month in the single session it named a new chief executive. One is being marked for policy; the other for succession.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
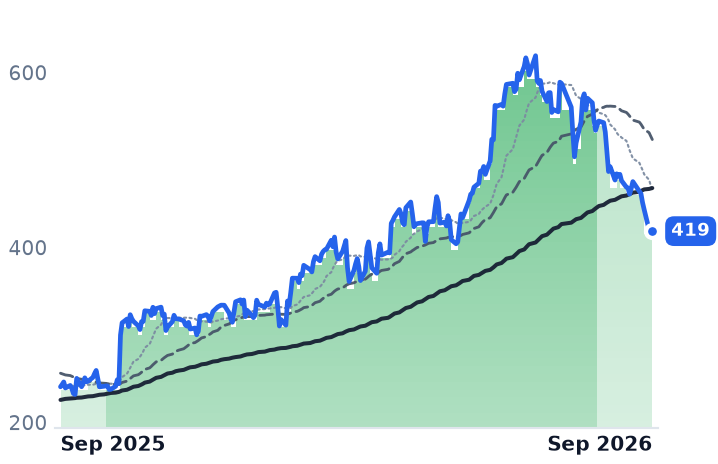
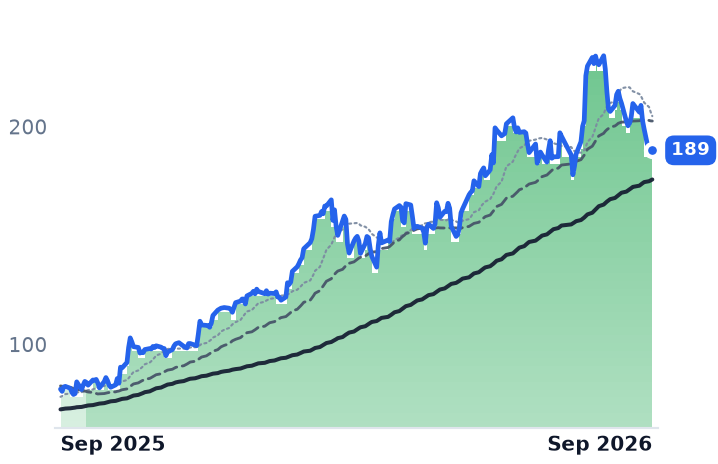
CENX | Century Aluminum | Aluminum | ⚠️ Emerging Bear | −14.8% | +54.1% |
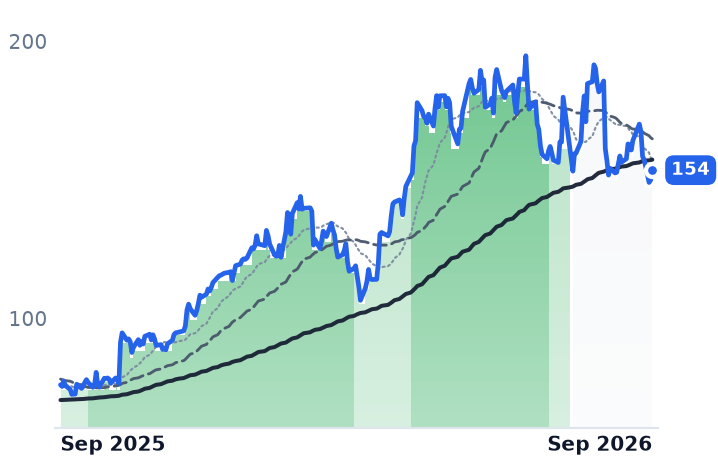
KALU | Kaiser Aluminum | Aluminum | 🟢 Cont. Bull | −17.3% | +101.9% |
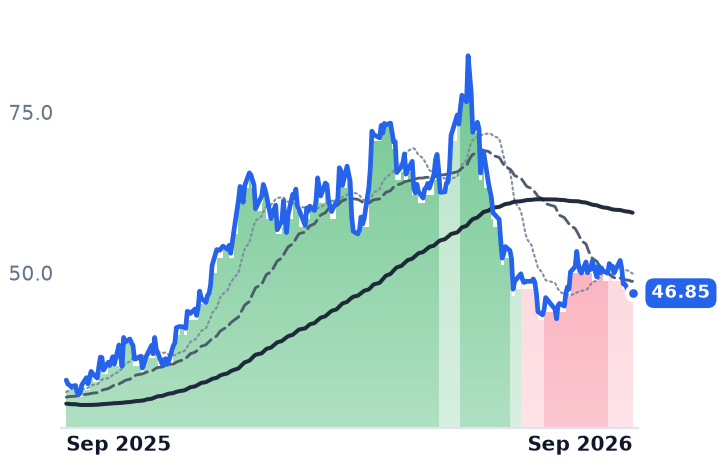
AA | Alcoa | Aluminum | ⚠️ Emerging Bear | −9.4% | +40.6% |
| Compared against · context, not the story | |||||
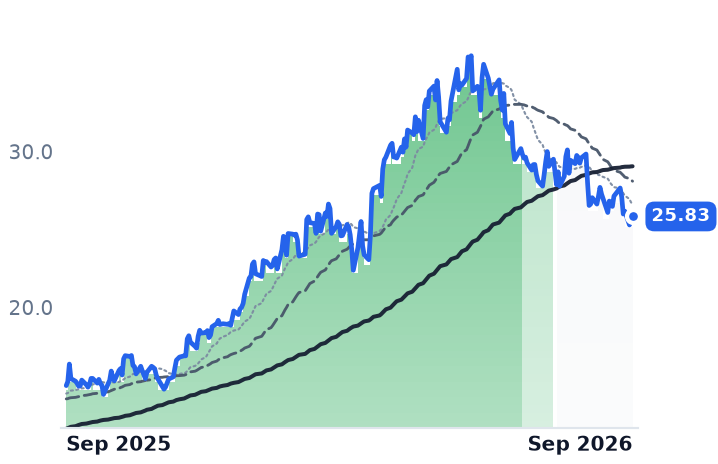
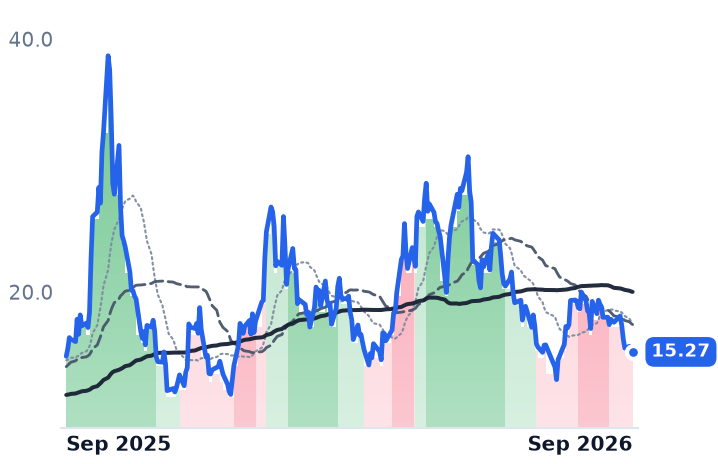
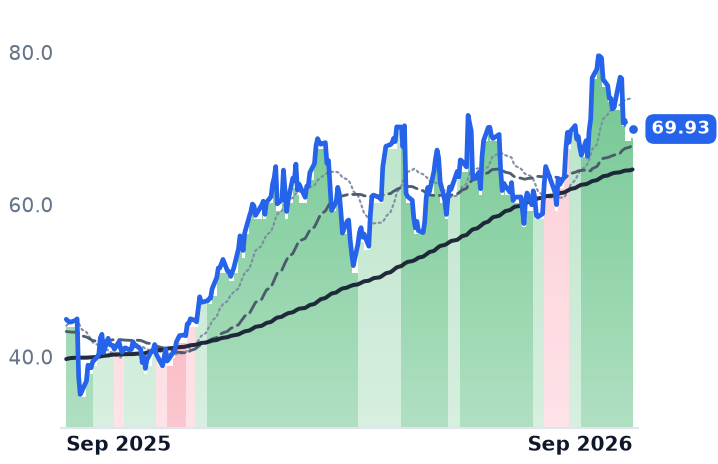
CSTM | Constellium | Aluminum | 🟢 Cont. Bull | −13.4% | +72.5% |
CRS | Carpenter Technology | Specialty Alloys | 🟢 Cont. Bull | −22.9% | +73.9% |
ATI | ATI | Specialty Alloys | 🟢 Cont. Bull | −18.7% | +138.0% |
USAR | USA Rare Earth | Rare Earth & Magnets | ⚠️ Emerging Bear | −20.9% | +2.3% |
FCX | Freeport-McMoRan | Copper | 🟢 Cont. Bull | +2.3% | +55.6% |
SCCO | Southern Copper | Copper | 🟢 Cont. Bull | +0.2% | +82.3% |
RIO | Rio Tinto | Major Diversified Mining | 🟢 Cont. Bull | +0.5% | +58.2% |
VALE | Vale | Major Diversified Mining | ⚠️ Emerging Bear | +4.4% | +38.9% |
TECK | Teck Resources | Major Diversified Mining | 🟢 Cont. Bull | +0.1% | +61.7% |
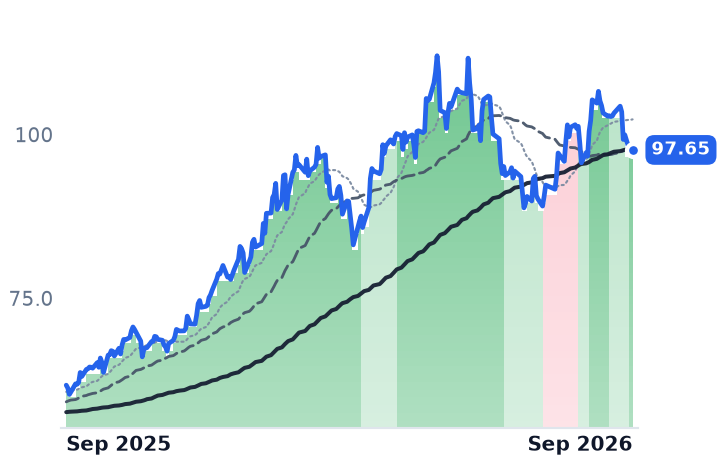
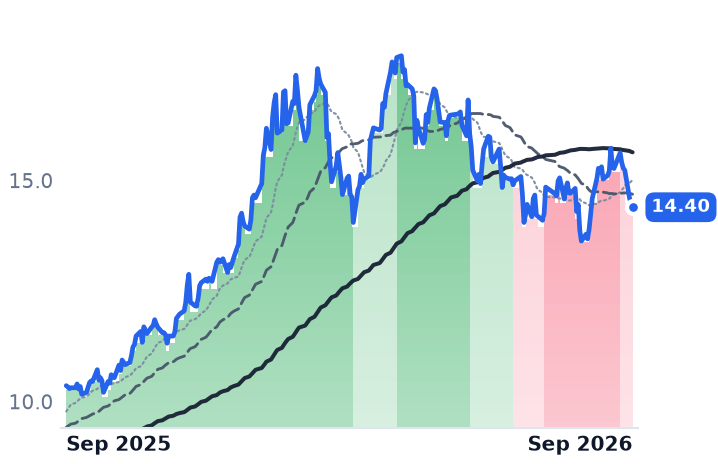
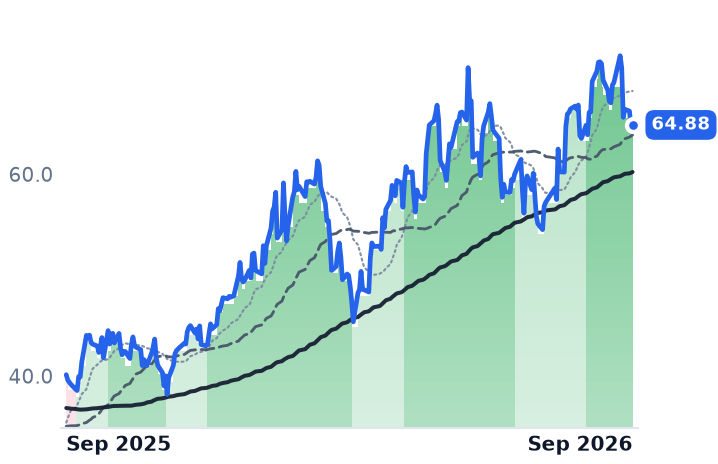
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CENX | $4.0B | 6.6x | 4.0x | 1.5x | 1.2x | 7.7x | 6.1x | 5.8x | 3.8% |
KALU | $2.5B | 10.9x | 10.9x | 0.6x | 0.5x | 5.2x | 4.7x | 7.4x | 3.5% |
AA | $12.4B | 9.5x | 7.1x | 0.9x | 0.8x | 4.8x | 4.4x | 6.6x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CSTM | $3.7B | 6.8x | 7.0x | 0.4x | 0.4x | 2.9x | 2.7x | 5.1x | 6.0% |
CRS | $20.3B | 42.7x | 38.8x | 6.7x | 6.5x | 22.6x | 21.8x | 26.5x | 2.0% |
ATI | $21.0B | 49.3x | 35.3x | 4.6x | 4.2x | 20.3x | 18.7x | 26.6x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
USAR | $2.6B | n/m | — | 194.4x | 32.3x | — | — | n/m | -9.6% |
FCX | $110.2B | 37.8x | 26.1x | 4.3x | 3.8x | 15.9x | 14.0x | 12.9x | 5.4% |
SCCO | $154.0B | 27.0x | 24.1x | 9.8x | 9.2x | 15.7x | 14.7x | 15.8x | 3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RIO | $171.1B | 14.0x | 12.7x | 2.7x | 2.7x | 10.1x | 9.8x | 7.6x | 3.4% |
VALE | $69.6B | 24.3x | 8.1x | 1.8x | 1.7x | 5.2x | 4.9x | 6.2x | 4.8% |
TECK | $33.4B | 18.6x | 11.3x | 3.3x | 2.2x | 9.4x | 6.2x | 7.7x | 3.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CENX | Revenue | +32.9% | +21.6% | −1.8% |
| EPS | +361.4% | +11.9% | +50.4% | |
KALU | Revenue | +37.3% | −3.8% | −6.3% |
| EPS | +129.3% | −17.0% | +16.6% | |
AA | Revenue | +17.1% | +1.9% | −5.9% |
| EPS | +85.0% | −7.5% | +5.8% | |
CSTM | Revenue | +24.3% | +0.6% | −1.3% |
| EPS | +160.8% | −31.2% | +4.3% | |
CRS | Revenue | +7.0% | +10.3% | +10.7% |
| EPS | +44.9% | +19.1% | +17.6% | |
ATI | Revenue | +8.4% | +9.3% | +6.7% |
| EPS | +37.3% | +22.1% | +15.7% | |
USAR | Revenue | +980.4% | +592.8% | +163.6% |
| EPS | −75.2% | −59.4% | −249.2% | |
FCX | Revenue | +15.3% | +20.6% | +3.0% |
| EPS | +89.3% | +36.2% | +11.1% | |
SCCO | Revenue | +27.7% | −4.3% | +2.7% |
| EPS | +47.9% | −6.3% | −2.0% | |
RIO | Revenue | +12.4% | +2.1% | +1.5% |
| EPS | +24.8% | −0.3% | −2.0% | |
VALE | Revenue | +8.3% | −0.4% | +2.6% |
| EPS | +0.3% | −4.0% | +0.4% | |
TECK | Revenue | +45.6% | +0.1% | −15.4% |
| EPS | +130.8% | −14.6% | −25.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
An Alcoa executive spent part of 10 September explaining to investors the exact circumstances under which American smelters would stop making money without the price of aluminum falling at all. Molly Beerman, the company's chief financial officer, said that if Washington extends tariff relief beyond Canada to partners such as Japan, South Korea or Europe and the last million tonnes of imports is covered, "then you can expect the Midwest premium to reduce in response to essentially wipe out the tariff benefit." Century Aluminum, the listed company whose profit most nearly is that benefit, fell 15.8% over the five sessions to 16 September, more than twice Alcoa's decline.
The stake is a printed number due in weeks. Century guided third-quarter adjusted earnings before interest, tax, depreciation and amortization to $325–345m on an assumed US Midwest premium of $1.09 a pound. On 20 August the September contract slumped 8.2% to 95 cents after reports that Washington would halve the 50% tariff on Canadian metal. Those talks collapsed and the 50% rate stayed, but the premium never went back: duty-paid metal fetched more than $2,850 a tonne in early July and roughly $2,094 by late August. The metal itself did not move with it.
Where the dollar comes from
Century runs primary aluminum smelters in the United States and Iceland and owns a carbon-anode plant in the Netherlands. It realizes the London price plus the regional premium and pays for alumina, delivered power and anodes — three inputs set elsewhere. When both revenue numbers rose together in the June quarter, everything followed: revenue of $752.1m, up 19.7% year on year, gross margin of 30.3% against 5.8% a year earlier, and adjusted EBITDA of $327m on shipments of 130,632 tonnes. Price alone added $95m sequentially.
"Today, both plants are producing at full capacity into a market that needs every unit we can produce," chief executive Jesse Gary told investors on the 6 August call, after the Mt. Holly expansion completed in June and Grundartangi's second line restarted six months early. The cost stack is guided to worsen into the September quarter — $10–15m of summer energy, $5m of raw materials and $20–25m of hedge settlements against a $15–25m volume and mix tailwind. The offset is alumina, the biggest single input, which Beerman expects to stay oversupplied into 2027.
Century changed hands at 6.6x trailing and 4.0x forward earnings, against 140x in early May when the shares were priced for the tariff to hold forever. Alcoa — which produces around 900,000 tonnes a year in Canada and is paying more than $1bn in Section 232 duties to bring most of it south, the mirror of Century's position — trades at 9.5x trailing and 7.1x forward. Consensus still has Century earning $10.07 a share this year against 42 cents last, rising again in 2027.
Kaiser's month was one day
Kaiser Aluminum rolls, extrudes and draws mill products for aerospace, packaging and automotive customers, buying metal on contractual pass-through terms and getting paid per pound of conversion. It has no direct claim on the premium, and its drawdown is not about one. Second-quarter sales were a record $1.26bn, up 53%, net income more than quadrupled, and packaging conversion revenue rose 34% to $174m. Of its 17.3% loss over the month, 13.2% came on 18 August, the session it named Amcor's Fred Stephan to succeed Keith Harvey as chief executive from 1 November. Strip that day and the shares are down 4.8%. At 10.9x both trailing and forward earnings the market pays nothing for this year's step-up, and consensus puts 2027 earnings 17% lower.
Nor is aluminum alone in the selling: Carpenter Technology fell 22.9% and ATI 18.7% over the same 30 days while copper producers were flat to higher, and the dollar firmed as traders priced a Federal Reserve rate rise into 3.4% inflation.
The verdict
Part of Century's fall is honestly earned — the thing it sells did get cheaper, and a quarter budgeted on $1.09 a pound will not print $1.09. What nothing yet explains is the remainder: four consecutive quarters of widening gross margin, cash that exceeded total debt for the first time in July, and a forward multiple of four while the estimate under it still rises. The caveat that belongs beside that multiple is that the earnings are a spread between two administered numbers, and four times a policy decision is not four times an ordinary earnings stream. Kaiser's case is unrelated: record conversion economics, modelled as a peak, plus a leadership handover.
Century's own hedge against premium risk is more policy. A 20 July executive order lets companies investing in US primary capacity import approved volumes at 25% rather than 50%, and Century expects clearance for 300,000 tonnes a year from 2027 tied to its Oklahoma project — "quite material" to cash flow, Gary called it. The insurance against one signature is another signature.