

Only $50m of Clearway's Up-to-$1bn Equity Plan Has Been Raised; Project Deals Are Paused
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Clearway Energy's operating business is doing what it promised and its financing plan is not. The vehicle needs outside equity to fund a $3bn capital program through 2029, and at today's share price it will not sell it — so growth now runs on retained cash and debt, and third-party project purchases are on hold until the stock recovers.
The June quarter was strong: revenue of $481m, up 22.7%, with operating income up 36.5%, and all three ERCOT wind contracts restructured past 2040 on terms accretive from the first month. The damage is at the discount rate, not the asset. XPLR Infrastructure, the former NextEra Energy Partners, shows the endpoint: it pays no distribution at all, and its units barely moved while Clearway fell.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
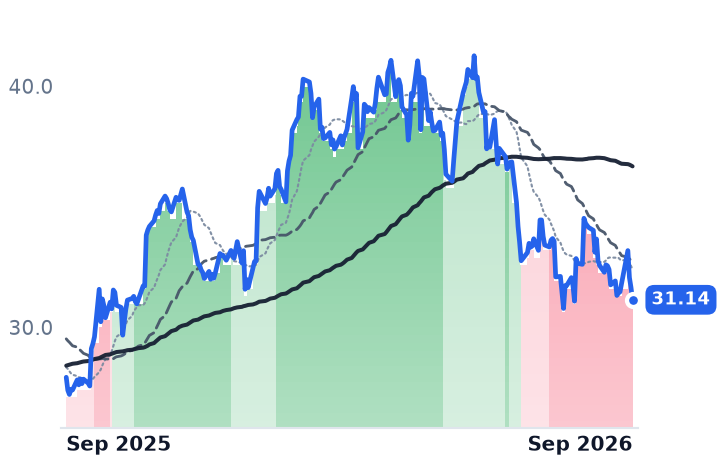
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −8.5% | +11.5% |
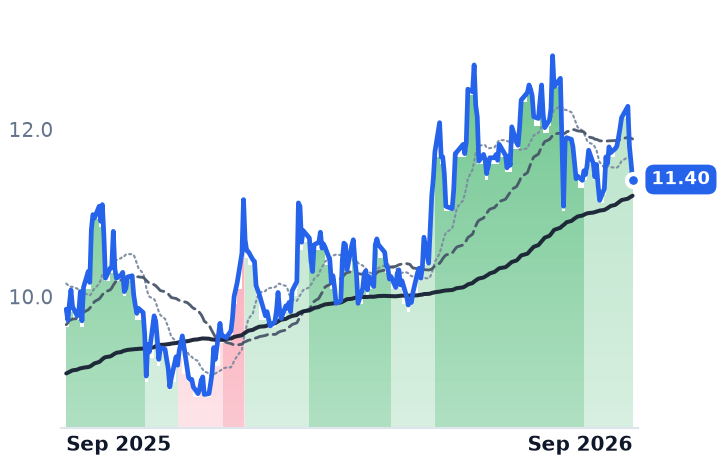
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | −1.6% | +15.7% |
| Compared against · context, not the story | |||||
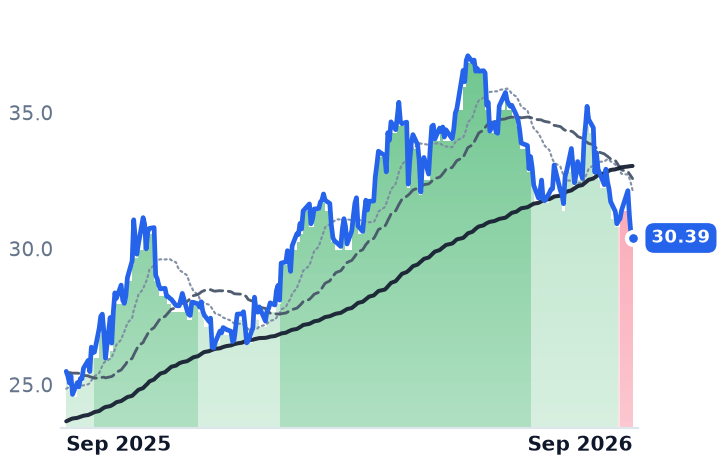
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −11.8% | +19.2% |
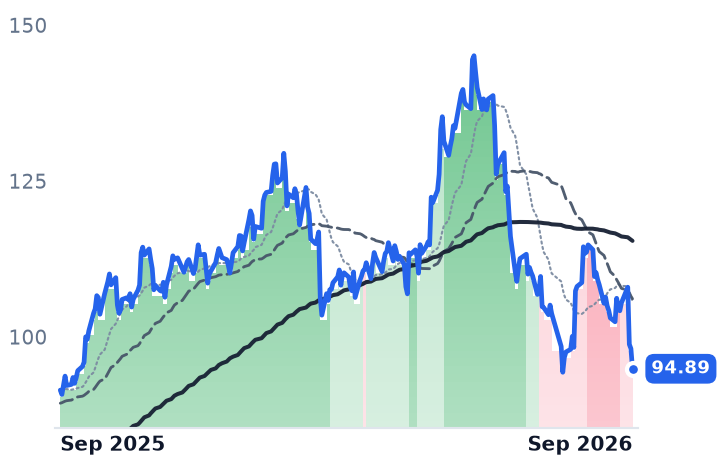
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | −16.7% | +3.7% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.2% | +16.7% |
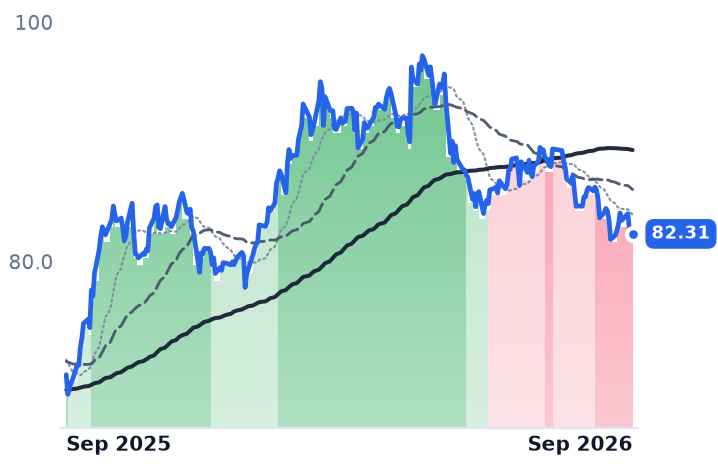
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWEN | $6.4B | 41.0x | — | 4.1x | 3.9x | 7.7x | 7.3x | 14.4x | 10.5% |
XIFR | $1.1B | 17.0x | 10.0x | 0.9x | 0.8x | 5.2x | 4.6x | 8.9x | -59.0% |
BEP | $9.3B | 66.1x | — | 1.5x | 1.4x | 6.0x | 5.7x | 9.7x | -50.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORA | $5.8B | 45.6x | 37.3x | 4.9x | 4.9x | 17.6x | 17.7x | 20.1x | -4.5% |
NEE | $172.8B | 18.5x | 20.6x | 6.0x | 5.6x | 8.3x | 7.8x | 15.8x | -5.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CWEN | Revenue | +14.5% | +11.5% | +12.2% |
| EPS | −116.0% | −318.9% | +60.4% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% | |
BEP | Revenue | +3.8% | +9.0% | −3.4% |
| EPS | +14.0% | −11.7% | +9.4% | |
ORA | Revenue | +21.4% | −1.7% | +11.1% |
| EPS | +16.4% | −4.1% | +28.2% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Clearway Energy has promised $3bn of corporate capital between 2026 and 2029, and the cheapest piece of that plan is the piece it will not sell. The company is a holding vehicle for roughly 5,000 net megawatts of American wind and solar plus about 2,500 net megawatts of natural gas generation, spun out of NRG in 2018 and staffed by 60 people. Its plan called for $500m to $1bn of new equity. It has raised $50m.
That matters beyond one funding decision, because equity is the marginal money in a yieldco. The remainder of the plan — more than $500m of retained cash flow and more than $1.5bn of corporate debt, $600m of it already raised this year — is largely committed. The share price sets the price of everything else: the drop-downs bought from sponsor Clearway Group, the third-party projects, and ultimately the cash available for distribution per share that governs the dividend. Management has deprioritized third-party project acquisitions until the stock recovers.
The spread that vanished
What repriced was the alternative. The 30-year Treasury closed 11 September at 5.36%, its highest since 2007, against the 5.27% reading of a week earlier; the Treasury had already doubled its long-end liquidity-support buybacks to at least $4bn per operation effective 9 September, and yields rose anyway. Clearway's quarterly dividend, raised to $0.4602 in February and to $0.4676 in May, annualizes to $1.87 — about 6.0% at $31.14, or roughly two-thirds of a percentage point over the long bond. A contracted annuity that clears the risk-free rate by that little is not an expensive thing to replace.
Meanwhile Clearway's debt is cheap: $600m of senior notes priced at 5.750% in January, against a leverage target of 4.0-4.5x and a BB rating. Its repowering program is deploying roughly $600m at cash-available-for-distribution yields of 11% to 12%. Borrowing at under 6% to earn 11% is obvious arithmetic; issuing shares at 0.69x book to do the same is not.
The business kept working
June-quarter revenue was $481m, up 22.7%, with operating income up 36.5% to $116m — growth accelerating from 18.8% in the March quarter. All three ERCOT wind projects, more than 600 megawatts, were restructured onto contracts running past 2040 and accretive to cash from the first month, at a time when North American wind power purchase agreements cleared at a record $79.40 per megawatt-hour. The one genuine deterioration was weather: 2026 CAFD guidance cut about 8% at the midpoint, to $430m-$470m, on poor first-half wind.
"While we are lowering our 2026 financial guidance due to factors outlined in our mid-July operational preview, our team is focused on maintaining our trademark operational excellence to uphold our historic track record of meeting our financial targets," chief executive Craig Cornelius told investors on 5 August. The 2027 target of $2.70 or better per share was reaffirmed; the shares sit at 11.5 times it.
The shares themselves have fallen 9.3% in thirty days and 17.4% in three months, with the 50-day average under the 200-day since 20 July. The decline was not Clearway's own: Brookfield Renewable fell 12.0% and Ormat 16.3% over the same month. The only discoverable company news was an 8 September leadership change, with Steven Ryder becoming chief financial officer while keeping the same job at the sponsor — a dual hat at a vehicle whose central governance question is what it pays that sponsor for assets.
The mirror: a yieldco with no yield
XPLR Infrastructure, the former NextEra Energy Partners, barely moved: down 0.5% over the same thirty days, because it has no distribution to be repriced against a 5.36% bond. It suspended one and redirected the cash into buying out convertible equity portfolio financings — outside investors who can otherwise claim the underlying projects. In the June quarter it completed the first minimum buyout of one such financing for about $150m and repaid $500m of converts. Roughly $2.5bn of buyouts remain, falling due at annual intervals from 2028 through 2034, with about $470m planned for 2027 and an intention to sell the assets inside one financing next year. Revenue grew 6.1% to $363m; operating income fell a third to $60m as margin dropped from 26.3% to 16.5%. It trades at 0.33x book and 10.0x forward earnings against 17.0x trailing.
What the move earns
The guidance cut explains a slice of Clearway's decline and the rest is the discount rate — which is a real loss, not a misunderstanding, since a vehicle valued as a spread over Treasuries has less spread. But the operating evidence points the other way: recontracting is repricing upward, not down, and the 2027 cash target is fundable out of retained cash and debt alone. The exposed part of the plan is the back end, the 2030 range and the 2 gigawatts of late-stage solar-plus-storage behind it, which needs an equity market Clearway currently declines to use. XPLR is what that looks like taken to its conclusion: the same contracted megawatt-hours, routed to financiers for the rest of the decade, with growth arriving through sponsor joint ventures because issuing units is no longer an option.
Clearway will roll its five-year growth target forward into 2031 on the third-quarter call, alongside a roadmap to a payout ratio below 70%. It will be setting that target in a market where its own shares are the most expensive money it can raise.