

Antero's Liquids Barrel Sold at $44.33 as Henry Hub Fell 16%, and Net Income Rose 78%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two Appalachian producers sit on adjacent rock and are paid by different markets. Antero Resources sells roughly a third of its volumes as natural gas liquids priced off Mont Belvieu and the export docks, and in the second quarter that stream realized $44.33 a barrel before hedges — about six dollars better than a year earlier — while the gas benchmark fell 16%.
The result was revenue up 11.1% and net income up 78% to $279m at Antero, against a 29.2% revenue decline and an operating margin of 25.1% from 44.3% at EQT, the largest US gas producer. Consensus follows the split: Antero's forward earnings multiple of 9.03x sits below its trailing 10.95x, EQT's 13.27x sits above its 11.88x.
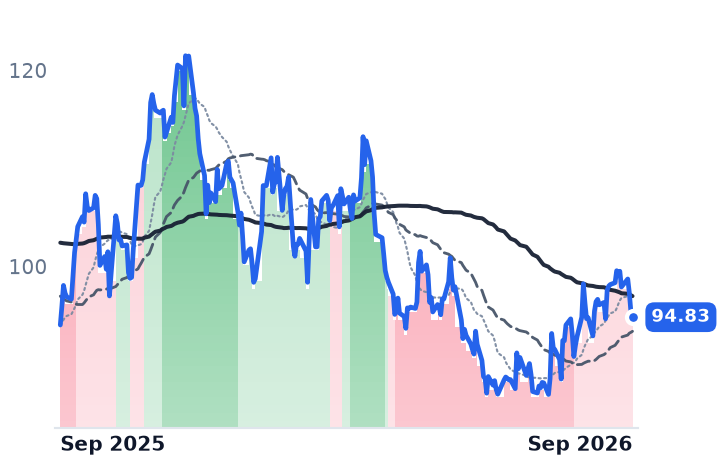
The business earns Antero's three-month recovery. What it does not yet explain is a flat twelve months against a 57% gain in adjusted earnings before interest, taxes, depreciation and exploration expense — and the liquids barrel carrying the story is the one Antero deliberately leaves unhedged.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AR | Antero Resources | Appalachian Shale Gas | ⚠️ Emerging Bear | +2.8% | +18.4% |
EQT | EQT | Appalachian Shale Gas | ⚠️ Emerging Bear | −0.6% | +8.8% |
| Compared against · context, not the story | |||||
RRC | Range Resources | Appalachian Shale Gas | ⚠️ Emerging Bear | +2.1% | +17.8% |
CNX | CNX Resources | Appalachian Shale Gas | ⚠️ Emerging Bear | +0.5% | +19.4% |
EXE | Expand Energy | Appalachian Shale Gas | 🔴 Cont. Bear | +0.1% | +0.8% |
GPOR | Gulfport Energy | Appalachian Shale Gas | ⚠️ Emerging Bear | +1.9% | +0.6% |
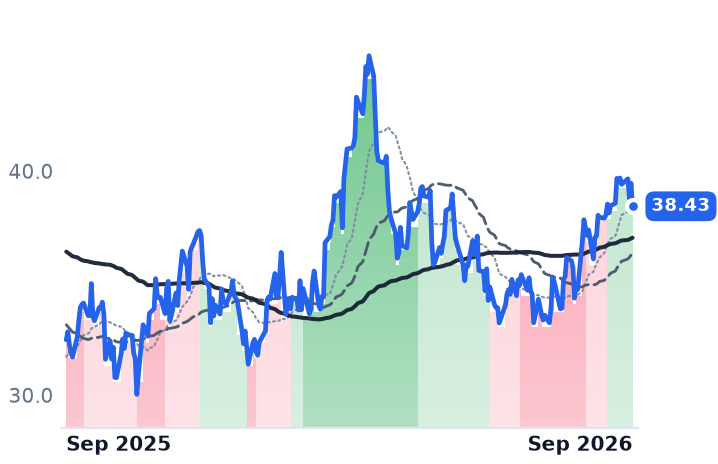
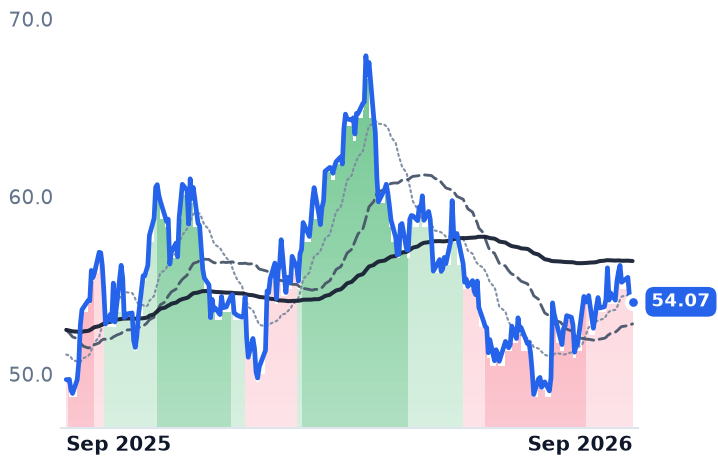
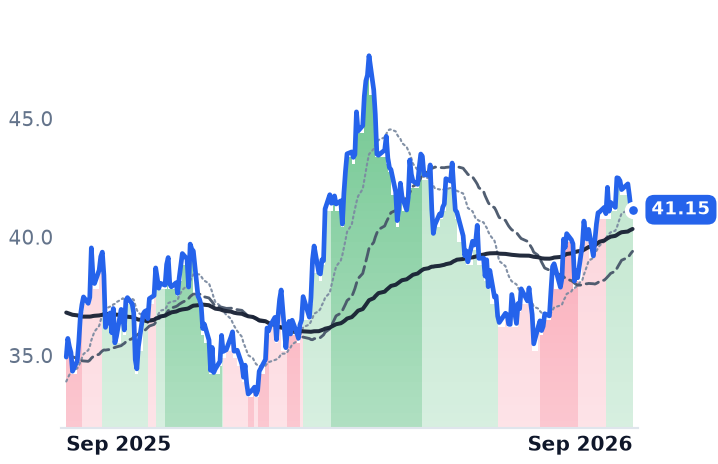
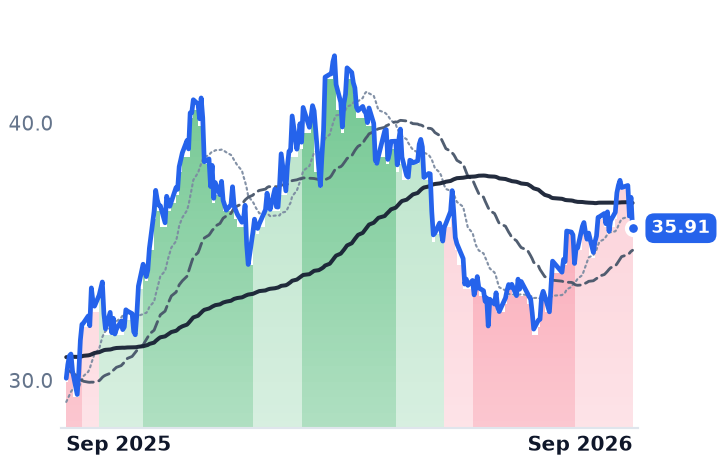
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AR | $11.8B | 10.9x | 9.0x | 2.1x | 1.8x | 8.1x | 6.8x | 6.9x | 11.9% |
EQT | $33.8B | 11.9x | 13.3x | 3.6x | 3.6x | 5.3x | 5.3x | 6.4x | 11.1% |
RRC | $9.8B | 11.5x | 10.3x | 3.0x | 2.8x | 6.2x | 5.8x | 7.6x | 12.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNX | $5.3B | 5.2x | 11.5x | 2.2x | 2.2x | 4.5x | 4.5x | 4.1x | 9.9% |
EXE | $22.7B | 8.4x | 10.9x | 1.7x | 1.7x | 2.7x | 2.7x | 3.9x | 11.2% |
GPOR | $3.1B | 6.9x | 7.4x | 2.1x | 2.0x | 3.5x | 3.4x | 4.3x | 8.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AR | Revenue | +31.0% | −0.2% | +8.5% |
| EPS | +134.9% | +2.7% | +27.8% | |
EQT | Revenue | +11.4% | −1.0% | +11.1% |
| EPS | +38.4% | −5.3% | +37.4% | |
RRC | Revenue | +17.7% | +2.5% | +8.1% |
| EPS | +40.2% | −4.7% | +21.6% | |
CNX | Revenue | +16.2% | −8.8% | +7.1% |
| EPS | +42.9% | +31.7% | +23.1% | |
EXE | Revenue | +15.4% | −4.0% | +6.1% |
| EPS | +50.0% | −5.1% | +22.8% | |
GPOR | Revenue | +10.7% | +1.2% | +5.4% |
| EPS | +8.7% | +18.6% | +31.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Antero Resources sells about a third of what it produces as liquids, and in the second quarter that decision did all the work. The Denver-based Appalachian driller — 502,000 net acres, 17.7 trillion cubic feet equivalent of proved reserves — realized $44.33 a barrel on its propane-and-heavier stream before hedges, its best since 2022 and roughly six dollars above a year earlier. The gas benchmark over the same stretch fell 16%.
That gap is the whole story of why one basin label covers two businesses. An Appalachian producer's revenue is not the Henry Hub print; it is the benchmark plus or minus where its pipe goes. Antero guides its 2026 gas to a premium of $0.05 to $0.15 per thousand cubic feet to NYMEX, the payoff on firm transportation held off the basin for years. EQT, vertically integrated since it absorbed Equitrans, realized a $(0.67) differential per thousand cubic feet in the second quarter, a figure that already nets its firm-transport position. Then Antero adds a second price deck entirely: 216,000 barrels a day of liquids inside 4.1 billion cubic feet equivalent of daily output, sold against Mont Belvieu and the waterborne export market.
The barrel is an export barrel
Antero, which calls itself the country's second-largest liquids producer and largest producer-exporter, told investors on its July 30 call that US propane exports ran 2.03m barrels a day in the quarter, up 170,000 year on year, with China's share of the global liquefied petroleum gas market back to 51% from 10% in June 2025. It raised guidance for its ethane premium to Mont Belvieu to $2.00–$3.00 a barrel. It carries no liquids hedges at all. The counterweight is that Mont Belvieu itself has stayed soft on high domestic inventories even as export volumes set records.
The income statement follows the barrel. Second-quarter revenue rose 11.1% to $1.34bn and net income rose 78% to $279m, with diluted earnings of $0.90 a share against $0.50. Production set a record at 4.1 billion cubic feet equivalent a day, up 21%. Management also laid out a $300m annual margin programme running to 2028 — a dissolved royalty entity worth $60m a year from the third quarter, an expiring volumetric production payment worth $30m, and transport renegotiations for the rest — against $0.35 per thousand cubic feet equivalent of lower realizations as it shifts sales in-basin.
The dry-gas side of the same rock
EQT's quarter ran the other way: revenue down 29.2% to $1.81bn, operating margin to 25.1% from 44.3%, diluted earnings to $0.44 from $1.30. Its answer is demand, not liquids. It has a signed ten-year agreement to supply 325m cubic feet a day to a Competitive Power Ventures plant in West Virginia, worth about $100m of free cash flow and five cents of corporate differential if it runs a full year from 2027; the far larger 4.4-gigawatt Homer City campus was announced as an agreement in principle. "These are big plans that are being put out in this area, so we're really excited about how Appalachia is positioned to be the home for a lot of these projects," chief executive Toby Rice said on the second-quarter call, citing a pipeline of negotiations. Range Resources, the closest comparison because it too has a liquids book, grew revenue 19.1% to $834m with operating margin at 39.1% against 26.8%.
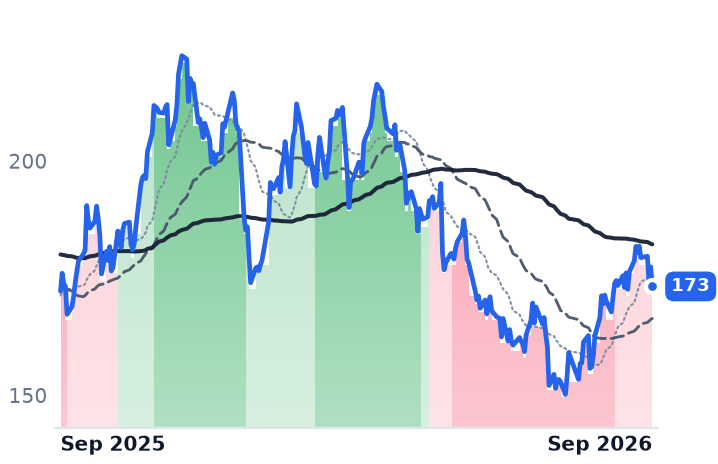
The shares have split along the same seam. All six Appalachian pure-plays fell together over six months — EQT down 15.3%, Antero down 3.1% — and all six have risen over three, Antero most at 12.3%. Over twelve months the liquids-weighted names lead: Antero and Range both up 17%, EQT up 6.1%, Expand and Gulfport flat to slightly lower. Antero trades at 10.95x trailing earnings and 9.03x forward, the market modeling roughly 21% growth, on a trailing free-cash-flow yield of 11.9%. EQT's forward multiple of 13.27x sits above its trailing 11.88x — consensus models 2027 earnings per share of $3.86, down 5.3%. Range sits between them at 11.51x trailing against 10.31x forward.
What the business earns
The three-month recovery in Antero's shares is paid for: accelerating revenue, expanding margins, a barrel priced off an export market rather than a congested basin. The twelve-month flat line against a 57% rise in adjusted earnings before interest, taxes, depreciation and exploration is the part nothing yet explains, and the likeliest reading is that the market has already looked past 2026 — consensus has revenue plateauing at $6.70bn next year with earnings up 2.7%. EQT's de-rating is not a mispricing either; it is a market marking earnings down while the company argues that in-basin power demand will re-rate them later.
What the split removes is the hedge in owning the basin as a theme. Antero's advantage this year came from the one product it refuses to hedge, sold to buyers on the other side of an ocean; its next print is the first test of whether a Chinese propane bid survives the winter that Appalachian gas is counting on.