

Starbucks Grew Transactions 4.5% and Dutch Bros 3.4% While Their Shares Fell Together
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two coffee chains reported quarters that argued against their own share prices, for opposite reasons. Starbucks lifted North America segment operating margin to 13.6% from 13.3% while adding back barista hours — store operating expenses held at 51.2% of segment revenue — and raised fiscal 2026 guidance. Dutch Bros grew revenue 32.5% to $550.9m and raised its outlook, then guided third-quarter system comparable sales down to 4-5% as shop contribution margin slipped to 30.6%.
The thirty-day fall belongs to the restaurant group: McDonald's, Cava and Texas Roadhouse all dropped as hard or harder. What splits the two is what got repriced. Starbucks is still on 37.8x forward earnings against McDonald's 19.6x, with consensus earnings this year below fiscal 2024's — a recovery being paid for in advance, less of it now. Dutch Bros' forward multiple has compressed by roughly a third since June while estimates rose.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
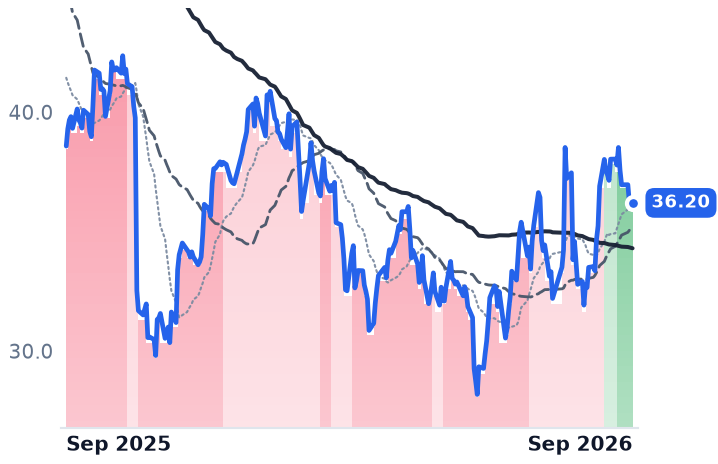
SBUX | Starbucks | Coffee & Beverages | 🟢 Cont. Bull | −8.3% | +21.1% |
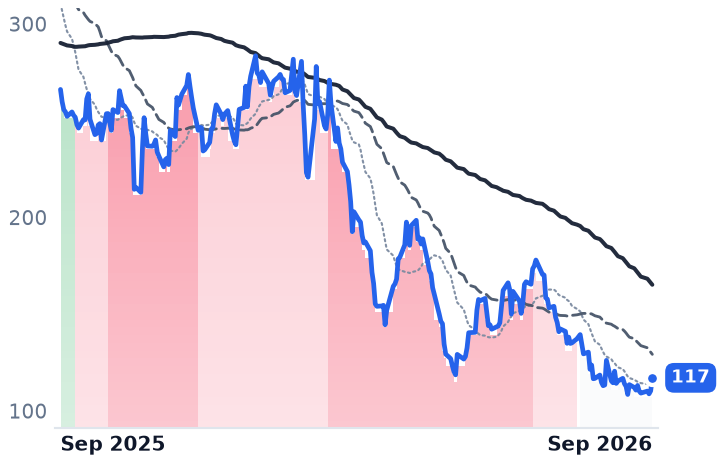
BROS | Dutch Bros | Coffee & Beverages | 🌱 Emerging Bull | −15.6% | −29.3% |
| Compared against · context, not the story | |||||
MCD | McDonald's | Quick Service - Burgers & Sandwiches | ⚠️ Emerging Bear | −7.4% | −15.4% |
CAVA | CAVA | Quick Service - Mexican & Bowls | 🔴 Cont. Bear | −24.9% | −10.6% |
CMG | Chipotle Mexican Grill | Quick Service - Mexican & Bowls | 🌱 Emerging Bull | +8.1% | −6.2% |
WING | Wingstop | Quick Service - Chicken & Wings | 🔴 Cont. Bear | −7.2% | −56.0% |
TXRH | Texas Roadhouse | Casual Dining - Steakhouse & Seafood | 🌱 Emerging Bull | −12.5% | +10.7% |
EAT | Brinker International | Casual Dining - Full Service | 🌱 Emerging Bull | −10.4% | +39.0% |
SHAK | Shake Shack | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −15.0% | −37.1% |
YUM | Yum! Brands | Quick Service - Pizza | 🟢 Cont. Bull | −4.9% | −4.5% |
DRI | Darden Restaurants | Casual Dining - Full Service | 🟢 Cont. Bull | −6.8% | +1.2% |
WEN | The Wendy's | Quick Service - Burgers & Sandwiches | 🌱 Emerging Bull | −11.7% | −18.3% |
QSR | Restaurant Brands International | Quick Service - Pizza | 🟢 Cont. Bull | −0.9% | +23.8% |
BJRI | BJ's Restaurants | Casual Dining - Full Service | 🟢 Cont. Bull | −10.6% | +95.6% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.6% | +16.6% |
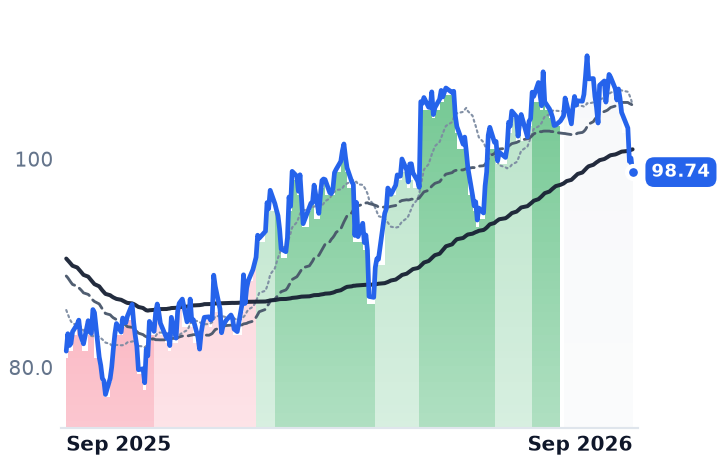
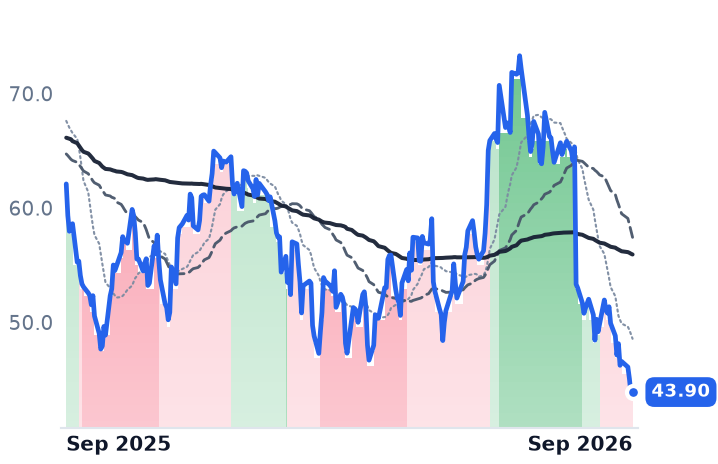
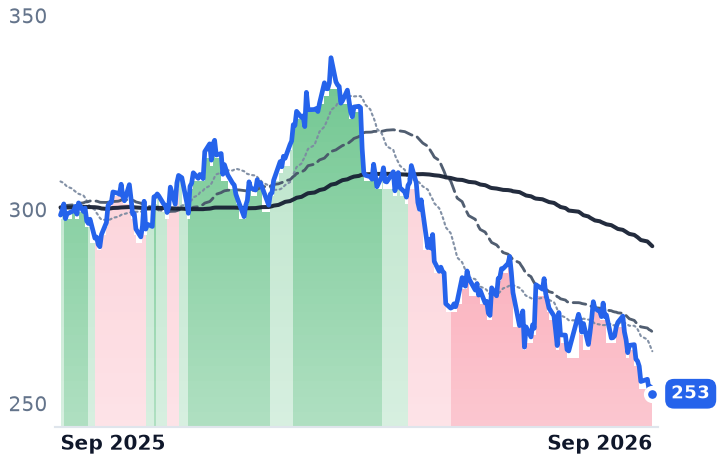
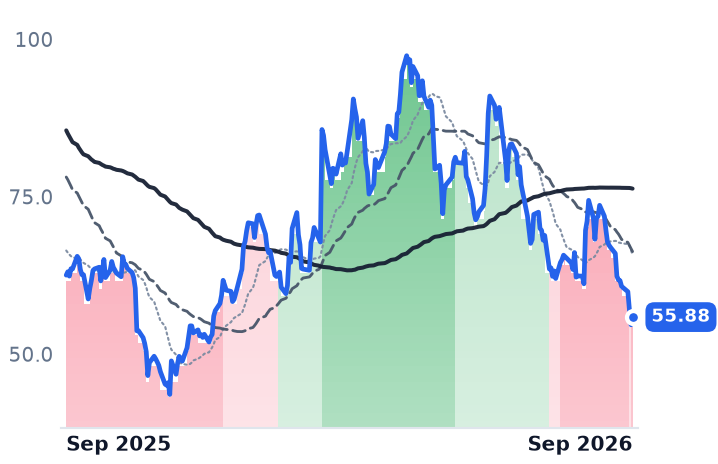
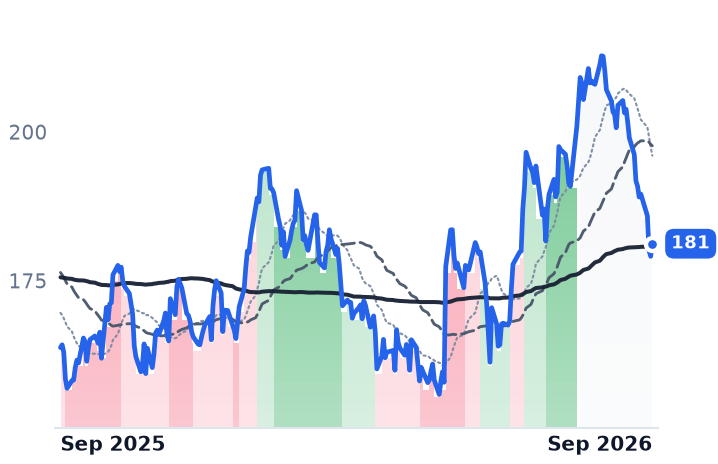
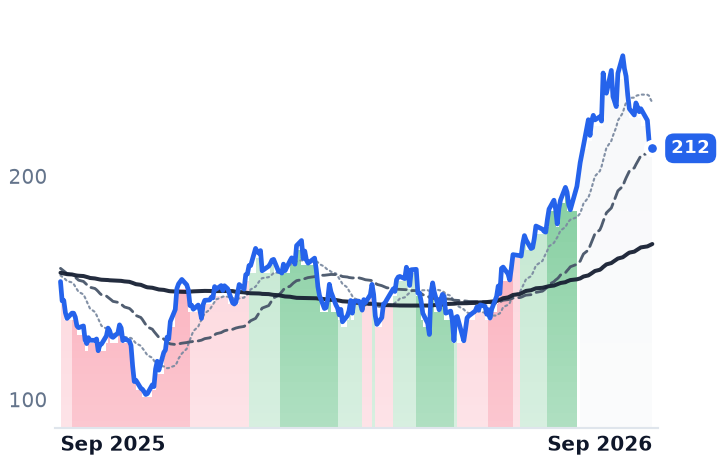
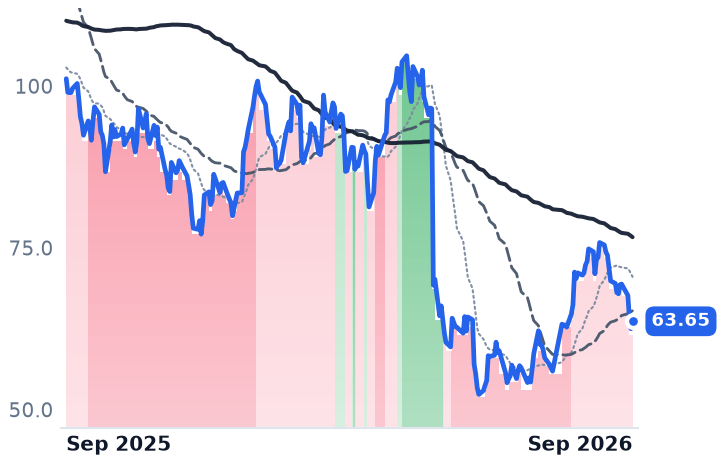
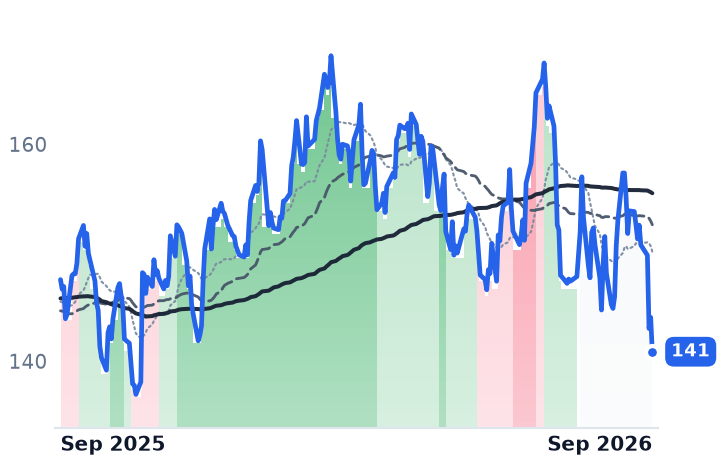
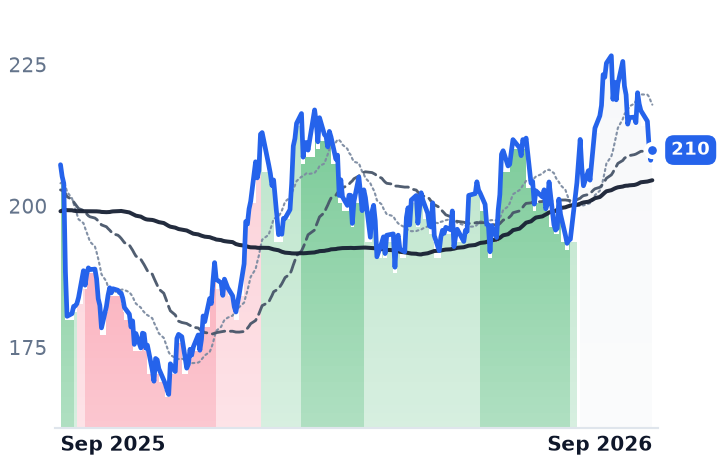
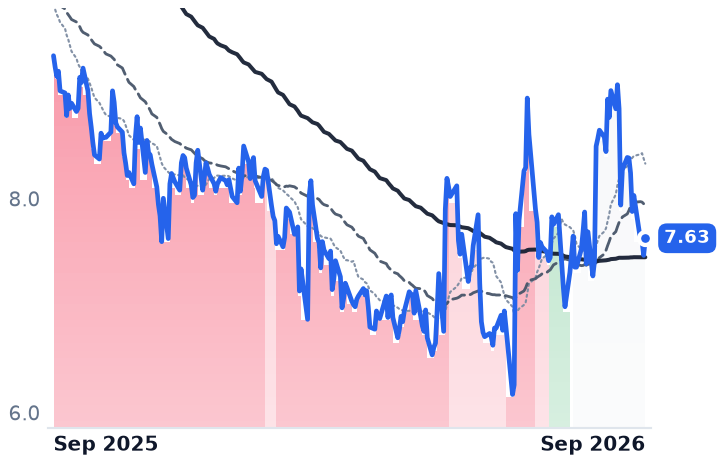
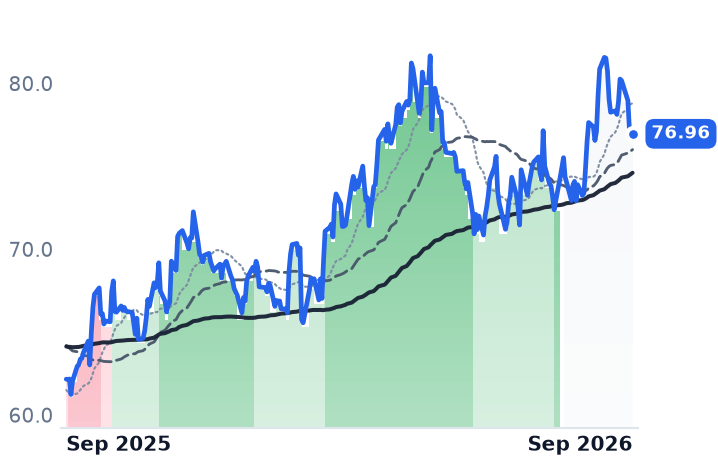
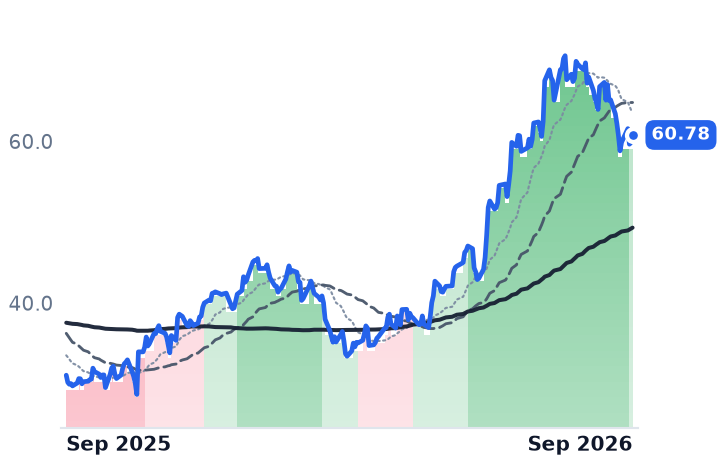
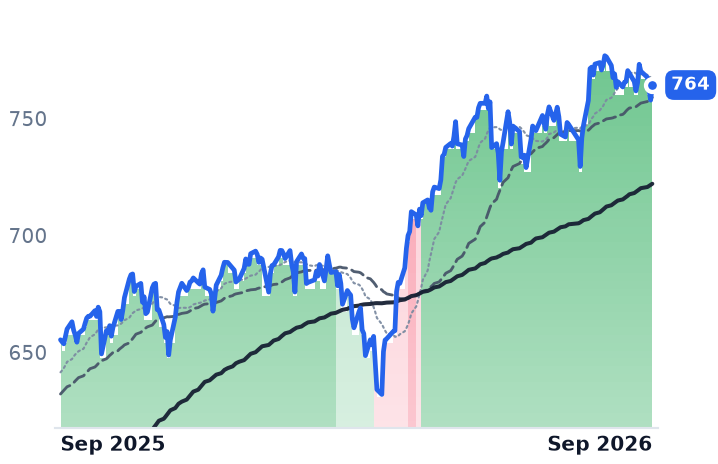
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SBUX | $112.6B | 56.7x | 37.8x | 2.9x | 3.0x | 9.3x | 9.3x | 22.4x | 3.2% |
BROS | $7.6B | 61.0x | 45.9x | 4.0x | 3.6x | 16.1x | 14.2x | 28.7x | 1.3% |
MCD | $179.4B | 20.5x | 19.6x | 6.5x | 6.4x | 11.3x | 11.1x | 15.5x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAVA | $6.5B | 97.6x | 102.4x | 4.7x | 4.3x | 23.5x | 21.5x | 39.5x | 0.8% |
CMG | $41.9B | 29.2x | 28.7x | 3.5x | 3.2x | 9.5x | 8.9x | 20.5x | 3.6% |
WING | $3.5B | 31.7x | 28.3x | 5.0x | 4.5x | 6.0x | 5.5x | 15.4x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXRH | $11.9B | 28.9x | 27.4x | 1.9x | 1.8x | 12.5x | 11.9x | 16.7x | 3.4% |
EAT | $10.2B | 21.2x | 18.9x | 1.8x | 1.7x | 9.4x | 8.9x | 14.0x | 5.5% |
SHAK | $2.4B | 59.1x | 49.0x | 1.6x | 1.5x | 8.5x | 7.6x | 16.8x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
YUM | $42.0B | 19.0x | 23.1x | 4.8x | 4.7x | 10.5x | 10.2x | 18.6x | 4.0% |
DRI | $25.8B | 21.5x | 20.0x | 2.0x | 1.9x | 2.8x | 2.7x | 13.5x | 4.3% |
WEN | $1.5B | 8.9x | 13.9x | 0.7x | 0.7x | 2.6x | 2.6x | 10.3x | 14.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QSR | $26.3B | 27.6x | 18.7x | 2.7x | 2.7x | 6.1x | 6.0x | 15.9x | 5.8% |
BJRI | $1.4B | 34.8x | 28.7x | 1.0x | 1.0x | 6.4x | 6.3x | 14.6x | 3.1% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SBUX | Revenue | +2.8% | +1.7% | +5.0% |
| EPS | +21.4% | +20.8% | +18.9% | |
BROS | Revenue | +31.8% | +24.6% | +21.4% |
| EPS | +38.8% | +32.0% | +26.0% | |
MCD | Revenue | +5.7% | +5.0% | +4.3% |
| EPS | +6.4% | +7.9% | +7.0% | |
CAVA | Revenue | +28.3% | +20.8% | +20.5% |
| EPS | +3.5% | +36.2% | +38.8% | |
CMG | Revenue | +9.0% | +11.0% | +10.9% |
| EPS | −1.6% | +19.6% | +18.0% | |
WING | Revenue | +11.6% | +15.4% | +14.1% |
| EPS | +17.0% | +22.2% | +24.3% | |
TXRH | Revenue | +11.0% | +9.3% | +8.6% |
| EPS | +4.7% | +18.3% | +20.8% | |
EAT | Revenue | +8.1% | +6.0% | +4.2% |
| EPS | +21.2% | +16.7% | +10.0% | |
SHAK | Revenue | +14.8% | +15.1% | +13.2% |
| EPS | −4.4% | +29.2% | +26.6% | |
YUM | Revenue | +10.0% | +3.7% | +5.7% |
| EPS | +8.5% | +10.2% | +10.8% | |
DRI | Revenue | +9.5% | +3.6% | +6.0% |
| EPS | +11.5% | +6.2% | +9.9% | |
WEN | Revenue | +1.5% | +0.5% | +4.2% |
| EPS | −33.9% | +11.8% | +12.3% | |
QSR | Revenue | +5.2% | +1.7% | −0.4% |
| EPS | +10.4% | +9.4% | +6.5% | |
BJRI | Revenue | +4.1% | +4.0% | +6.2% |
| EPS | +6.6% | +15.4% | +20.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Starbucks spent the past year deliberately adding back scheduled labor hours, and its stores got more profitable while it did. North America segment operating margin reached 13.6% in the quarter ended June 28, against 13.3% a year earlier, on comparable store sales up 8.1% led by a 4.5% increase in transactions rather than price. Store operating expenses rose to $3,789.3m from $3,552.4m in dollars, but held at 51.2% of segment revenue against 51.3%: the comp absorbed the reinvestment.
That arithmetic matters because Starbucks is not a franchisor. Company-operated stores produced $6,754.8m of the segment's $7.4bn of revenue, so every hour added to a schedule lands on Starbucks' own books rather than a licensee's — the reason McDonald's, whose franchisees carry the crew cost, ran a 46.5% operating margin last quarter. The turnaround Brian Niccol is running is therefore a margin question, funded alongside a $1bn restructuring announced in September 2025 that closed 400 to 500 North American stores. "Our third quarter results are proof they do," Niccol said of the plan's premises in the July 29 release. Guidance went up with it: fourth-quarter US comps of 6.5% or better, full-year non-GAAP earnings of $2.55 to $2.65 a share. The labor line is not settled — Starbucks Workers United has proposed a $17 starting wage against a company floor of $15.25 to $16.00 in 43 states.
The other machine
Dutch Bros, which runs drive-thru-only beverage shops under the Dutch Bros and Rebel brands from Grants Pass, Oregon, earns its growth by opening buildings. Revenue rose 32.5% to $550.9m in the June quarter, company-operated same-shop sales rose 8.3% on 3.4% more transactions, and it opened 48 shops, 44 of them company-operated, against a target of more than 150 for the year at roughly $1.4m of capital each. New units are not fading: chief executive Christine Barone told investors on the second-quarter call that the Melrose Park shop near Chicago was pacing to about $7m of volume, a company opening record. Shop contribution margin still fell to 30.6% from 31.1%, because cost of goods rose eight-tenths of a point to 26.1% of company-operated revenue on coffee contracted earlier and a new food program now in about 750 shops.
The number that broke the stock was the shape of the comp. "System same shop sales growth is now estimated to be in the range of 5% to 6%, with us trending towards the midpoint of that range," chief financial officer Joshua Guenser said on that call, guiding third-quarter system comps to 4-5% against 5.8% delivered. Shares fell 18.4% the next session — on a call that raised the revenue outlook to $2.1bn-$2.13bn.
What the group did
The last month was not about either company. Between August 12 and September 11, McDonald's fell 8.5%, Cava 19.8%, Texas Roadhouse 14.8%, Brinker 13.7% and Shake Shack 12.0%, while the S&P 500 tracking fund lost 1.1% and Chipotle rose 10.5%. Starbucks' 8.5% and Dutch Bros' 14.3% declines sit inside that. No Starbucks disclosure in the window explains it; the most prominent September item was an interview in which Niccol said the turnaround is working, so the likelier reading is rotation out of restaurant valuations.
And the valuations were where the two diverge. Starbucks trades at 37.8x forward earnings and 56.7x trailing, against 19.6x forward for McDonald's. Consensus has it earning $2.61 a share this fiscal year — below the $3.31 it actually earned in fiscal 2024, before annual operating margin fell to 9.6% from 15.0% — which puts the shares near 30x their own pre-turnaround earnings power, with consensus revenue growth of only 2.8%. Dutch Bros is at 45.9x forward, down from roughly 68x against its mid-June price, and 34.8x next year's consensus; Cava, the nearest fast-growing comparable, sits at 102x forward on expected earnings growth of 3.5%.
So the two falls mean different things. Starbucks' is the compression of a recovery multiple rather than a verdict on the recovery: four straight quarters of comp growth and two of margin expansion say the plan is converting, but the market had been paying in advance for earnings the company last posted two years ago and is paying less for them now. Dutch Bros' is a repricing of growth's shape — unit count doing the work while comps step down to 4-5% and forward-bought coffee keeps shop margin under the 30% Guenser has called the target — even as estimates rose through the decline. Cheaper than June is not cheap: 34.8x next year still needs the openings to keep landing at the volumes management describes.
The bean, for once, is cooperating. Arabica has fallen back near $3 a pound from last year's record and the extra US tariff on Brazilian green coffee came off last November — but chains buy forward, and better Brazilian supply takes months to reach the cup. Both companies are pouring last year's coffee price into a market that has already stopped charging it.