

Appian's $2bn Verdict Was Vacated and Federal Agencies Now Pay a Quarter of Its Revenue
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Appian spent four years carrying a $2bn trade-secret judgment against Pegasystems as the largest single asset it did not yet own. It no longer has one: Virginia's Supreme Court affirmed in January that the verdict be thrown out and a new trial ordered, and no trial date has been set.
What is left is the operating business, and it is sending two signals at once. Cash improved sharply — adjusted earnings before interest, taxes, depreciation and amortization of $16.2m against $5m-8m guided — while the demand meters softened: revenue growth slowed to 19.1%, gross margin fell just over three points to 71.2%, and the contracted book grew 13%. The shares were rerated regardless, to 4.14x forward gross profit from 3.07x in early May. Procore, filed under the same software heading, got cheaper on the same measure while advancing.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Low-Code & Process Automation | 🌱 Emerging Bull | −1.8% | +12.9% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | ⚠️ Emerging Bear | −10.9% | −25.0% |
| Compared against · context, not the story | |||||
NCNO | nCino | Financial Services Software | 🌱 Emerging Bull | +2.1% | −29.8% |
FRSH | Freshworks | Security & Compliance | 🌱 Emerging Bull | −6.1% | −5.3% |
BL | BlackLine | Financial Services Software | 🔴 Cont. Bear | −7.1% | −47.8% |
PEGA | Pegasystems | Low-Code & Process Automation | ⚠️ Emerging Bear | +12.1% | −38.7% |
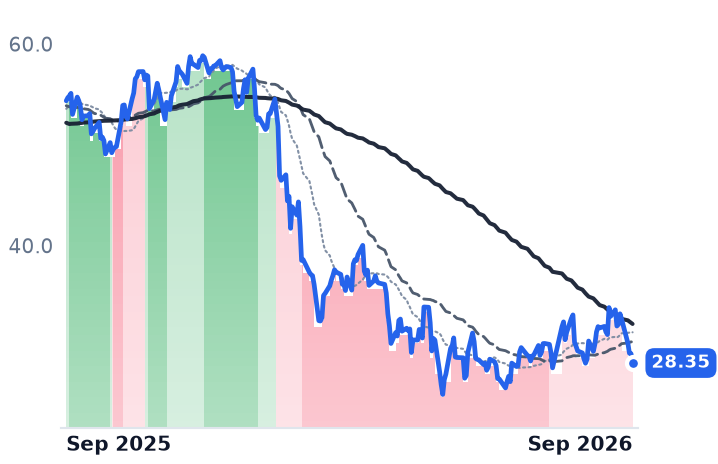
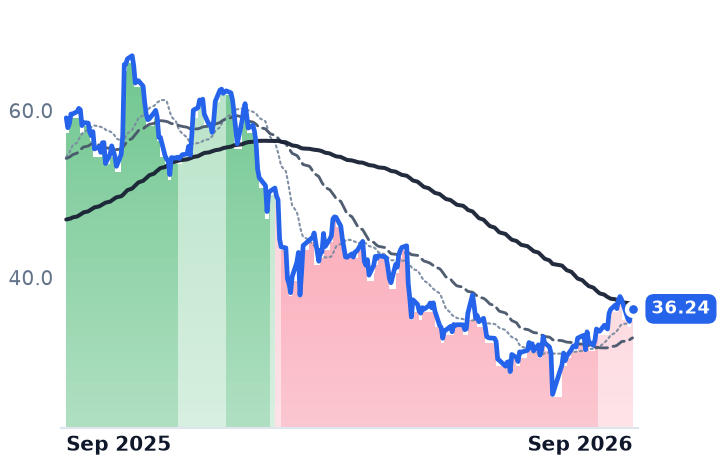
12-month price & trend
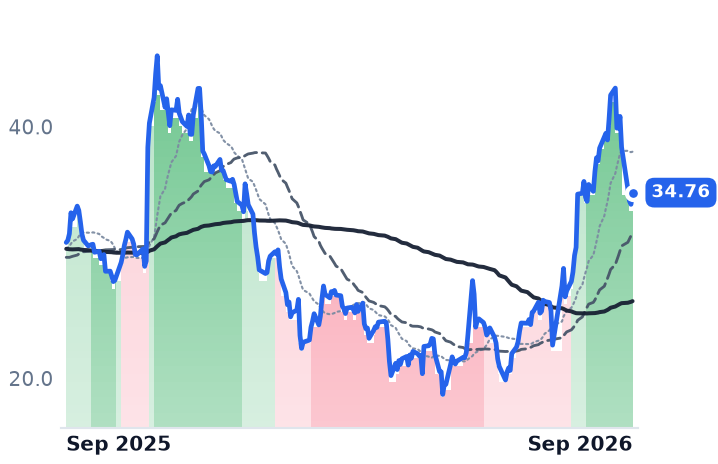
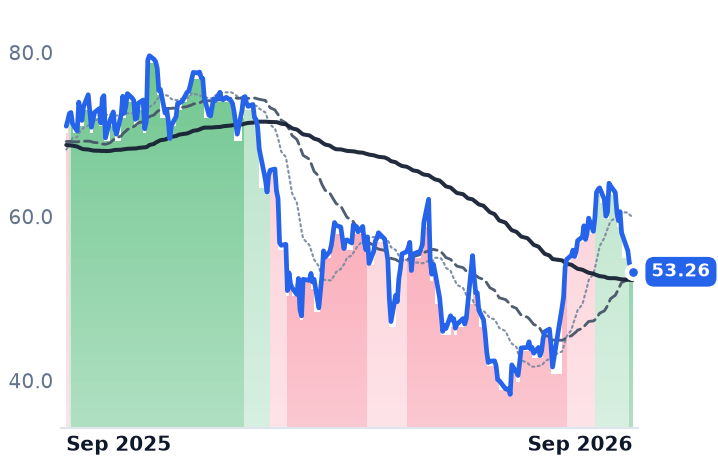
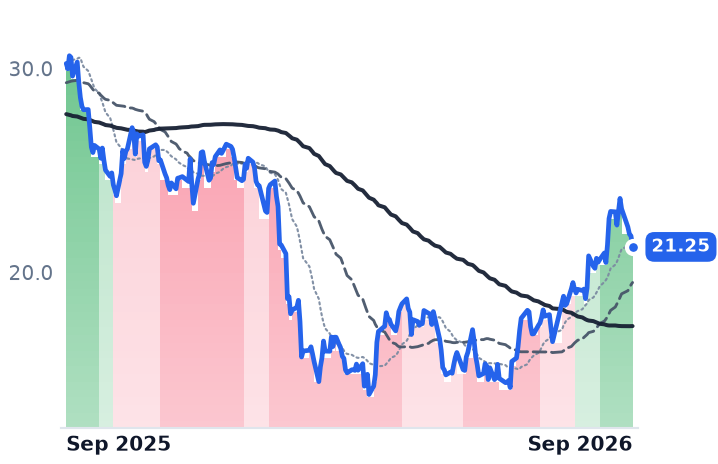
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $2.6B | n/m | 32.1x | 3.2x | 3.0x | 4.4x | 4.1x | 111.7x | 3.0% |
PCOR | $8.0B | n/m | 31.7x | 5.6x | 5.3x | 7.1x | 6.7x | 125.8x | 3.7% |
NCNO | $2.3B | 67.3x | 15.9x | 3.7x | 3.5x | 6.0x | 5.7x | 30.8x | 5.8% |
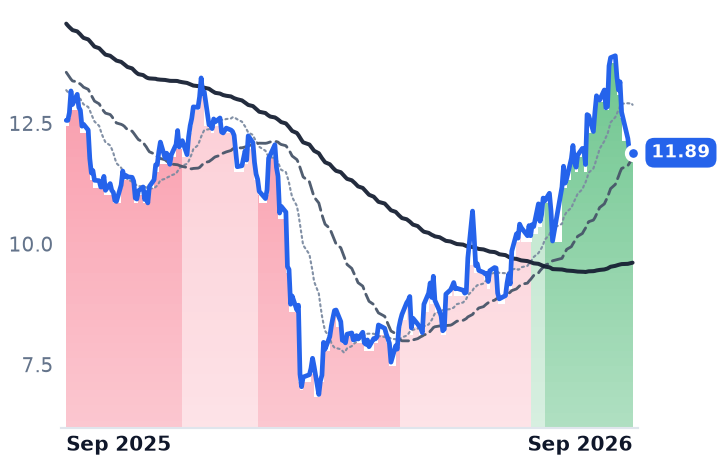
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FRSH | $3.3B | 18.1x | 17.7x | 3.6x | 3.4x | 4.3x | 4.0x | 36.2x | 7.6% |
BL | $1.7B | 48.7x | 11.5x | 2.3x | 2.2x | 3.0x | 2.9x | 21.2x | 10.1% |
PEGA | $6.1B | 19.7x | 15.2x | 3.5x | 3.3x | 4.7x | 4.3x | 30.6x | 8.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
PCOR | Revenue | +15.2% | +13.8% | +14.3% |
| EPS | +24.2% | +46.1% | +20.1% | |
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
FRSH | Revenue | +15.6% | +14.2% | +15.6% |
| EPS | +5.4% | +24.5% | +19.0% | |
BL | Revenue | +9.5% | +10.5% | +10.2% |
| EPS | +19.4% | +11.9% | +17.3% | |
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The largest number in Appian's story is one a court took back. On 8 January the Supreme Court of Virginia unanimously affirmed that the $2bn trade-secret verdict Appian won against Pegasystems be thrown out and a new trial ordered, faulting a jury instruction that shifted the burden of proof on damages onto the defendant. The case returns to Fairfax County Circuit Court before a new judge, for a retrial of both liability and damages. No trial date has been identified.
That matters beyond the docket because Appian, the McLean, Virginia maker of low-code software that builds workflows, forms and data models without hand-coding, is a $2.57bn company still losing money on a reported basis. A contingent recovery larger than its own market value was doing quiet work in the equity story. With it gone, the shares rest on the operating business — and that business has been sending two signals at once while the stock rose 47% in three months.
Three revenue lines, pulling apart
June-quarter revenue was $203.3m, up 19.1%, a deceleration from 21.5% in March. Cloud subscriptions, the part that should compound, reached $131.7m and grew 23%, with net expansion from existing cloud customers steady at 115%. The drag sits on either side of that line: non-cloud subscriptions growing at low-to-mid single digits, and a professional-services arm that grew 20% to $45.6m, faster than software, holding services at roughly 22% of revenue. The mix did not shift toward the higher-margin line; it held still.
Gross margin fell to 71.2% from 74.3% a year earlier. The compression came from the software side, where subscription gross margin slipped to 84% from 86% on the cost of serving artificial-intelligence features, while services margin actually widened to 31%. Meanwhile remaining performance obligations — contracted revenue not yet recognized — stood at $625.3m at 30 June, up 13%. The book grew more slowly than the revenue it feeds.
The cash line is where the quarter was won. Adjusted EBITDA of $16.2m beat guidance of $5m-8m, operating cash flow swung to a positive $12.1m from an outflow of $1.9m, and the company bought back 1.8m shares for $43.9m. Chief executive Matt Calkins, explaining why Appian pulled next year's hiring forward, told analysts on 6 August: "I think it might be an indication of strong pipeline that's unusually strong and also our confidence of being able to win in the current environment."
The federal book, and its new date
One customer set deserves separate accounting. US federal agencies supplied 25.3% of revenue in 2025, up from 23.9% in 2024 and 21.3% in 2023 — a concentration that has risen every year. The 30 September funding cliff that would have tested it was defused on 1 September, when the House passed a stopgap 370-48, funding the government to 11 December. The risk moved rather than cleared: a continuing resolution holds spending at prior-year levels, which keeps most new awards on hold, so a quarter of Appian's revenue base sits with buyers who cannot start much that is new until December at the earliest.
What the rerating is paying for
Appian now trades at 4.14x forward gross profit, against 3.07x in early May — roughly a 35% expansion in four months — and 32.1x consensus 2026 earnings of $1.08 a share. Consensus has revenue growth halving to 10.8% in 2027. Procore, the construction-management platform filed under the same software heading, did the opposite: it advanced 26% over three months and still trades at 6.65x forward gross profit, cheaper than the 7.96x it carried on 3 May, because a first quarter of GAAP operating profit and 24% growth in contracted obligations outran the share price.
The two moves are therefore bought with different currency. Procore's is paid for in reported cash flow. Appian's is paid for with a narrative — 85% of new logos taking AI-enabled tiers, a profitability beat — set against decelerating revenue, a thinner gross margin and a backlog growing slower than sales. What is not being paid for is the lawsuit: Pegasystems itself rose 15.6% over the past thirty sessions alongside Appian, which is not how a market prices a courtroom in which one side's gain is the other's loss.
Management has guided full-year cloud subscription revenue to $525m-529m, or 20% growth, against the 23% just delivered. The second half has to fund the multiple now, because the courthouse no longer will.