

Repligen Is Paying $1.5bn for a 98%-Consumables Business as Equipment Sales Stay Muted
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Repligen's earnings are consumed by the gram: its ligands, resins, columns and filters get used up in proportion to how much antibody its customers actually manufacture. The lumpy half of the business, capital equipment, is still muted — so the company is buying annuity instead of waiting for it.
Antitrust regulators cleared its purchase of BioLife Solutions on 3 September, leaving a shareholder vote before a fourth-quarter close. BioLife runs a 64% gross margin against Repligen's 53%. Repligen's own second quarter grew 13% organically and guidance went up, but reported growth has now decelerated for four straight quarters and the shares fetch 80x forward earnings.
Avantor sits under the same industry heading and inverts the thesis: the segment that most resembles Repligen shrank 5.6% organically while its thin-margin distribution arm returned to growth.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
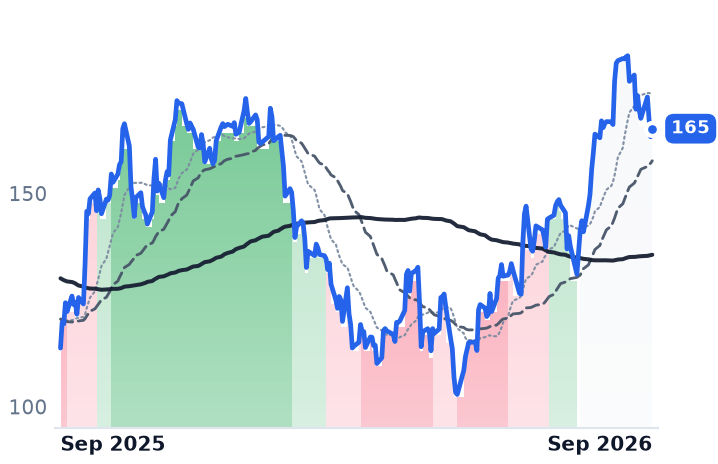
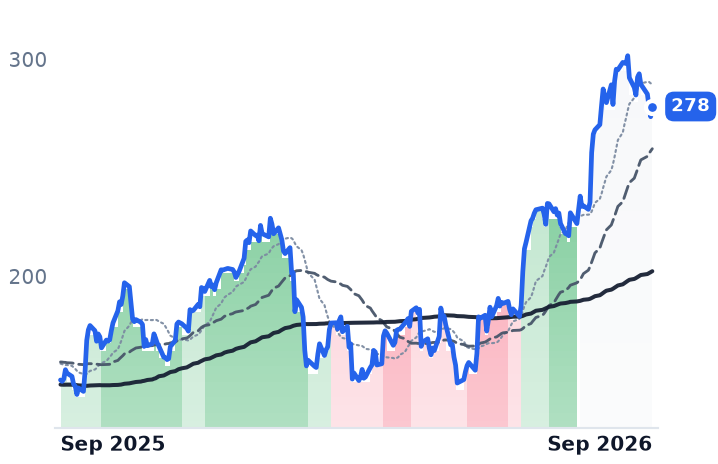
RGEN | Repligen | Bioprocessing & Cell Therapy | 🟢 Cont. Bull | −1.0% | +45.2% |
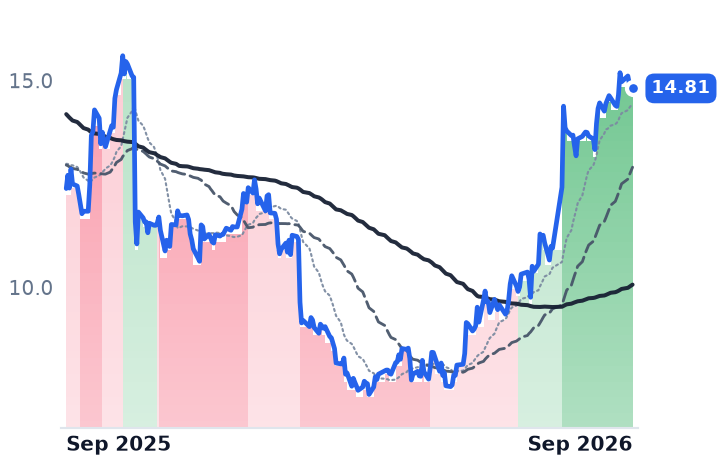
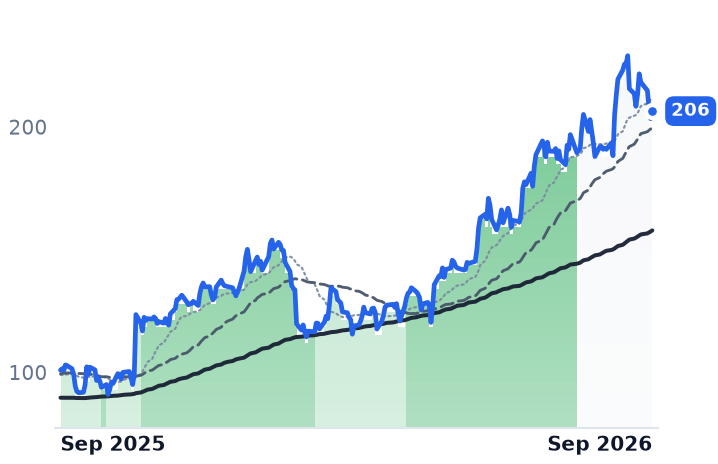
AVTR | Avantor | Bioprocessing & Cell Therapy | 🌱 Emerging Bull | +8.4% | +19.5% |
| Compared against · context, not the story | |||||
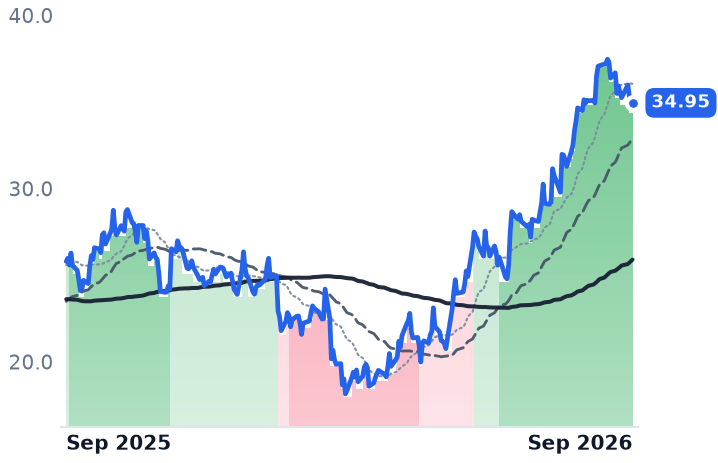
BLFS | BioLife Solutions | Bioprocessing & Cell Therapy | 🟢 Cont. Bull | −0.3% | +35.5% |
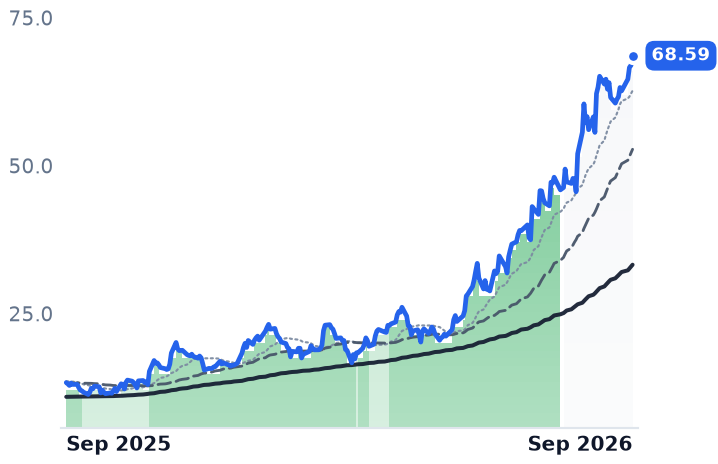
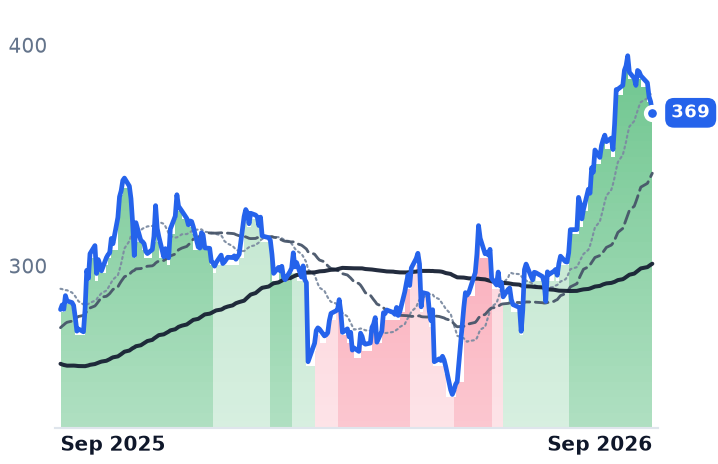
TXG | 10x Genomics | Genomics & Molecular Testing | 🟢 Cont. Bull | +22.3% | +413.8% |
CRL | Charles River Laboratories International | Contract Research & Development | 🟢 Cont. Bull | −0.6% | +82.8% |
ILMN | Illumina | Genomic & Molecular Sequencing | 🟢 Cont. Bull | +8.2% | +104.6% |
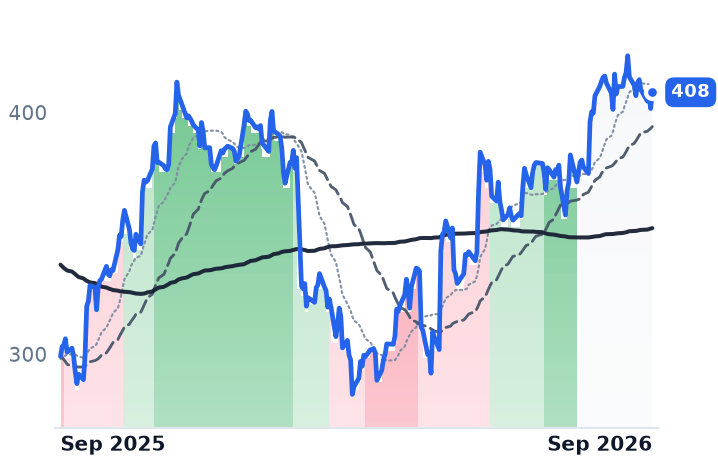
BIO | Bio-Rad Laboratories | Life Sciences & Diagnostics | 🟢 Cont. Bull | +3.7% | +31.8% |
WAT | Waters | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | −0.9% | +36.6% |
TMO | Thermo Fisher Scientific | Life Sciences Instruments & Consumables | ⚠️ Emerging Bear | +3.7% | +28.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RGEN | $9.3B | 223.2x | 80.1x | 11.9x | 11.3x | 23.3x | 22.1x | 77.2x | 1.2% |
BLFS | $1.7B | 33.8x | 58.3x | 16.6x | 14.9x | 25.8x | 23.1x | 173.7x | -0.1% |
AVTR | $10.0B | n/m | 18.2x | 1.5x | 1.5x | 4.8x | 4.8x | 107.0x | 4.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXG | $2.7B | n/m | — | 4.2x | 4.4x | 6.1x | 6.3x | n/m | 4.5% |
CRL | $7.3B | n/m | 13.6x | 1.8x | 1.9x | 5.7x | 5.9x | 12.6x | 5.4% |
ILMN | $21.6B | 25.6x | 27.4x | 4.9x | 4.7x | 7.3x | 7.0x | 18.9x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BIO | $6.7B | 39.5x | 27.0x | 2.6x | 2.6x | 5.0x | 5.0x | 218.6x | 5.3% |
WAT | $21.5B | 60.2x | 22.7x | 5.7x | 3.3x | 10.3x | 6.1x | 28.4x | 1.2% |
TMO | $162.9B | 23.8x | 17.6x | 3.6x | 3.4x | 9.1x | 8.7x | 18.2x | 4.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RGEN | Revenue | +12.9% | +17.2% | +16.3% |
| EPS | +23.9% | +27.8% | +31.0% | |
BLFS | Revenue | +19.3% | +17.6% | +22.7% |
| EPS | −278.0% | −48.0% | +172.4% | |
AVTR | Revenue | +1.0% | +2.4% | +3.4% |
| EPS | −9.8% | +8.7% | +8.1% | |
TXG | Revenue | −3.6% | +8.8% | +8.2% |
| EPS | +80.3% | −16.0% | −30.4% | |
CRL | Revenue | −3.9% | +1.8% | +4.4% |
| EPS | +8.3% | +11.1% | +9.5% | |
ILMN | Revenue | +6.2% | +5.5% | +6.6% |
| EPS | +10.2% | +13.1% | +14.5% | |
BIO | Revenue | +0.1% | +3.2% | +3.6% |
| EPS | −9.3% | +10.5% | +10.9% | |
WAT | Revenue | +103.6% | +10.0% | +5.9% |
| EPS | +10.6% | +12.9% | +10.3% | |
TMO | Revenue | +7.9% | +5.5% | +6.3% |
| EPS | +9.3% | +9.5% | +10.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Repligen agreed in July to buy BioLife Solutions, the Bothell, Washington maker of the CryoStor and HypoThermosol media in which cell therapies are frozen and shipped, and the antitrust waiting period expired at 11:59pm on 3 September, leaving a BioLife shareholder vote as the last condition before a fourth-quarter close.
The price is roughly $1.5bn of enterprise value — $11.25 a share in cash plus 0.1442 Repligen shares, 64% stock and 36% cash. What that money buys is a revenue mix. BioLife's sales are about 98% consumables, at a 64% gross margin and adjusted earnings before interest, tax, depreciation and amortization of $7.4m last quarter, 26% of revenue. Repligen is buying the part of its own model that works, because the other part still does not.
Paid by the gram
Repligen sells Protein A affinity ligands, CaptivA chromatography resins and OPUS pre-packed columns, XCell alternating tangential flow and KrosFlo filtration, and SoloVPE process analytics — the disposable flow path inside a biologics plant. Nearly all of it is consumed in proportion to grams of drug substance actually made, which makes the base business an installed-base-times-utilization annuity with a lumpy machine-sales line bolted on.
The annuity is working. Second-quarter revenue of $204.1m grew 13% organically, consumables rose in the high teens, proteins climbed about 50% and analytics more than 30%, and gross margin reached 53.1%, three points better than a year earlier. Full-year organic guidance went up to 10.5–13.5%, with adjusted earnings of $2.03–2.09 a share. Equipment revenue stayed muted, though chief executive Olivier Loeillot told investors on the July 28 call that second-quarter equipment book-to-bill was "significantly above one", with a second competitive award won and a third expected, building 2027 backlog.
Two things cut against it. Reported year-on-year growth has slowed every quarter for a year, from 21.9% to 11.9%. And on that 11.9%, GAAP operating income fell 14.2%, to $11.9m.
Repligen is also third in its signature socket: independent market work puts Danaher's Cytiva at roughly 35.7% of Protein A resin, Merck KGaA at 16.2% and Repligen at 13.6%. The offsetting fact is that Repligen supplies ligand to Cytiva and MilliporeSigma under supply agreements and buys base resin from Purolite, which this year extended five ligand programs to 2032 — so some per-gram economics accrue even when a rival's column wins.
The mirror that isn't one
Avantor, the Radnor, Pennsylvania distributor and producer of lab chemicals, consumables and single-use assemblies, is filed under the same heading and runs a different machine: a 31.7% gross margin, gross profit down 3.1% last quarter, and adjusted net leverage of 3.3x. Its second quarter inverted the obvious read. The VWR distribution arm returned to 1.7% organic growth from a 4.8% first-quarter decline, while the Bioscience & Medtech Products segment — the piece that resembles Repligen — fell 5.6% organically. "Our Revival program is strengthening how we serve our customers, leading to improved business performance," chief executive Emmanuel Ligner said in the results release. Consensus still has Avantor's 2026 earnings falling about 10%, to $0.81.
What the prices already hold
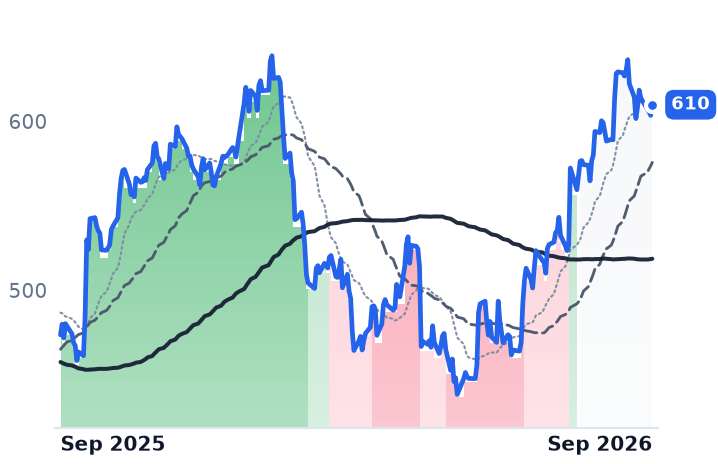
The whole life-science-tools shelf bottomed in March and re-rated together; 10x Genomics has more than tripled since. Customer funding is the plausible mechanism — trailing-twelve-month biotech capital raised through the second quarter reached $95bn, up 69%. Repligen gapped down 5.8% on the BioLife announcement and up 7.8% around its results; Avantor jumped 15.8% in a single session on 39.8m shares. Since mid-August Repligen has gone nowhere and Avantor has added nearly 8%. BioLife at $34.95 sits within a third of a percent of the $35.07 its merger terms imply, so its chart is now Repligen's chart.
The verdict splits. Repligen's operating record earns the direction of its move but not its level: 80x forward earnings, 22x forward gross profit, and still 48x consensus 2028 earnings of $3.45 — a price that assumes the return of 2022, when this business ran a 28% operating margin against roughly 6% today. Avantor's 4.8x price-to-gross-profit is the cheaper number by far, but it is being paid for a second derivative that has not yet reached the estimate line, and the only Avantor segment sharing Repligen's mechanism is the shrinking one.
The vote is the last gate. Clear it, and Repligen owns a high-margin annuity it did not have to wait for anybody's capital budget to release — while still waiting for the equipment orders that only a capital budget can release.