

Lamb Weston Guided 2027 Profit Flat Despite Cheaper Potatoes and a $250m Cost Program
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
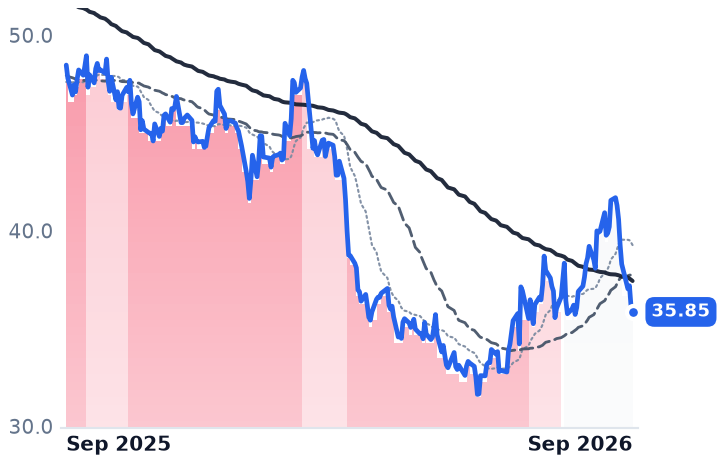
Lamb Weston's volumes are finally growing and its margins are not. Fourth-quarter sales volume rose 7% while price/mix fell 3%, and gross margin closed the year at 20.4% — identical to a year earlier. The cheaper 2026 potato crop, a closed plant in Argentina, a curtailed line in the Netherlands and a running cost program are all real, and the company's own outlook says they will be "mostly offset by inflation in essentially all other input cost areas." Adjusted profit is guided to roughly last year's level.
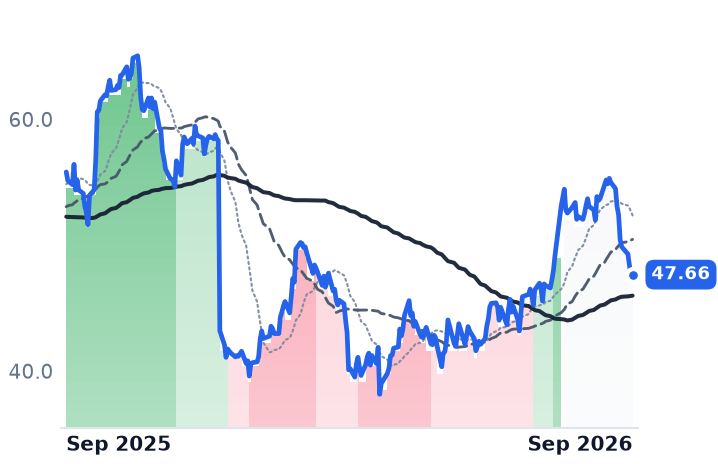
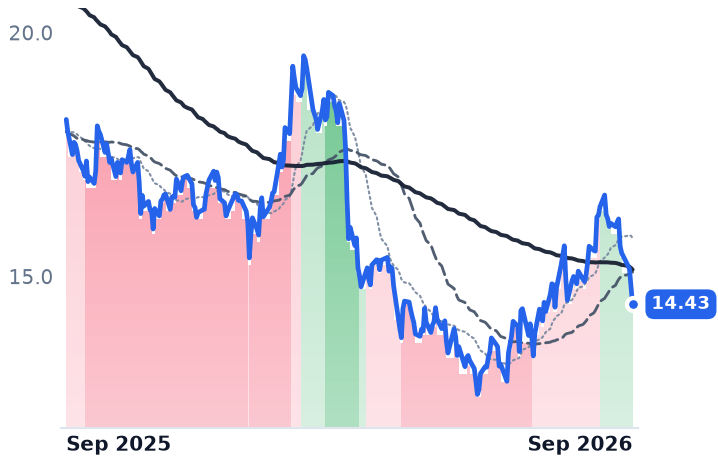
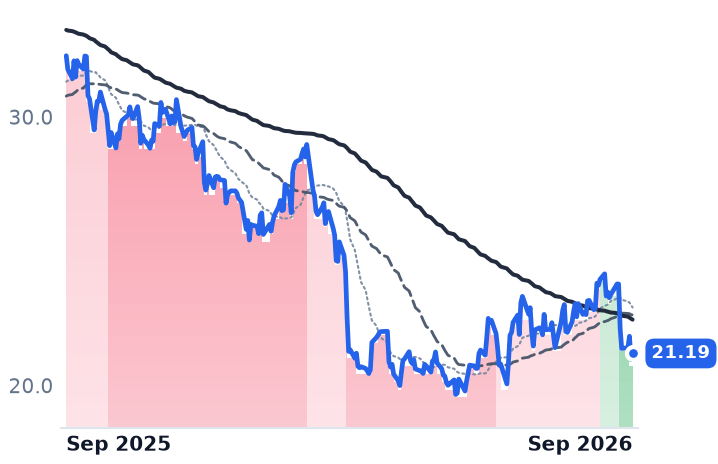
Conagra sits under the same frozen-foods heading on an unrelated cost line — tariffed tinplate steel and beef, worth more than $200m a year — with net debt at 3.83x and its dividend halved. The September slide in both was Campbell's doing, not theirs.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
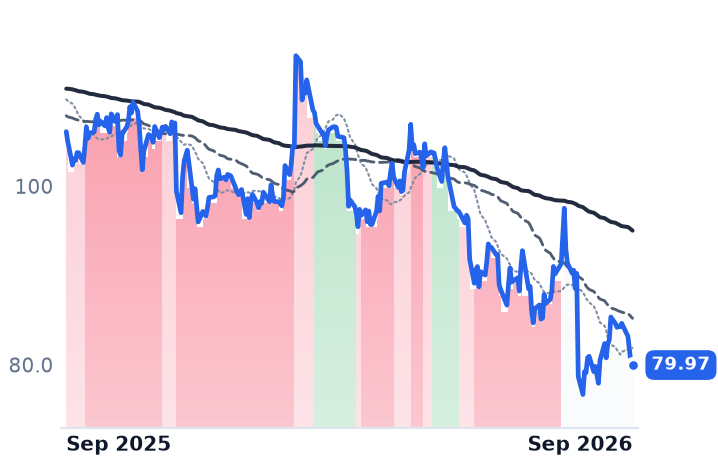
LW | Lamb Weston | Frozen & Prepared Foods | 🌱 Emerging Bull | −10.3% | −14.6% |
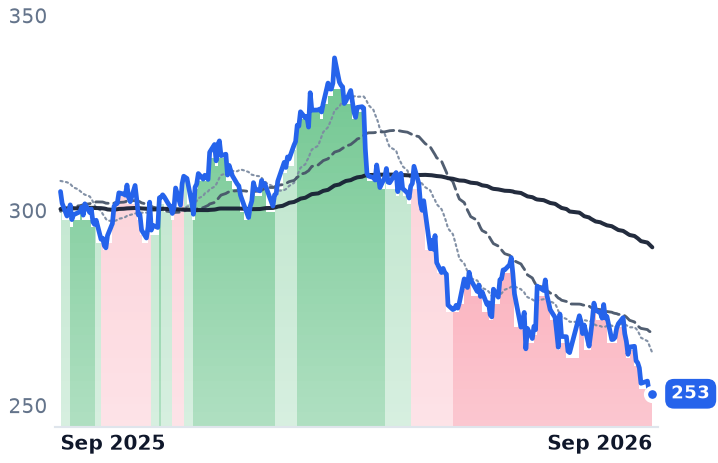
CAG | Conagra Brands | Frozen & Prepared Foods | 🔴 Cont. Bear | −4.0% | −20.8% |
| Compared against · context, not the story | |||||
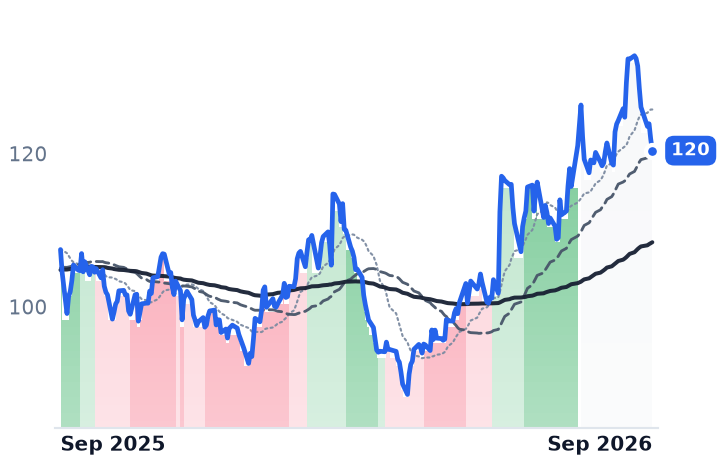
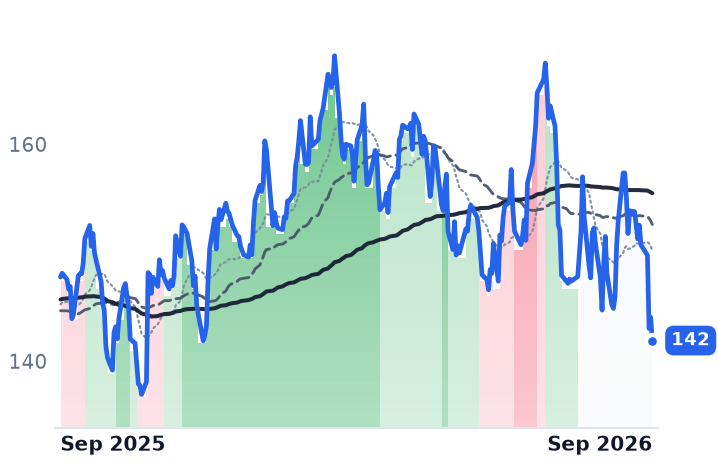
CPB | Campbell Soup | Frozen & Prepared Foods | 🌱 Emerging Bull | −6.4% | −34.3% |
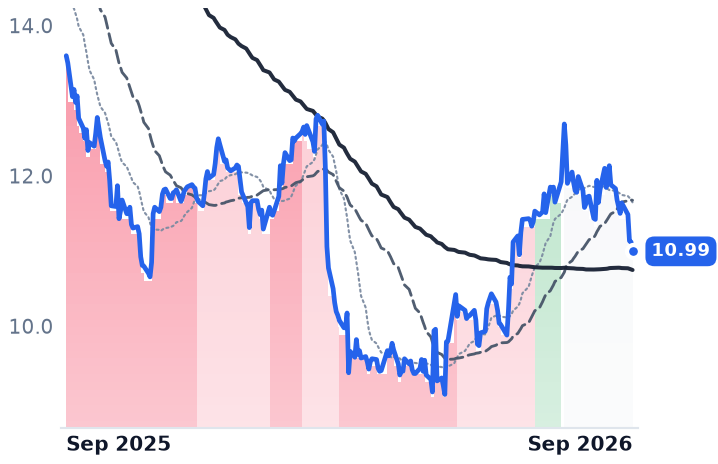
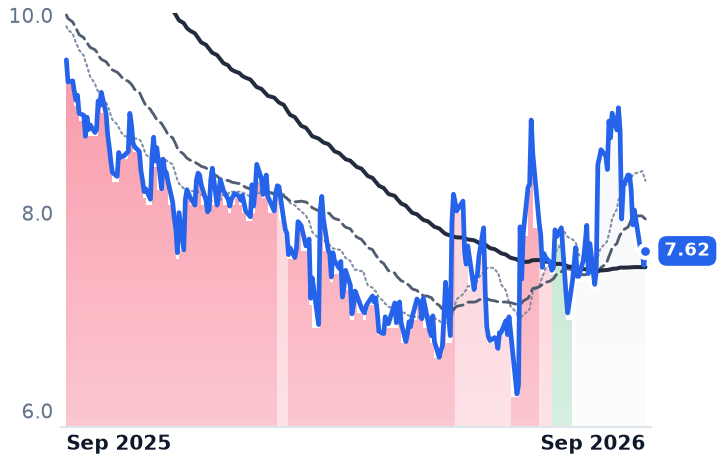
NOMD | Nomad Foods | Frozen & Prepared Foods | 🌱 Emerging Bull | −5.5% | −19.1% |
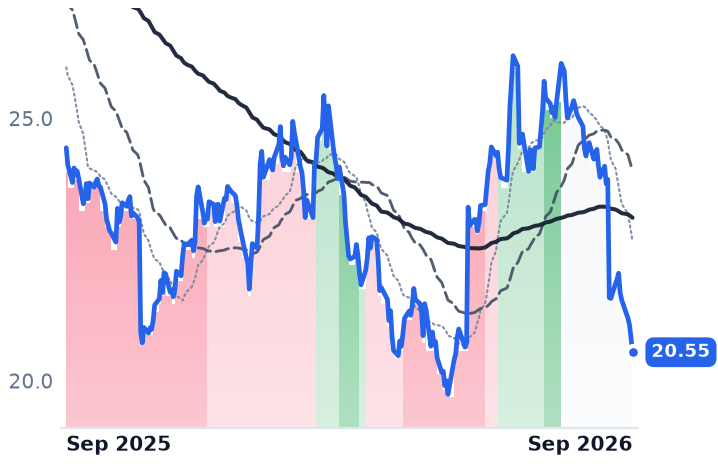
GIS | General Mills | Cereals & Breakfast | 🔴 Cont. Bear | −6.4% | −26.0% |
SJM | The J. M. Smucker | Pet Food & Nutrition | 🌱 Emerging Bull | +1.4% | +12.0% |
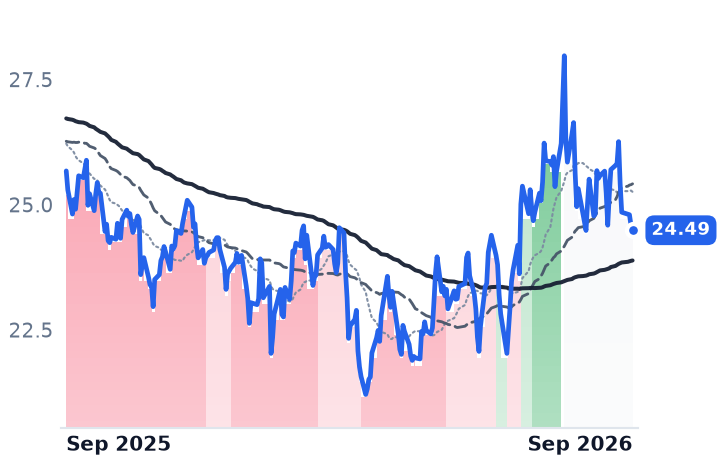
HRL | Hormel Foods | Meat & Protein Processing | 🌱 Emerging Bull | −15.4% | −15.9% |
KHC | The Kraft Heinz | Condiments & Sauces | 🌱 Emerging Bull | +0.0% | −4.6% |
POST | Post | Cereals & Breakfast | 🔴 Cont. Bear | +1.1% | −24.6% |
MCD | McDonald's | Quick Service - Burgers & Sandwiches | ⚠️ Emerging Bear | −8.3% | −17.0% |
YUM | Yum! Brands | Quick Service - Pizza | 🟢 Cont. Bull | −4.8% | −4.0% |
WEN | The Wendy's | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −10.3% | −20.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.9% | +16.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LW | $6.6B | 22.8x | 15.8x | 1.0x | 1.0x | 4.8x | 4.9x | 10.7x | 9.7% |
CAG | $7.0B | n/m | 10.1x | 0.6x | 0.6x | 2.6x | 2.7x | n/m | 14.0% |
CPB | $6.0B | 10.8x | 9.2x | 0.6x | 0.6x | 2.0x | 2.1x | 8.6x | 15.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOMD | $1.4B | 9.0x | 6.4x | 0.4x | 0.5x | 1.5x | 1.8x | 9.4x | 19.0% |
GIS | $17.6B | 8.1x | 9.6x | 1.0x | 1.0x | 2.9x | 2.9x | 10.1x | 9.4% |
SJM | $10.7B | n/m | 10.1x | 1.2x | 1.2x | 3.7x | 3.6x | n/m | 9.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HRL | $10.9B | 22.2x | 13.5x | 0.9x | 0.9x | 5.8x | 5.7x | 12.6x | 5.3% |
KHC | $27.2B | n/m | 11.1x | 1.1x | 1.1x | 3.3x | 3.3x | n/m | 14.5% |
POST | $4.6B | 14.3x | 13.1x | 0.5x | 0.5x | 2.0x | 2.1x | 8.3x | 15.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MCD | $196.4B | 22.6x | 21.2x | 7.2x | 6.9x | 12.5x | 12.0x | 16.8x | 3.6% |
YUM | $42.0B | 19.0x | 23.1x | 4.8x | 4.7x | 10.5x | 10.2x | 18.6x | 4.0% |
WEN | $1.5B | 8.9x | 13.9x | 0.7x | 0.7x | 2.6x | 2.6x | 10.3x | 14.6% |
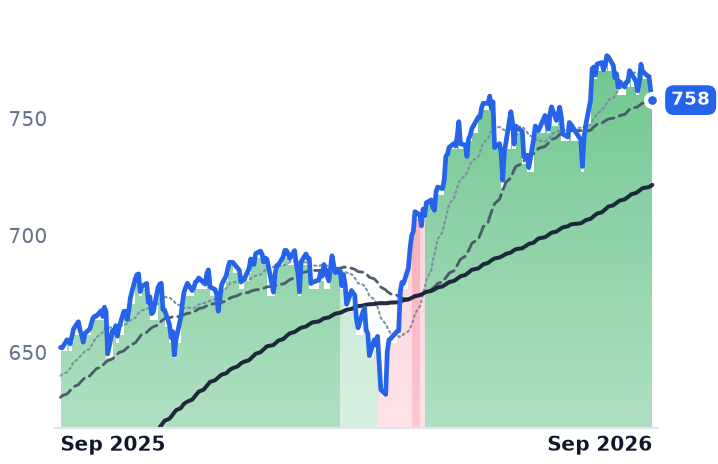
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LW | Revenue | +2.7% | −0.4% | +1.6% |
| EPS | −10.9% | +9.0% | +11.5% | |
CAG | Revenue | −3.2% | −3.9% | −0.4% |
| EPS | −26.7% | −14.6% | +3.7% | |
CPB | Revenue | −4.7% | −0.2% | +0.6% |
| EPS | −25.4% | −1.0% | +5.3% | |
NOMD | Revenue | −1.7% | +1.8% | −0.3% |
| EPS | −6.8% | +8.7% | +6.6% | |
GIS | Revenue | −5.6% | −2.5% | +1.0% |
| EPS | −18.2% | −4.5% | +4.0% | |
SJM | Revenue | +3.2% | +1.0% | +1.5% |
| EPS | −10.2% | +10.4% | +8.5% | |
HRL | Revenue | +1.3% | +1.5% | +2.6% |
| EPS | +7.4% | +7.0% | +5.5% | |
KHC | Revenue | −2.0% | +0.6% | +1.1% |
| EPS | −18.6% | +1.4% | +4.4% | |
POST | Revenue | +2.2% | −0.2% | −0.0% |
| EPS | +9.5% | +13.5% | +14.4% | |
MCD | Revenue | +6.9% | +5.7% | +4.9% |
| EPS | +7.2% | +9.1% | +7.5% | |
YUM | Revenue | +10.0% | +3.7% | +5.7% |
| EPS | +8.5% | +10.2% | +10.8% | |
WEN | Revenue | +1.5% | +0.5% | +4.2% |
| EPS | −33.9% | +11.8% | +12.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Lamb Weston sold materially more frozen potatoes in its fiscal fourth quarter and made less money doing it. Net sales rose 6%, led by a 7% increase in sales volume against a 3% decline in price/mix, and gross margin came in at 20.4% — the same figure as the prior-year quarter. Operating income fell 9.1%.
That is the whole question in front of the company, which manufactures fries, commercial ingredients and appetizers in Eagle, Idaho and sells them mostly business-to-business, to restaurant chains and foodservice distributors, under multi-year contracts. Its earnings are a spread between a potato cost contracted once a year with growers and a price it cannot reset mid-term, with utilization of its processing lines as the swing factor. Fiscal 2027 is supposed to be the year the spread widens. Management has already told investors it will not.
The tailwind is spent before it arrives
Lamb Weston's own fiscal 2027 outlook says the benefits of lower raw potato costs, supply-chain savings, better fixed-cost absorption and the lapping of fiscal 2026 potato write-offs are "anticipated to be mostly offset by inflation in essentially all other input cost areas." Adjusted EBITDA is guided to $1.1–1.2bn against $1,147m delivered, on sales guided flat to up 1%.
The crop cuts both ways. North American contracted acreage is expected to fall at least 10% for 2026, and the fry industry has signaled intent to lower contract prices by 3 to 5 cents per kilogram — a cheaper ton bought, and a cheaper contract sold. Underneath that, the end market is soft: US frozen potato exports fell 12.8% in the first quarter, and quick-service restaurant foot traffic was down 1.6% year on year in May on a higher average check. The National Restaurant Association counted 45% of operators reporting lower customer traffic that month, the fifteenth net decline in sixteen months.
So the company is managing absorption directly: it is closing its Munro plant in Argentina and curtailing a Netherlands line, affecting about 110 employees at $80m–$110m of pre-tax charges, alongside a roughly 4% workforce cut. Its Focus to Win program targets at least $250m of annualized run-rate savings by the end of fiscal 2028 and cleared its $100m milestone this year. The pressure is external: the board was expanded to 13 seats under an agreement with Jana Partners and Continental Grain, and Starboard Value has pressed for 25% adjusted EBITDA margins by fiscal 2029. "This past year marked an important inflection point for our Company," chief executive Mike Smith said on July 24. North America delivered segment EBITDA up 17% at a 26% margin; International EBITDA fell 55% on European price/mix and a $33.1m potato write-off.
Conagra's problem is metal and meat
Conagra — Birds Eye, Healthy Choice, Marie Callender's, Slim Jim, sold at retail shelf price through a handful of grocers — shares the frozen-foods label and none of the economics. Its cost shock is tariffs on the tinplate steel and aluminum in its cans, which the company put at 3% of cost of goods sold, more than $200m a year, plus beef inflation. Fiscal 2026 revenue fell 2.9% to $11.28bn and gross margin slid to 23.9% from 27.7% two years ago; a roughly $2bn goodwill and brand impairment produced a net loss. Net debt ended at $7.1bn, or 3.83x, against a 3.0x target, and the quarterly dividend was halved to $0.175. "I really believe a balanced approach to capital allocation is critical to the long-term success of the company," chief executive John Brase said on the July 15 call. Fiscal 2027 organic sales are guided down 1–3% with volumes down mid-single digits, and an incremental $125m goes into supply-chain resilience.
What the last two weeks actually were
Both shares fell hard in early September, and neither announced anything. The trigger was Campbell's September 3 results: a sales miss, adjusted gross margin down 190 basis points to 28.6%, fiscal 2027 earnings guided 17–24% lower and a 36% dividend cut. From September 2 to September 11, Campbell's fell 10.9%, Conagra 10.8% and Lamb Weston 9.1% — and so did General Mills, down 11.7%, J.M. Smucker, Kraft Heinz and Post, against roughly 1% for the broad market. Structural pressure sits behind it: GLP-1 medications are now used by about 18% of US adults, up from roughly 14% a year earlier, with users spending less per grocery trip.
The September leg neither protagonist earned. The twelve-month de-rating they did: Lamb Weston's diluted earnings of $2.08 are less than half the $4.98 of fiscal 2024, and it trades at 15.8x forward earnings against 22.8x trailing and 10.7x trailing enterprise value to EBITDA — inexpensive against profit guided to stand still. Conagra's trailing multiple is meaningless after the impairment; its 10.1x forward earnings applies to a consensus that has earnings falling another 14.6% before any recovery in fiscal 2028.
The useful meter at Lamb Weston is no longer revenue, which has now grown four quarters running. It is gross margin and factory absorption, because the company has told everyone what the cheaper crop is worth net of everything else. Volume that arrives at a 3% lower price into flat profit guidance is share bought with margin.
Lamb Weston reports on October 1, into a crop whose savings it has already promised away.