

Teleflex Cut Its Growth Guidance and Raised Earnings With a $700m Debt Paydown
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Teleflex is not splitting itself in two after all — it sold the pieces instead, for $2.03bn in cash. What is left cut its revenue growth guidance in August and raised its earnings guidance in the same breath, the raise sourced from a debt paydown, a buyback and a lower tax rate rather than from selling more devices.
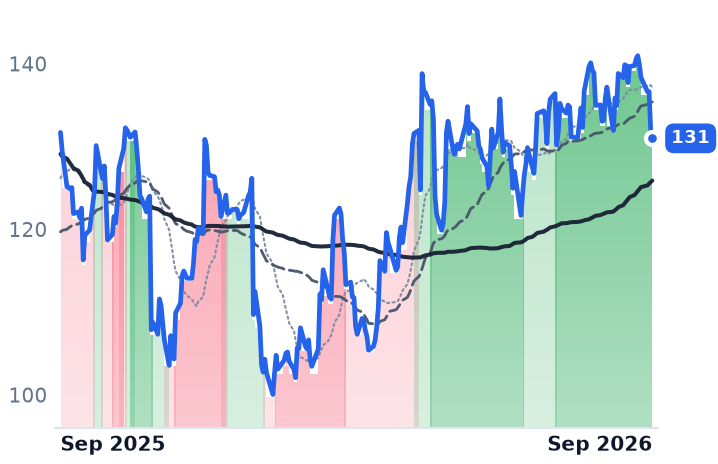
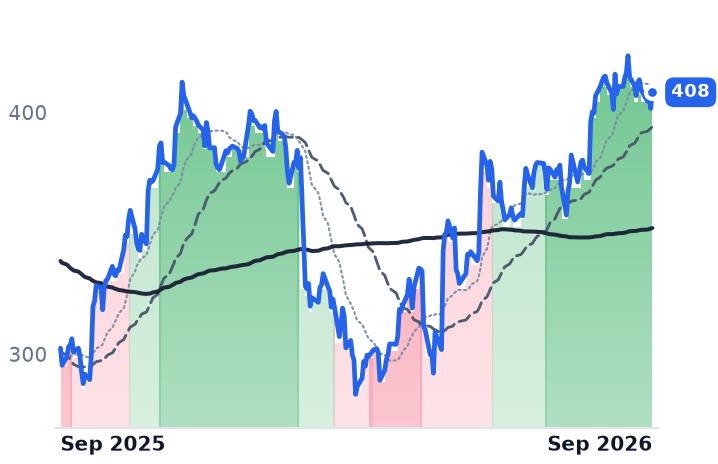
Interventional, the business it bought from BIOTRONIK to build scale in cardiology, shrank 1% as the integration slipped to the end of 2026, and adjusted operating margin fell to 19.6% against management's 23% target. The shares made a 52-week high on 1 September regardless. Merit Medical, selling into the same hospital vascular socket, grew 9% organically — and is the only one of these four names down over twelve months.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TFX | Teleflex Incorporated | Intravenous Access & Infusion | 🟢 Cont. Bull | −1.6% | −0.5% |
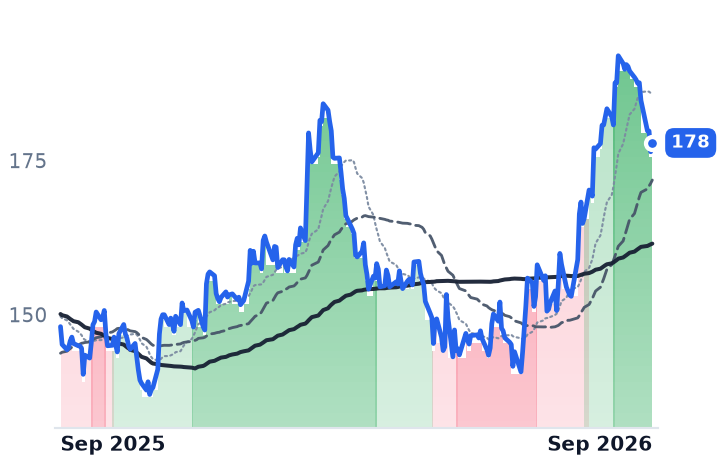
BDX | Becton, Dickinson and | Intravenous Access & Infusion | 🟢 Cont. Bull | −1.6% | +20.1% |
| Compared against · context, not the story | |||||
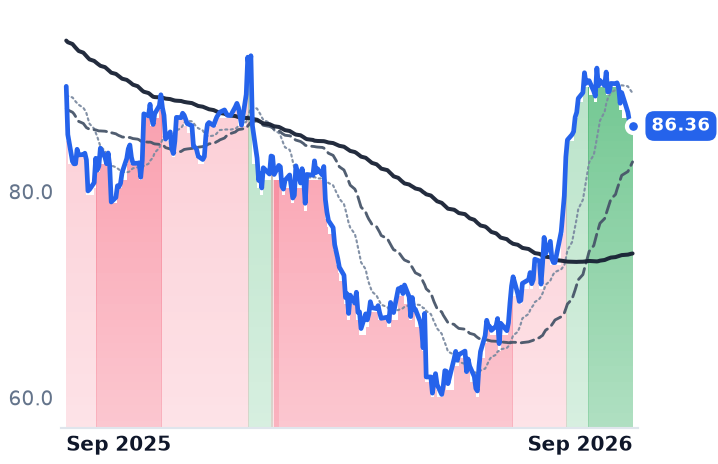
MMSI | Merit Medical Systems | Cardiovascular Intervention & Monitoring | 🌱 Emerging Bull | −4.6% | −4.3% |
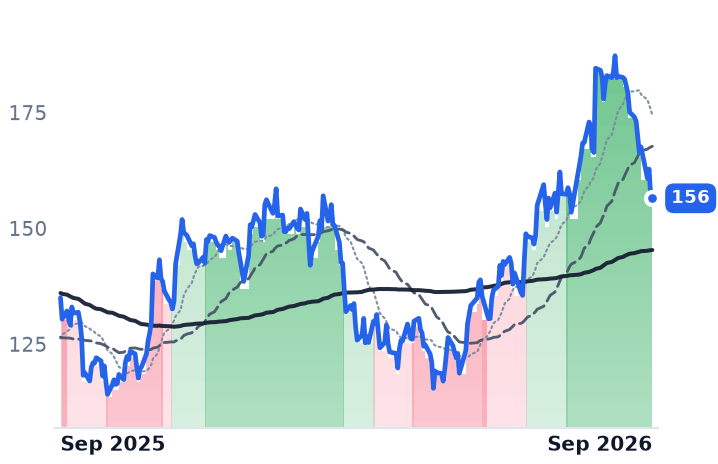
ICUI | ICU Medical | Intravenous Access & Infusion | 🌱 Emerging Bull | −12.0% | +15.9% |
WAT | Waters | Analytical Instruments & Reagents | 🟢 Cont. Bull | −1.5% | +35.0% |
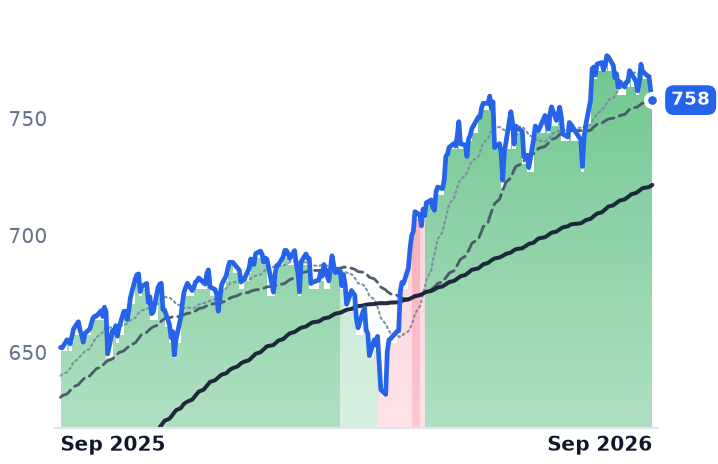
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.1% | +17.2% |
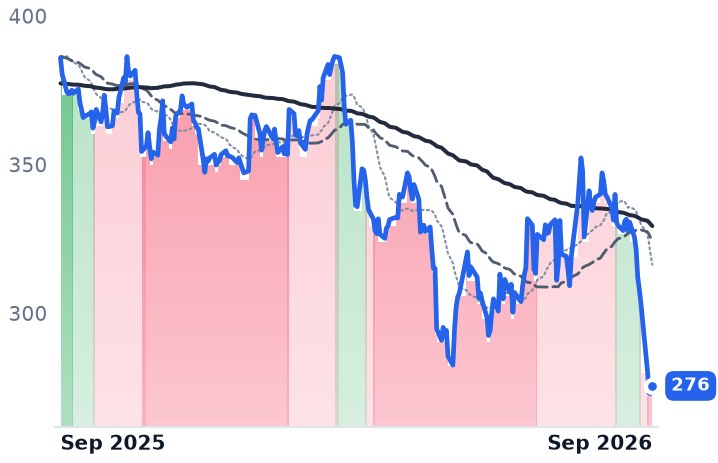
SYK | Stryker | Orthopedic & Spine Implants | 🔴 Cont. Bear | −20.0% | −28.6% |
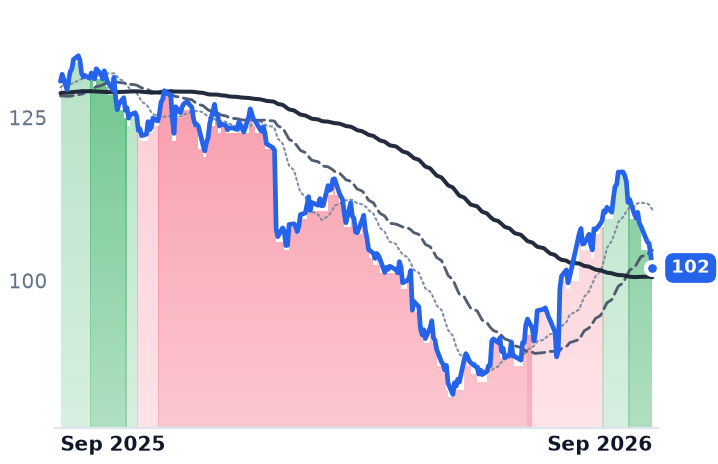
ABT | Abbott Laboratories | Clinical & Molecular Diagnostics | 🌱 Emerging Bull | −7.9% | −21.9% |
GEHC | GE HealthCare Technologies | Diagnostic Imaging | ⚠️ Emerging Bear | −11.9% | −17.9% |
ZBH | Zimmer Biomet | Orthopedic & Spine Implants | 🌱 Emerging Bull | −2.6% | −9.6% |
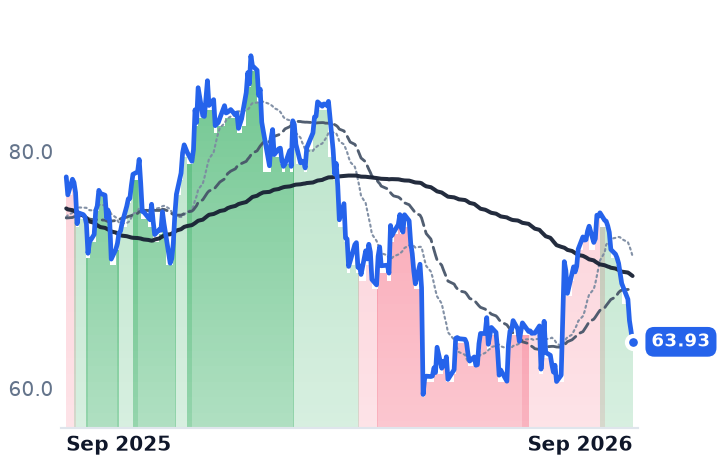
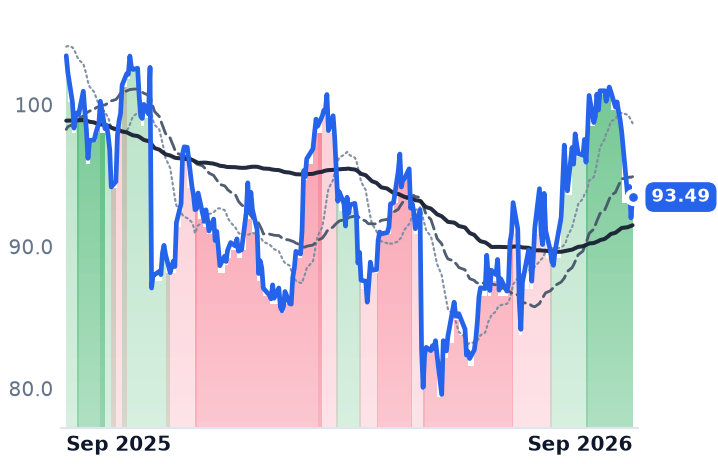
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TFX | $5.8B | n/m | 18.3x | 2.2x | 2.6x | 4.2x | 4.8x | n/m | 6.7% |
BDX | $48.6B | 53.1x | 13.9x | 2.3x | 2.5x | 5.1x | 5.5x | 16.6x | 5.4% |
MMSI | $5.2B | 35.3x | 20.1x | 3.3x | 3.2x | 6.6x | 6.4x | 15.3x | 3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ICUI | $3.9B | 131.1x | 18.0x | 1.8x | 1.8x | 4.8x | 4.8x | 16.5x | 3.9% |
WAT | $41.3B | 104.6x | 28.9x | 8.9x | 6.4x | 17.5x | 12.6x | 51.4x | 1.0% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SYK | $127.6B | 35.5x | 22.6x | 4.9x | 4.8x | 7.4x | 7.3x | 21.1x | 3.6% |
ABT | $183.8B | 39.3x | 19.2x | 3.8x | 3.7x | 6.7x | 6.4x | 21.8x | 4.7% |
GEHC | $30.9B | 19.7x | 13.9x | 1.5x | 1.4x | 3.6x | 3.3x | 12.7x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZBH | $20.4B | 26.9x | 12.5x | 2.4x | 2.4x | 3.4x | 3.4x | 12.0x | 8.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TFX | Revenue | −31.2% | +4.3% | +4.6% |
| EPS | −48.6% | +52.0% | +10.6% | |
BDX | Revenue | −11.7% | +2.1% | +3.8% |
| EPS | +12.1% | +4.9% | +6.6% | |
MMSI | Revenue | +8.2% | +6.1% | +5.9% |
| EPS | +14.8% | +7.2% | +7.6% | |
ICUI | Revenue | −0.8% | +4.2% | +3.9% |
| EPS | +15.4% | +10.6% | +7.5% | |
WAT | Revenue | +104.2% | +10.4% | +5.9% |
| EPS | +11.1% | +13.2% | +11.5% | |
SYK | Revenue | +7.0% | +7.1% | +7.5% |
| EPS | +9.4% | +10.0% | +10.8% | |
ABT | Revenue | +11.9% | +7.4% | +6.5% |
| EPS | +7.1% | +7.6% | +9.5% | |
GEHC | Revenue | +5.8% | +4.6% | +4.7% |
| EPS | +8.2% | +10.4% | +11.2% | |
ZBH | Revenue | +4.7% | +3.6% | +3.9% |
| EPS | +4.4% | +6.1% | +7.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Teleflex spent 2025 preparing to split itself into two listed companies. It sold three businesses instead, agreeing in December to $2.03bn of cash deals — the OEM unit to Montagu and Kohlberg, Acute Care and Interventional Urology to Britain's Intersurgical. The OEM sale closed on 3 August for $1.5bn; the Intersurgical piece is still pending. There is no stub to value, only a smaller company.
That smaller company told investors three days later that it would grow more slowly than promised and earn more than promised. Full-year constant-currency revenue growth guidance came down to 3.5-4.5% from 4.5-5.5%. Adjusted earnings guidance went up, to $6.90-$7.20 a share from $6.25-$6.55. The raise was sourced from a $700m debt paydown, a $250m accelerated repurchase launched on 7 August, net interest expense cut to roughly $85m, and a tax rate trimmed to about 12.25%. None of it came from demand.
The hole is in the business it bought
Teleflex sells single-use critical-care and surgical devices — the Arrow vascular catheter family, the MANTA closure device, the UroLift system for enlarged prostates. It bought BIOTRONIK's vascular-intervention business to add scale in interventional cardiology, and that is the segment now going backwards: Interventional revenue fell 1% to $211.9m in the June quarter, against Vascular up 8% and Surgical up 9.2%. The integration that was to finish by mid-2026 now runs to the end of it, on order-to-cash system transitions that left customers confused, distributors working down inventory, and a repositioned sales force with roughly six-month onboarding. It is "not a product issue," chief executive Jason Weidman told investors on the August 6 call; the portfolios "fit beautifully together."
Margins moved with it. Gross margin fell 280 basis points to 61.7% on tariffs and the lower-margin acquired business, and adjusted operating margin fell 520 basis points to 19.6%. Full-year operating margin is guided to about 19% against the 23% steady state management says the post-divestiture company should reach. Part of that gap is chosen — research spending was lifted to 7.9% of sales from a historical 6% — and part is the cost of a company that has shed roughly a third of its revenue and not yet shed the overhead behind it.
What the same end market is doing
Demand is not the problem. Merit Medical, which sells disposable vascular-access, angiography and hemostasis devices into the same hospital departments, grew 9% organically in constant currency, its best quarter in three years, expanded gross margin by 314 basis points and raised full-year organic guidance to 6.9-7.5%. It trades at 20.1x forward earnings, the richest of the four, and is the only one down over twelve months, by 2.6%.
Becton Dickinson is the counter-case for restructuring done. Its Biosciences and Diagnostic Solutions business went to Waters in a deal that closed on 9 February, taking China down to 4% of revenue; every one of the four segments left grew in the June quarter, organic growth was 4.4%, and earnings guidance was raised to $12.62-$12.72. At 13.9x forward it is the cheapest of the group, up from roughly 11.7x in June. ICU Medical, which makes infusion pumps, needle-free connectors and IV solutions, grew reported revenue 0.5% but widened gross margin from 37.9% to 42.6% and raised guidance twice over; it sits at 18.0x.
All four are absorbing tariffs — 110 basis points of margin at BD, $0.21 a share at Merit, $30m-$40m a year at ICU Medical — and all four sell the exact products named in the unresolved Section 232 national-security investigation into syringes, catheters and IV bags.
The verdict
Teleflex's Vascular and Surgical numbers are earned; the share price is not yet. Its forward multiple has climbed from roughly 15.5x in March to 18.3x now on an unchanged consensus of $7.20 — a re-rating delivered across the same six months in which the company cut growth guidance and pushed out an integration. Measured against gross profit, the shares cost more on next year's figures than on last year's, because the profit base is shrinking faster than the price. What is being paid for is a consensus 2027 earnings rebound of 52% that management has framed only as a "meaningful step-up," and the standing possibility, pressed publicly by Irenic Capital, that the whole company is sold.
Weidman is two months into the job, still running a comprehensive review, and has promised more direction at the next call. Until it arrives, the most consequential thing Teleflex did for holders this year was write checks with the proceeds of businesses it no longer owns.