

Nova Grew 16% to a Record $255m Quarter While Camtek's Growth Slowed to 8%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two Israeli chip-metrology makers are being repriced as one group, and their businesses are moving in opposite directions. Nova's June-quarter revenue accelerated to a record, operating margin held at 29.9%, and management guided the September quarter to $277-287m — roughly 25% above a year earlier. Camtek's reported operating income fell 14.8% year over year on 8% revenue growth, even as it disclosed more than $600m of orders booked so far this year with deliveries running into 2027.
The market has done the reverse of what the reported numbers suggest: Camtek still carries the highest forward earnings multiple of the four listed process-control names, while Nova's has compressed from roughly 57x in mid-June to 34x. Both fell in the same August sessions, alongside Onto and KLA.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NVMI | Nova | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −8.5% | +29.0% |
CAMT | Camtek | Test & Assembly Services | ⚠️ Emerging Bear | −14.8% | +75.9% |
| Compared against · context, not the story | |||||
ONTO | Onto Innovation | Fabrication Equipment & Materials | 🟢 Cont. Bull | −16.6% | +159.8% |
FORM | FormFactor | Test & Assembly Services | ⚠️ Emerging Bear | −10.8% | +276.0% |
KLAC | KLA | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −13.3% | −81.1% |
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | +4.9% | +548.7% |
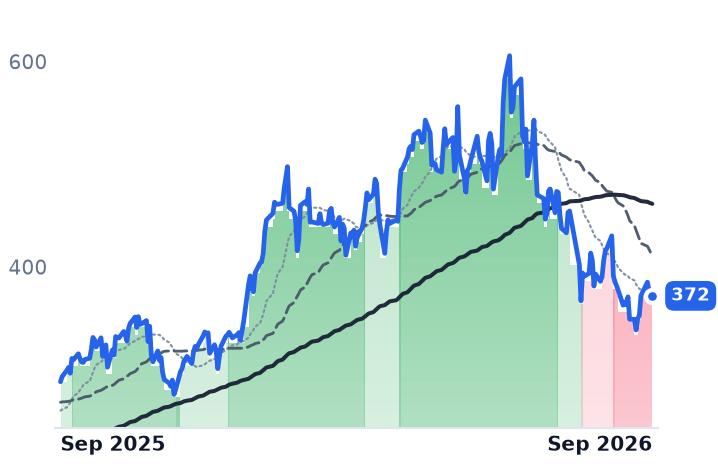
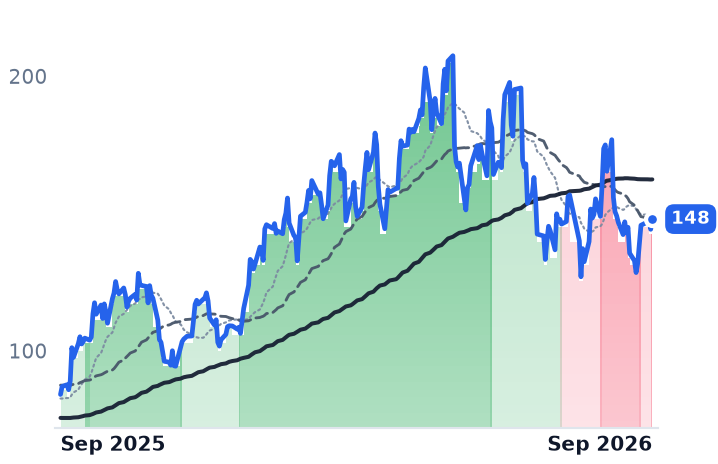
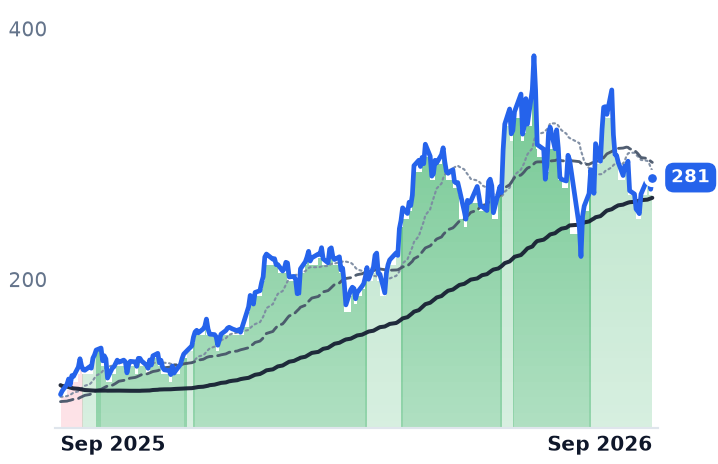
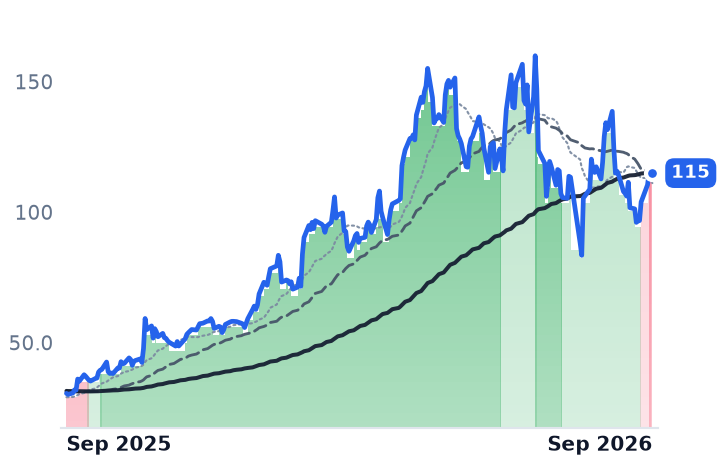
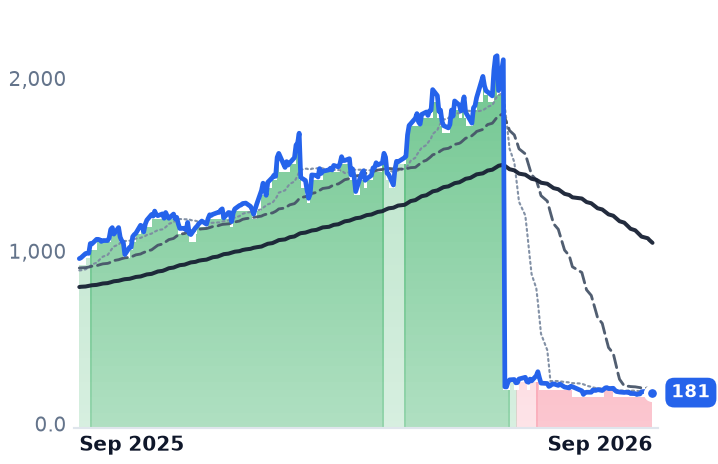
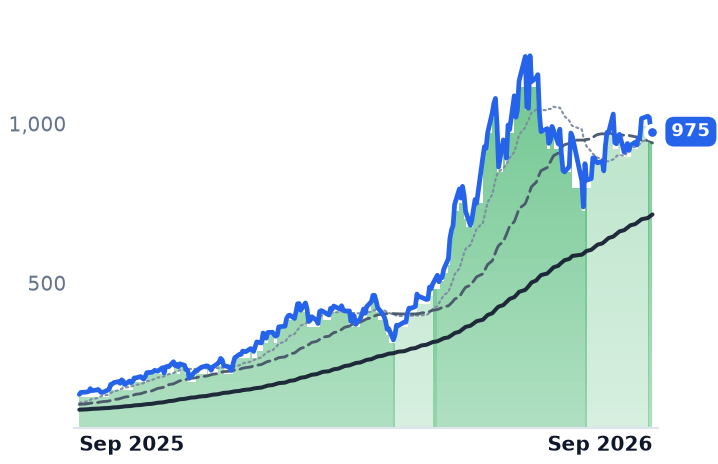
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVMI | $10.1B | 36.1x | 29.8x | 10.6x | 9.4x | 18.6x | 16.4x | 32.2x | 2.0% |
CAMT | $4.5B | 33.7x | 26.9x | 8.3x | 7.6x | 16.6x | 15.2x | 35.8x | 0.0% |
ONTO | $8.5B | 64.7x | 21.4x | 7.6x | 5.9x | 15.1x | 11.7x | 35.1x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FORM | $6.3B | 36.5x | 24.0x | 6.5x | 6.0x | 13.1x | 12.2x | 27.3x | 2.9% |
KLAC | $180.4B | 34.4x | 24.0x | 12.4x | 9.6x | 20.2x | 15.6x | 28.2x | 2.2% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NVMI | Revenue | +22.6% | +26.2% | +17.4% |
| EPS | +23.1% | +28.0% | +21.4% | |
CAMT | Revenue | +20.5% | +35.0% | +17.0% |
| EPS | +12.5% | +42.4% | +18.0% | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
FORM | Revenue | +34.6% | +24.3% | +26.7% |
| EPS | +199.2% | +29.0% | +38.5% | |
KLAC | Revenue | +12.2% | +39.5% | +20.1% |
| EPS | +14.5% | +55.5% | +23.1% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Nova, which sells process-control metrology systems — the film, materials, chemical and dimensional measurement tools chipmakers run between the steps that build a wafer — reported record revenue of $255m before the Nasdaq open on 6 August and guided the September quarter higher still. Its shares closed down 6.2% that day, and by 10 September stood 39% below their 15 June close of $605.65.
Process-control metrology is where the artificial-intelligence construction budget first becomes a measurable order: before memory stacks ship, someone buys the tools that inspect and measure them. Three months of selling have priced Nova, Camtek, Onto Innovation and KLA as a single trade. They are not one business. Nova's revenue tracks wafer-start capacity and the industry's move to gate-all-around transistors at leading-edge logic; Camtek's tracks back-end advanced packaging lines. Over the summer both de-rated hard — one into accelerating numbers, the other into decelerating ones.
Nova: records, and a lower price
Nova's growth has been speeding up, from 14.3% year over year in the December quarter to 10.3% in March and 15.9% in June. Operating margin was 29.9%, against 29.8% a year earlier, so the growth arrived without leakage. Guidance for the September quarter of $277-287m implies roughly 25.5% growth on the $224.6m booked a year ago. The company attributed the quarter to advanced logic on the gate-all-around transition and to record advanced-packaging revenue from capacity increases across logic and memory — two demand clocks inside one income statement. "This quarter marks a significant milestone for Nova, surpassing $250 million in quarterly revenue and $2.50 in quarterly non-GAAP EPS, reflecting the run-rate envisioned in our long-term strategic plan," said Gaby Waisman, president and chief executive, on 6 August.
Camtek: the order book and the P&L disagree
Camtek, a 709-person company in Migdal HaEmek that sells automated optical inspection and 2D/3D metrology systems into back-end packaging, has the opposite problem. June-quarter revenue rose 8.0% to $133.2m, operating margin fell to 20.4% from 25.9%, and operating income declined 14.8% — the second straight quarter of falling operating profit. Gross margin was flat at 50.1%, so the compression came from operating expenses rather than a slide back toward cheaper older platforms; its newer Eagle G5 and Hawk systems were half of systems revenue.
The forward-looking disclosure says something else entirely. More than $600m of orders have been received year to date, about 80% of them advanced packaging, with deliveries stretching into 2027 — more than four quarters of work against a $593m consensus revenue estimate for this year. Chief operating officer Ramy Langer told investors on the 10 August call that more than 20% of those orders came from high-bandwidth-memory manufacturers and more than half from outsourced assembly and test houses. Chief executive Rafi Amit said about 75% of second-quarter revenue came from advanced packaging, mostly AI-related. China is guided to about 45% of 2026 revenue, down from 49%, with the company's own risk disclosures naming further US export controls as a threat to that business.
What the group's numbers hide
Camtek trades at about 40x forward earnings and 29.5x the 2027 consensus, against Nova at 34x forward and 26.8x 2027, Onto at 33x and FormFactor at 37x. The slowest-growing of the four is the dearest. FormFactor, meanwhile, explains most of the group's apparent boom: its shares are up 286% over twelve months against Camtek's 79% and Nova's 33%, and it sells probe cards — consumables billed per test insertion, tracking wafer starts rather than capacity orders. Its June-quarter gross margin was 50.7%, up from 37.2%, and it guided the current quarter to $270m give or take $10m.
The selling itself was concentrated and shared. All four names peaked on 17 August and bottomed on 1 September; on 18 August, the 30-year Treasury yield topped 5.33%, a 19-year high, and Camtek fell 11.9%, Nova 9.1%, Onto 10.2% and KLA 5.3% in that one session. Since 1 September, Camtek has recovered 13.2% and Nova 9.2%.
The verdict
Camtek's de-rating is earned in part: two quarters of falling operating profit at a premium valuation is a fact, and consensus still asks for a sharp reacceleration to reach $593m this year. What nothing in Camtek's reported P&L supports is the order book, which says the slowdown is timing between shipment dates. Nova's case is cleaner and stranger — revenue accelerating, margins steady, guidance up a quarter year over year, and a share price a third lower than in June. The likelier reading is a discount-rate shock compressing a 57x multiple, not a demand signal. At 34x forward, that cushion is gone in both directions.
What sits under both order books is memory capacity that does not exist yet: Micron is adding as many as 60,000 high-bandwidth-memory wafers a month toward roughly 100,000 by year-end, capacity that ships product in 2027 and buys tools now. Micron reports on 30 September, and it will be the first outside read on whether the tools are still being bought.