

Navitas Moved Its In-Rack 800-Volt Date to Early 2028, Six Weeks After Saying 2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Navitas's own date for the technology it is named for has moved away from it. At Citi's conference on 8 September the company placed native 800-volt systems — voltage conversion moved inside the compute tray — in early 2028; on its 27 July call it had dated that gallium-nitride content in accelerators to mid-to-late 2027.
The business it still has is shrinking in the meantime: June-quarter revenue of $10.5m, down 27.3% from a year earlier, against $557m of cash and no debt. Monolithic Power, on the same Nvidia supplier list, grew revenue 47.6% in the same quarter and has been repriced to roughly the same forward price against gross profit as Vicor, which grew 1.6%.
One of those de-ratings the numbers explain. The other they do not.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
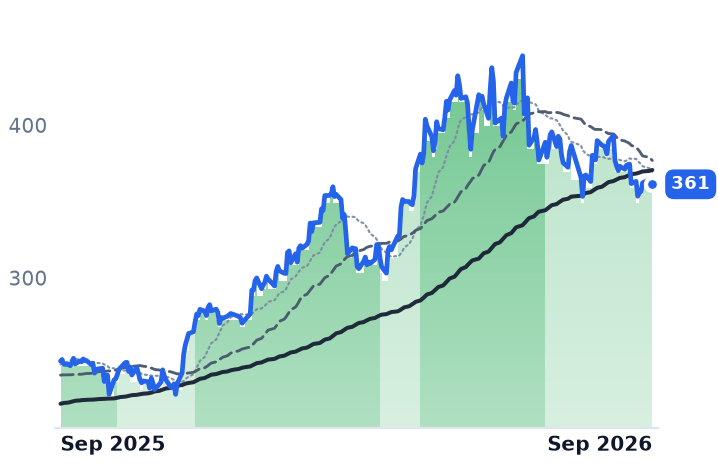
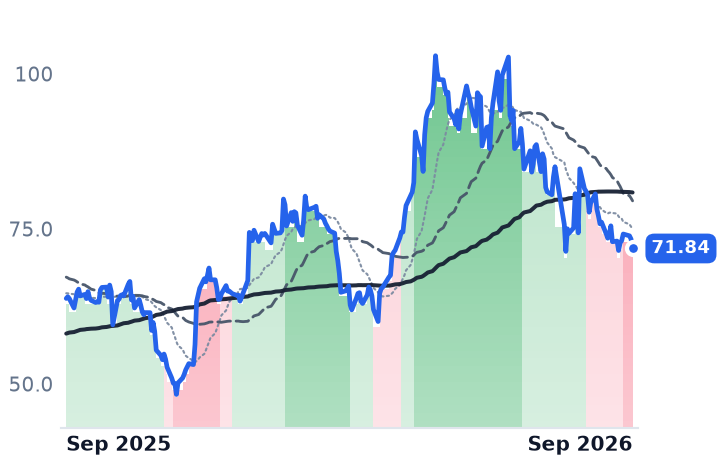
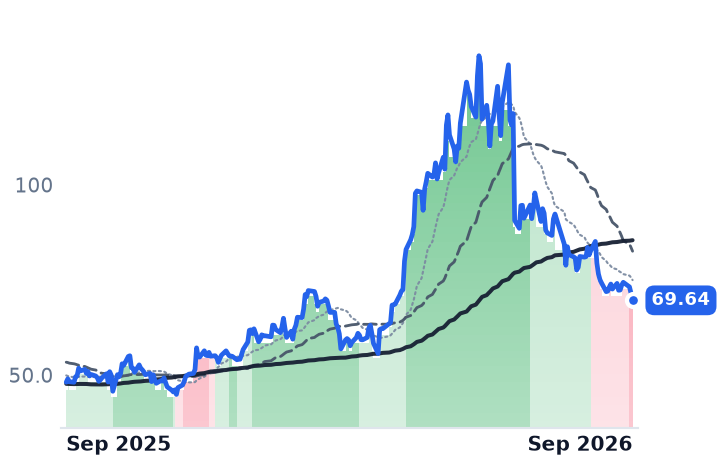
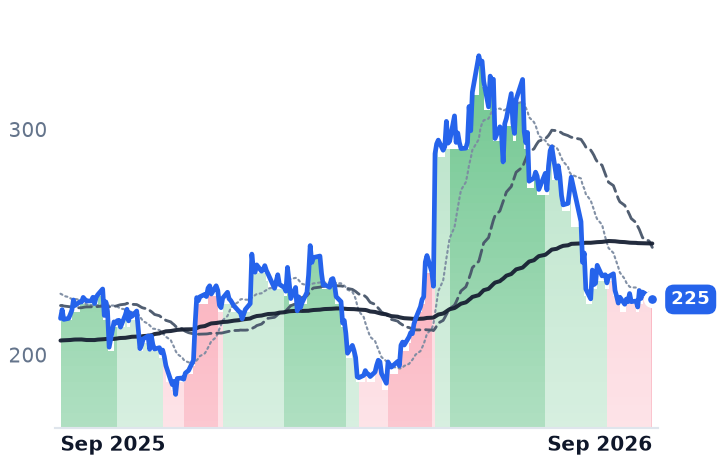
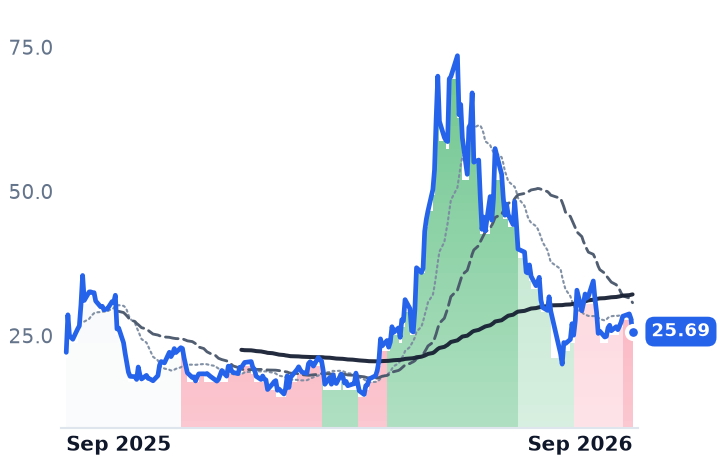
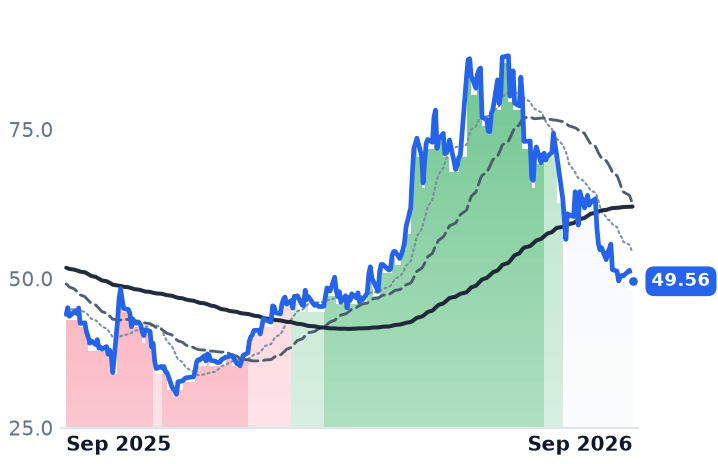
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | −15.0% | +40.1% |
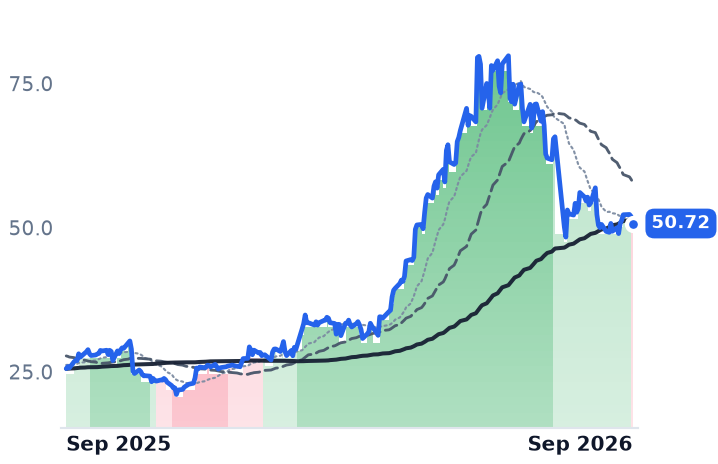
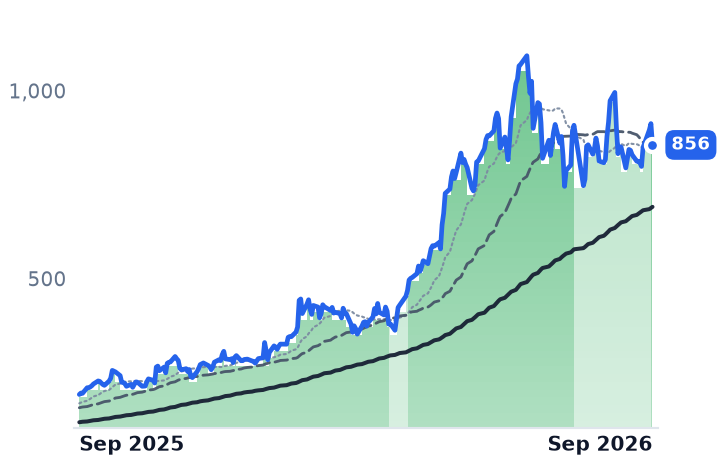
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −16.0% | +99.6% |
| Compared against · context, not the story | |||||
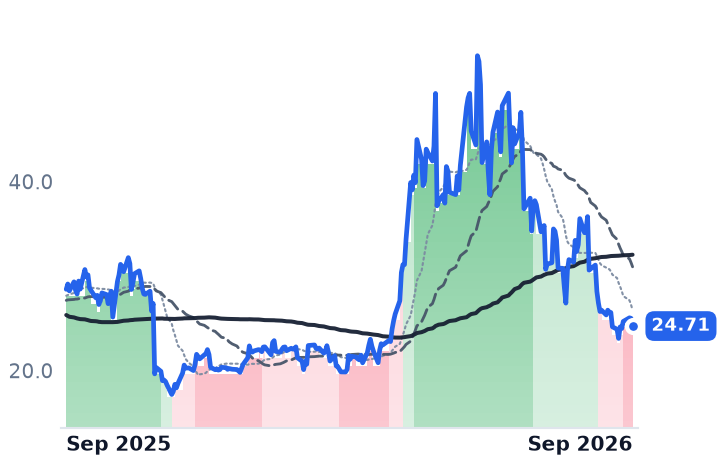
VICR | Vicor | Other | 🟢 Cont. Bull | −15.7% | +257.0% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | −7.0% | +44.9% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | −6.5% | +47.1% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −11.4% | +12.6% |
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | −14.1% | +44.7% |
NXPI | NXP Semiconductors | Analog & Mixed-Signal | ⚠️ Emerging Bear | −4.6% | +3.9% |
WOLF | Wolfspeed | Discrete & Power | 🔴 Cont. Bear | −16.0% | +16.3% |
AOSL | Alpha and Omega Semiconductor | Analog & Mixed-Signal | 🔴 Cont. Bear | −29.1% | −13.6% |
POWI | Power Integrations | Analog & Mixed-Signal | 🌱 Emerging Bull | −21.4% | +12.6% |
STM | STMicroelectronics | Analog & Mixed-Signal | 🟢 Cont. Bull | −7.2% | +98.5% |
VSH | Vishay Intertechnology | Discrete & Power | 🟢 Cont. Bull | −7.8% | +107.8% |
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −11.2% | +81.8% |
AVGO | Broadcom | Semiconductor Subsystems | 🟢 Cont. Bull | −13.8% | −1.0% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +0.2% | +22.8% |
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +14.5% | +597.9% |
SNDK | Sandisk | Specialty Manufacturing & Components | 🟢 Cont. Bull | +33.3% | +2175.5% |
SMCI | Super Micro Computer | Server & Infrastructure Systems | 🌱 Emerging Bull | +21.4% | −13.0% |
MRVL | Marvell Technology | Specialty Semiconductors | 🟢 Cont. Bull | +9.2% | +241.0% |
STX | Seagate Technology | Data Storage Devices | 🟢 Cont. Bull | +4.7% | +346.7% |
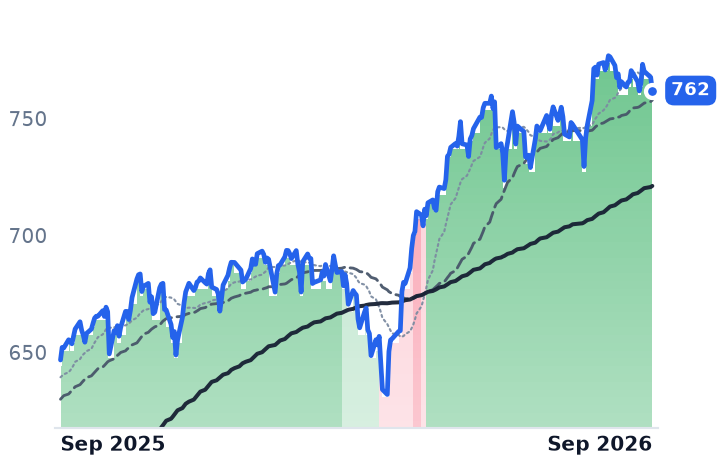
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.7% | +17.2% |
12-month price & trend
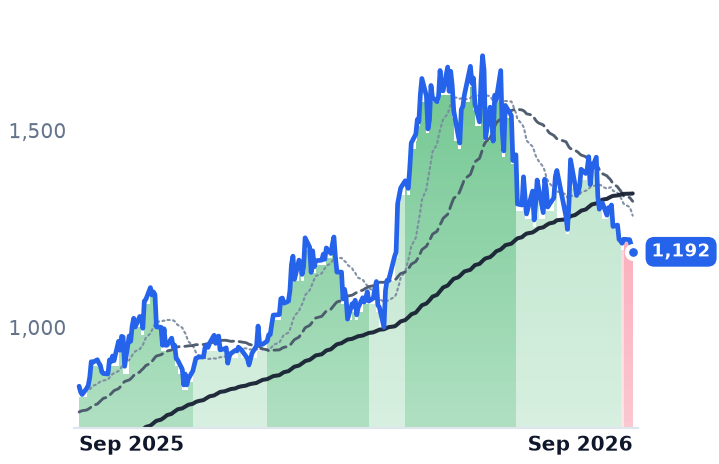
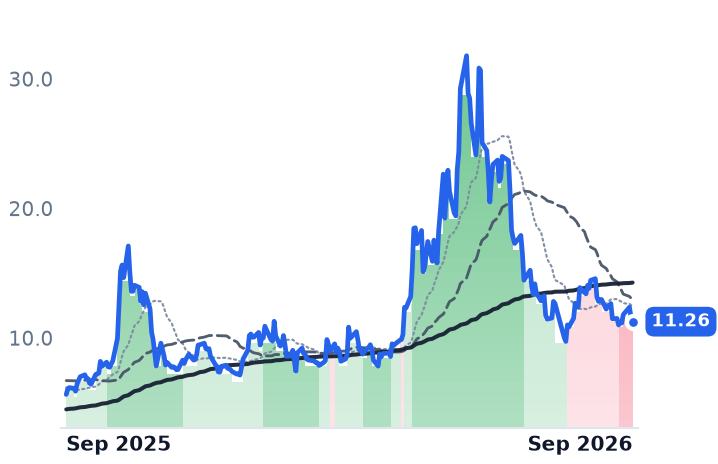
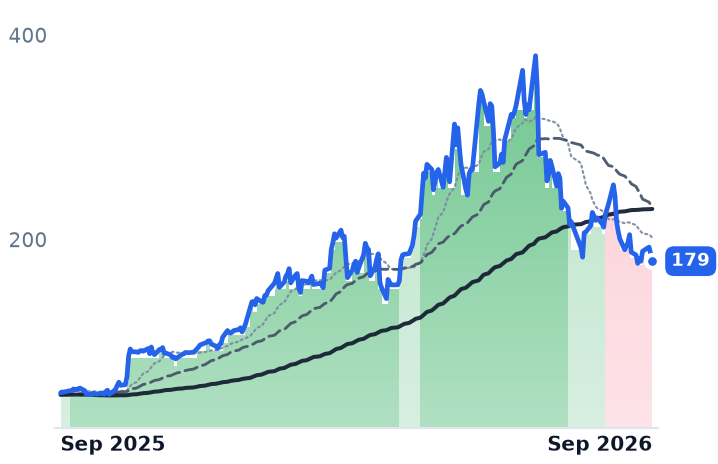
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $58.3B | 72.3x | 43.3x | 17.8x | 14.0x | 32.3x | 25.4x | 56.6x | 1.0% |
NVTS | $2.9B | n/m | — | 79.7x | 61.0x | — | — | n/m | -2.3% |
VICR | $8.8B | 60.6x | 56.3x | 18.5x | 14.5x | 32.6x | 25.7x | 65.2x | 0.6% |
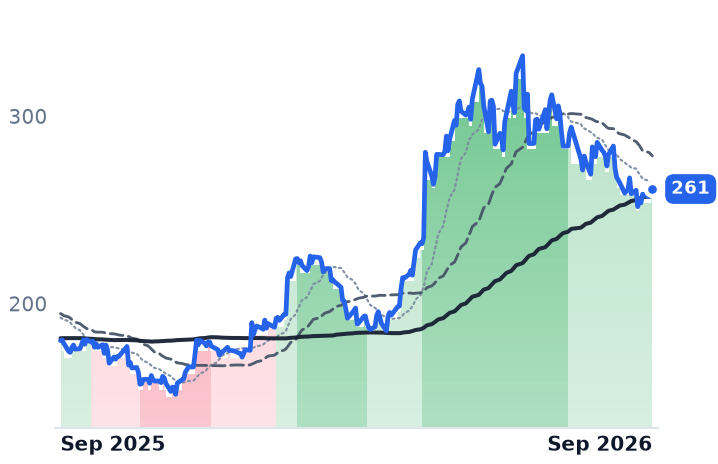
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $258.4B | 42.8x | 33.4x | 13.3x | 11.8x | 22.8x | 20.2x | 29.5x | 2.1% |
ADI | $181.1B | 43.9x | 28.9x | 13.0x | 12.0x | 19.8x | 18.2x | 28.8x | 2.7% |
MCHP | $40.2B | 102.6x | 20.3x | 7.8x | 6.3x | 13.0x | 10.4x | 26.9x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $32.5B | 52.8x | 26.1x | 5.2x | 5.0x | 14.0x | 13.2x | 26.4x | 5.5% |
NXPI | $56.9B | 19.1x | 15.0x | 4.3x | 4.0x | 7.7x | 7.1x | 13.2x | 5.2% |
WOLF | $1.4B | n/m | — | 2.1x | 2.2x | — | — | n/m | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AOSL | $929.9M | n/m | — | 1.4x | 1.3x | 6.1x | 5.9x | n/m | -1.8% |
POWI | $3.5B | 136.5x | 44.7x | 7.7x | 7.2x | 14.4x | 13.5x | 84.1x | 2.3% |
STM | $49.8B | 107.2x | 41.7x | 3.7x | 3.5x | 10.9x | 10.1x | 22.5x | 0.8% |
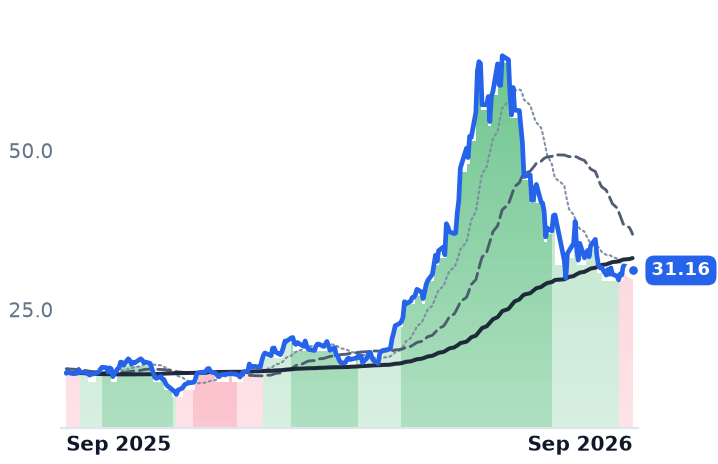
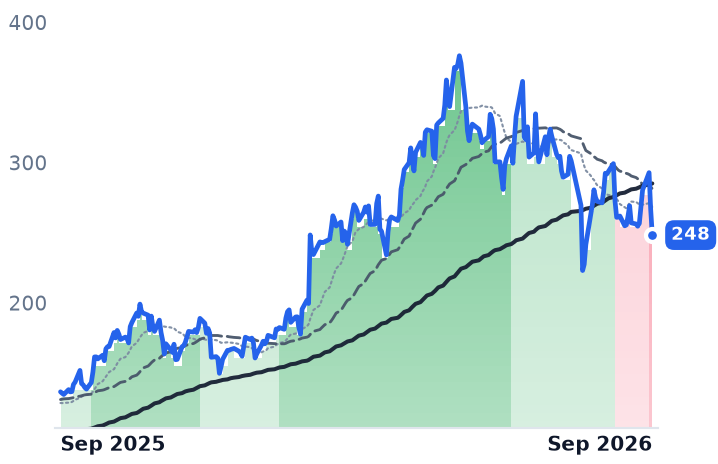
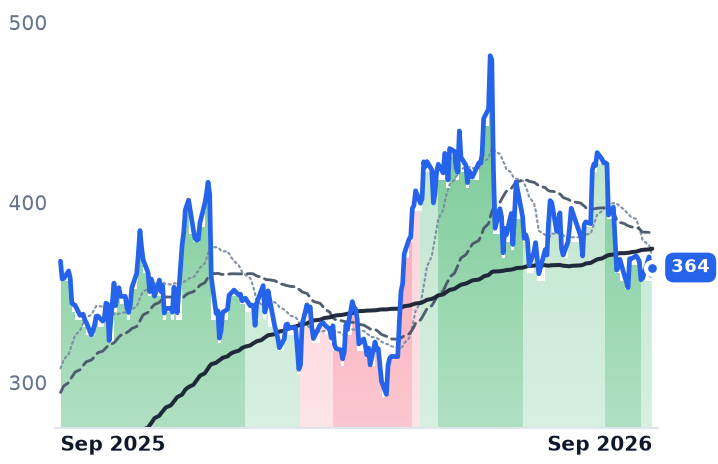
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VSH | $4.3B | 118.1x | 36.1x | 1.0x | 1.2x | 5.0x | 5.6x | 11.3x | -0.2% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
AVGO | $1.7T | 44.4x | 30.8x | 19.1x | 16.1x | 28.2x | 23.8x | 33.3x | 2.3% |
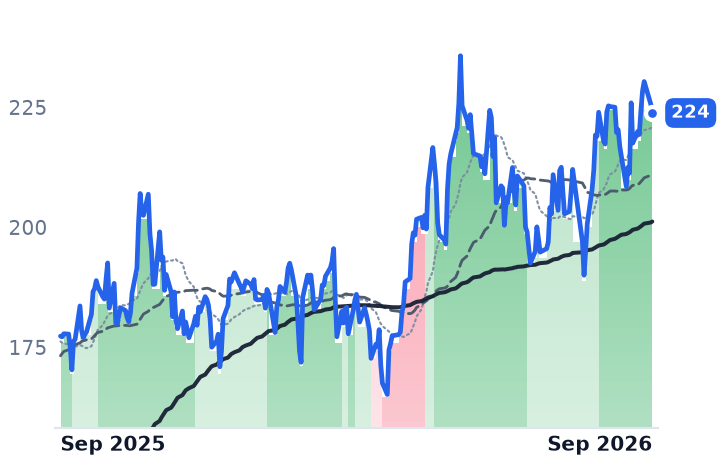
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
SNDK | $232.3B | 20.2x | 7.5x | 11.5x | 4.8x | 16.1x | 6.7x | 17.4x | 4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMCI | $24.1B | 10.2x | 8.6x | 0.6x | 0.4x | 5.7x | 3.3x | 7.7x | -28.9% |
MRVL | $230.5B | 92.0x | 65.3x | 26.4x | 20.1x | 52.2x | 39.7x | 50.5x | 0.7% |
STX | $178.4B | 73.9x | 53.5x | 16.2x | 14.8x | 39.0x | 35.7x | 53.6x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
TXN | Revenue | +23.8% | +14.0% | +10.8% |
| EPS | +55.0% | +20.5% | +18.4% | |
ADI | Revenue | +37.7% | +21.9% | +11.1% |
| EPS | +65.6% | +29.0% | +17.0% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
ON | Revenue | +9.2% | +12.9% | +13.5% |
| EPS | +37.1% | +41.7% | +31.7% | |
NXPI | Revenue | +16.7% | +11.5% | +8.3% |
| EPS | +28.0% | +20.5% | +15.3% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
AOSL | Revenue | −1.9% | +4.4% | +18.5% |
| EPS | −479.7% | −9.8% | −332.6% | |
POWI | Revenue | +7.7% | +14.2% | +20.8% |
| EPS | +14.8% | +34.8% | +43.0% | |
STM | Revenue | +22.4% | +18.7% | +13.2% |
| EPS | +104.2% | +98.3% | +45.6% | |
VSH | Revenue | +21.1% | +15.8% | +11.4% |
| EPS | −2768.7% | +110.0% | +53.5% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
AVGO | Revenue | +67.0% | +64.8% | +56.9% |
| EPS | +72.1% | +66.0% | +55.4% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
SNDK | Revenue | +174.4% | +143.0% | +18.2% |
| EPS | +2369.0% | +214.5% | +22.1% | |
SMCI | Revenue | +77.7% | +69.8% | +17.7% |
| EPS | +33.5% | +54.8% | +23.3% | |
MRVL | Revenue | +42.4% | +40.1% | +44.0% |
| EPS | +82.6% | +41.9% | +51.9% | |
STX | Revenue | +32.7% | +35.9% | +24.9% |
| EPS | +86.9% | +77.9% | +48.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Navitas Semiconductor — a 190-person fabless designer of gallium-nitride and silicon-carbide power chips in Torrance, California — spent the summer telling investors when the architecture it is built for arrives. On its 27 July call, management dated gallium-nitride content in graphics-processor voltage conversion to mid-to-late 2027, accelerating into 2028. At Citi's Global TMT conference on 8 September, the same step — native 800-volt systems, with direct-current conversion moved inside the compute tray — was dated to early 2028.
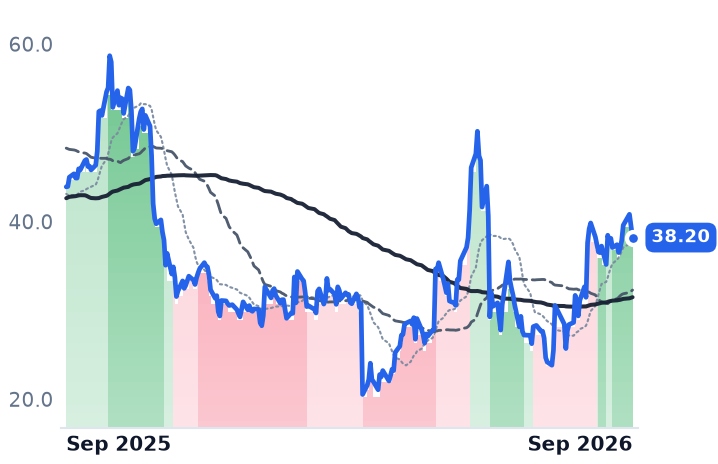
Six weeks, roughly two quarters of slippage on the one line item the equity is priced against. Navitas's June quarter brought in $10.5m of revenue, down 27.3% year on year, at a reported gross margin of minus 9.5% and an operating loss of $27.2m. Four quarters through June produced roughly minus $0.6m of cumulative gross profit, so there is no price-to-earnings or price-to-gross-profit figure to compute; the shares change hands at 79.7 times trailing sales. What the company does have is $557m in cash and no debt, after raising $373m during the quarter at $21.89 a share — 95% above Thursday's $11.26 close. Diluted share count is up 18.5% in a year. Until the racks ship, this is a claim on runway.
"It would have happened without NVIDIA, it's happening much sooner due to their influence," chief executive Chris Allexandre said of the 800-volt shift at the Citi conference, where he also called the pivot away from mobile and consumer chargers "pretty much done." Nvidia's own published schedule puts 800-volt direct-current architecture into full-scale production alongside its Kyber rack systems in 2027, and names ten silicon providers for it — Analog Devices, Infineon, Innoscience, MPS, Navitas, onsemi, Renesas, ROHM, STMicroelectronics and Texas Instruments. A place on a list is not a socket.
The supplier that already gets paid
Monolithic Power Systems, which designs the voltage-conversion chips and modules that sit under server processors and accelerators, is on that same list and is not waiting for it. June-quarter revenue was $980.6m, up 47.6% — the fourth straight quarter of accelerating growth. Enterprise data revenue reached $380.6m, up 164.3%, and the company lifted its full-year growth floor for that segment from 85% to 130%. Gross margin held at 55.2%, inside the band it has occupied for eight quarters, and operating margin widened to 31.0% from 24.8%. Founder and chief executive Michael Hsing told investors on the 30 July call that the company "relies on its own silicon carbide devices for the 800-volt solution" — its answer to the transition is internal, and sampling rather than shipping.
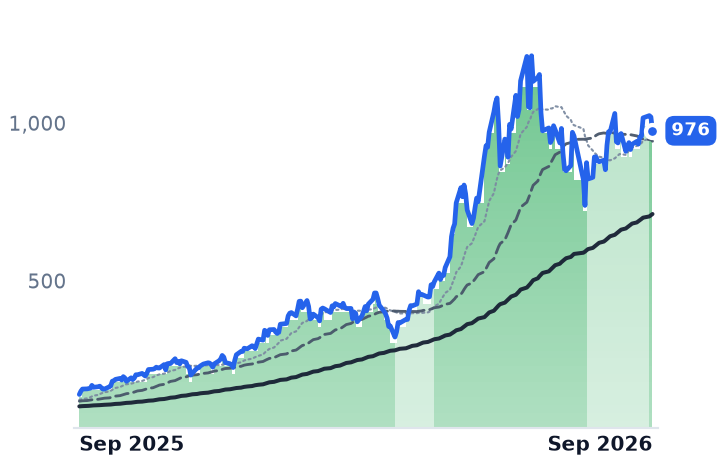
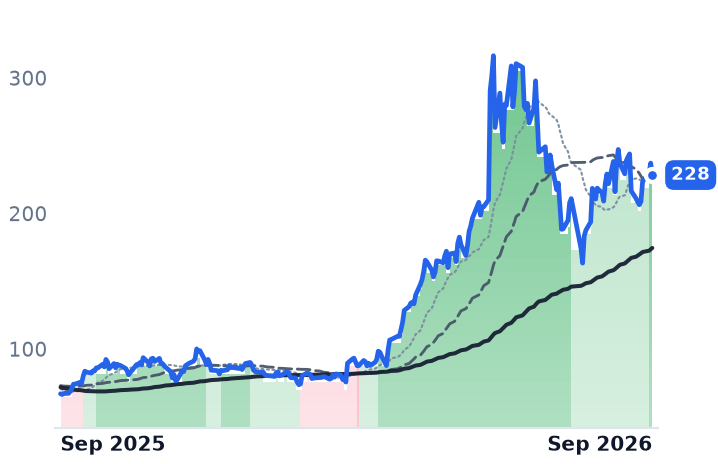
The shares have fallen 29.5% from their 3 June high. Measured against gross profit, Monolithic Power now trades at 32.3 times trailing and 25.4 times forward, against 49.8 times trailing in May. That forward figure is level with Vicor — the modular converter maker that lost Nvidia's H100 power socket to Monolithic years ago and now collects royalties on the patents — whose revenue grew 1.6% last quarter.
What the selling was actually sorting for
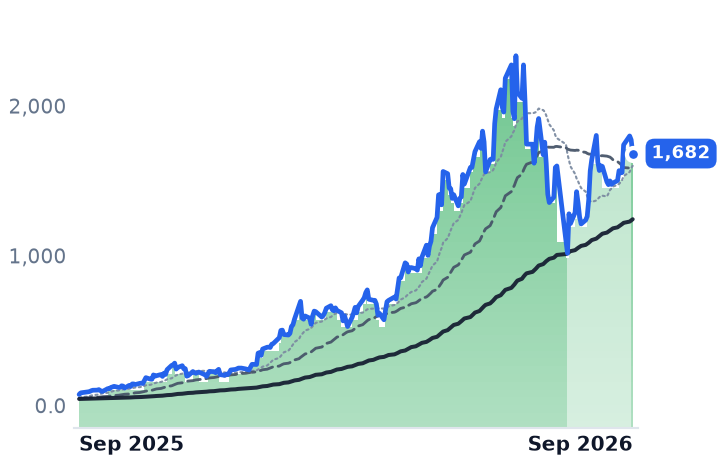
Over thirty days the power and analog complex fell in order of valuation, not end market: Alpha & Omega Semiconductor down 29.1%, Power Integrations 21.4%, Navitas 16.0%, Monolithic Power 15.0%, against Texas Instruments down 7.0% and Analog Devices 6.5%. Memory went the other way — Micron up 14.5%, SanDisk 33.3% — as capital moved toward scarcity that exists today. The backdrop is the same discount-rate repricing the market has been trading all month, with the 10-year Treasury yield near 4.90%. Nvidia itself has now fallen 5.4% in four sessions, which removes the tidy reading that the customer was rising while its suppliers sank.
So: Navitas's de-rating its own numbers explain, and its own calendar just reinforced. Monolithic Power's they do not — a business compounding at 47.6% has been marked to the price of one growing at 1.6%. The threat to Monolithic that would justify it is competitive rather than cyclical, and it is visible: Analog Devices paid $1.5bn for Empower Semiconductor, whose vertical power regulators sit in exactly the position under the accelerator that Monolithic is priced to own.
Nvidia's 800-volt racks reach full production next year on Nvidia's schedule. Navitas now expects its in-tray silicon a year after that. Every quarter that gap widens is a quarter in which the cash pile, not the design wins, does the work.