

Icahn Enterprises' Funds Are Short the Refining Margin CVR Energy Earns for It
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
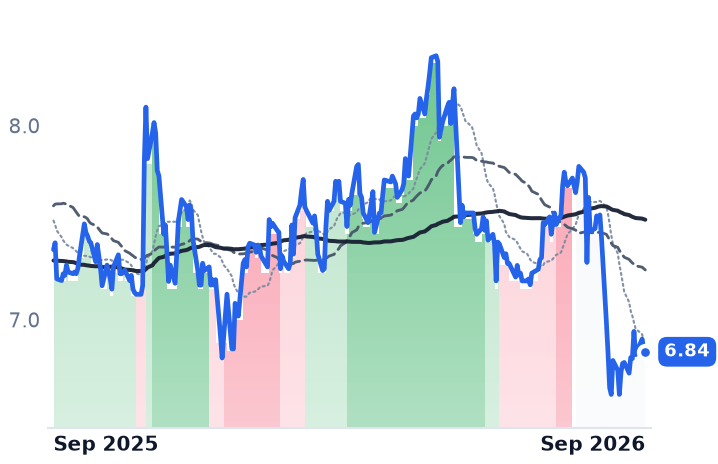
Icahn Enterprises owns two-thirds of CVR Energy and its investment funds hedge that exposure — so the best refining margins on record arrived at the parent as a loss. The funds returned -10.9% in the June quarter including refining hedges, and indicative net asset value fell 23% in three months to $2.602bn, with the CVR mark and broad-market hedges doing most of the damage.
CVR's own quarter was the mirror image: adjusted EBITDA of $209m, with the fertilizer business out-earning the refinery. The parent's units still trade at a large premium to the net asset value the company itself publishes, and the unit count has grown by roughly a fifth in a year to help fund a distribution the business does not cover. The refining recovery does not reach the parent undiluted; the hedge comes with it.
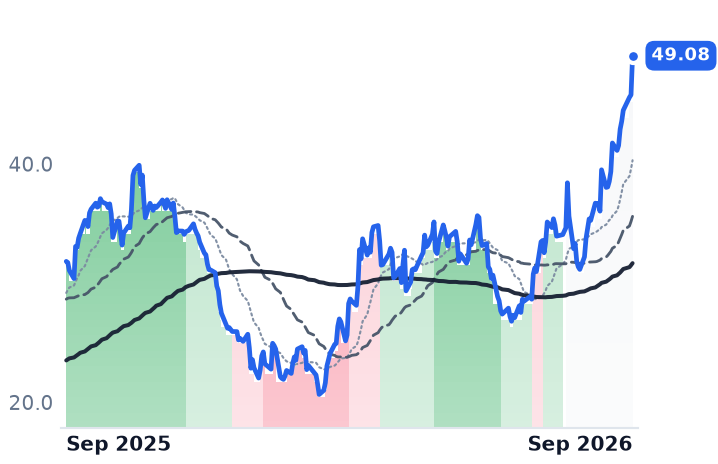
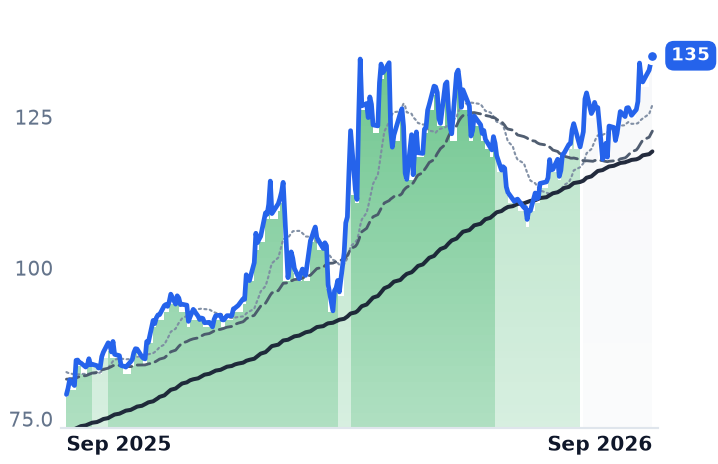
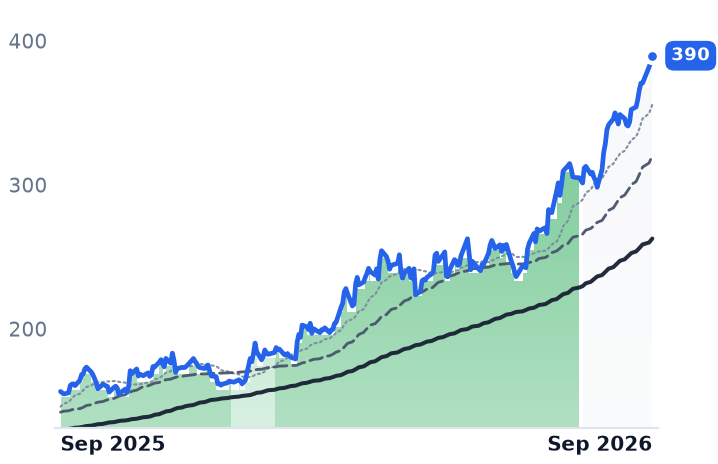
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
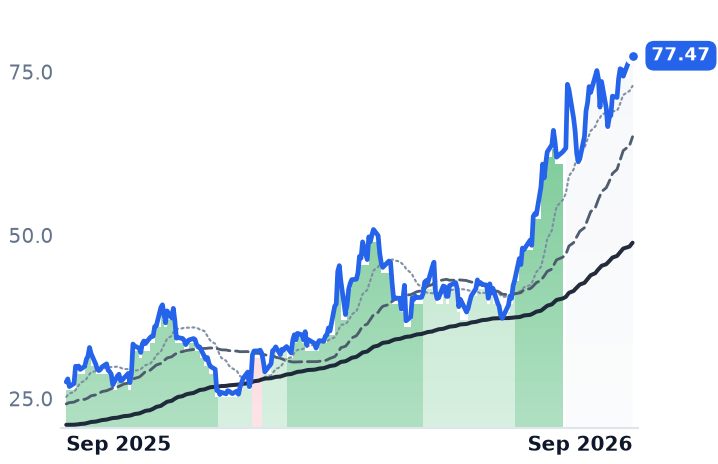
IEP | Icahn Enterprises | Real Estate & Agriculture | ⚠️ Emerging Bear | −9.3% | −7.1% |
CVI | CVR Energy | Specialty Refining | ⚠️ Emerging Bear | +45.4% | +54.2% |
| Compared against · context, not the story | |||||
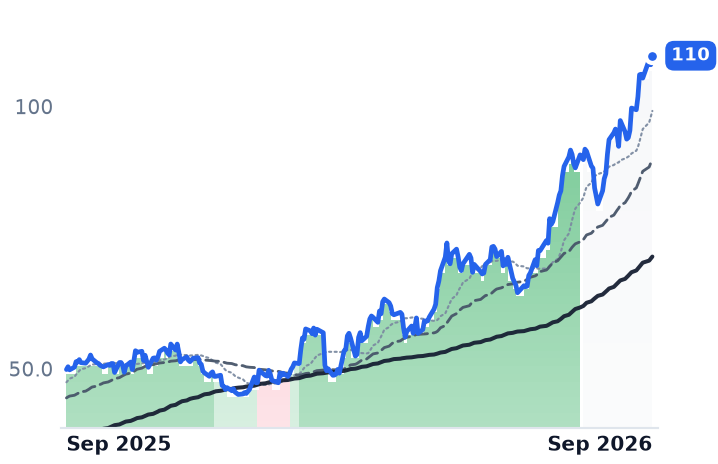
UAN | CVR Partners | Nitrogen Fertilizers | 🟢 Cont. Bull | +13.9% | +70.9% |
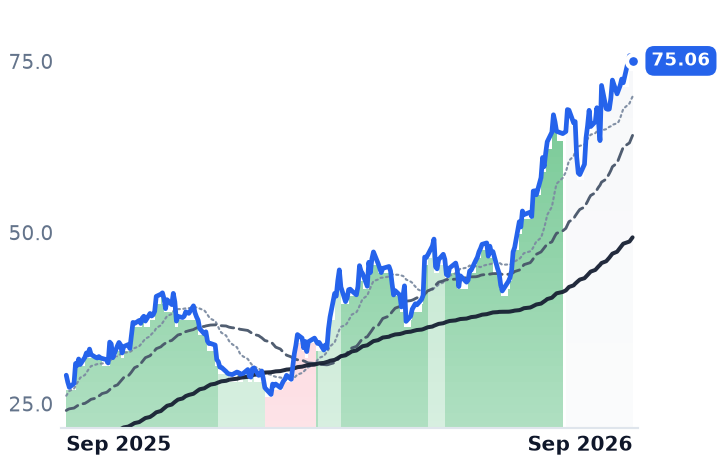
VLO | Valero Energy | Integrated Refiners | 🟢 Cont. Bull | +20.8% | +148.9% |
PBF | PBF Energy | Integrated Refiners | 🟢 Cont. Bull | +12.3% | +181.1% |
DINO | HF Sinclair | Integrated Refiners | 🟢 Cont. Bull | +27.2% | +120.0% |
DK | Delek US | Integrated Refiners | 🟢 Cont. Bull | +17.6% | +157.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IEP | $4.6B | n/m | — | 0.4x | 0.5x | 5.2x | 6.4x | 24.7x | -5.3% |
CVI | $4.9B | 70.4x | 128.3x | 0.6x | 0.6x | 17.0x | 16.5x | 8.0x | 7.1% |
UAN | $1.4B | 11.3x | — | 2.1x | — | 8.4x | — | 6.8x | 8.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VLO | $98.4B | 14.2x | 9.1x | 0.7x | 0.7x | 6.5x | 6.0x | 7.7x | 10.3% |
PBF | $8.5B | 6.3x | 5.3x | 0.2x | 0.2x | 5.5x | 5.2x | 4.8x | 8.7% |
DINO | $16.7B | 8.9x | 6.9x | 0.5x | 0.5x | 4.2x | 3.9x | 4.8x | 15.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DK | $4.0B | 17.9x | 6.7x | 0.3x | 0.3x | 3.9x | 3.7x | 5.3x | 17.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IEP | Revenue | −8.0% | +2.2% | — |
| EPS | +14.3% | −237.5% | — | |
CVI | Revenue | +22.8% | −12.0% | −2.6% |
| EPS | −130.1% | +477.9% | −20.6% | |
VLO | Revenue | +20.4% | −13.1% | −10.9% |
| EPS | +275.0% | −29.2% | −26.9% | |
PBF | Revenue | +24.2% | −7.2% | +1.4% |
| EPS | −390.5% | −29.5% | −47.1% | |
DINO | Revenue | +25.8% | −9.9% | −1.9% |
| EPS | +220.9% | −32.7% | −25.1% | |
DK | Revenue | +18.7% | −7.9% | +0.6% |
| EPS | +142.3% | −56.8% | −101.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Icahn Enterprises' investment funds spent the June quarter positioned against the business that dominates its own income statement. The funds finished June net short by the equivalent of 30% of notional exposure once refining hedges are counted, and net long 23% once those hedges are stripped out — the short book is specifically a hedge against refining, not a general view on equities. The refining exposure being hedged is CVR Energy, the coking refiner at Coffeyville, Kansas and Wynnewood, Oklahoma that also makes nitrogen fertilizer, and of which Icahn Enterprises owns 66.3% after a January 2025 tender at $18.25 a share drew almost no takers.
So when US product margins went to records this summer, the parent did not collect. CVR closed at $49.08 on 10 September, up 52.4% in a month; Icahn Enterprises' units fell over the same stretch, though most of the visible drop was the $0.50 distribution that went ex on 17 August — adjusted for it, the month's move is roughly -1.8%. The stake in CVR is now worth about $3.2bn against a $4.62bn market value for the whole holding company. Whether the rest of the structure adds or subtracts is the question, and the answer is disclosed quarterly.
What the refinery actually earned
CVR's June quarter produced $209m of adjusted EBITDA and $0.34 of adjusted earnings per share, against a reported loss of three cents once a $73m unfavorable mark on its renewable-fuel obligation and $81m of realized crack-spread hedging losses are counted. Petroleum segment adjusted EBITDA rose 179% to $106m, on Group 3 two-to-one-to-one crack spreads of $44.91 a barrel against $24.02 a year earlier, with throughput of 213,000 barrels a day at 98% utilization. Fertilizer adjusted EBITDA rose 60% to $107m — slightly more than refining — on a spread between cheap US natural gas and scarce global nitrogen, with CVR Partners' realized ammonia gate price up 33% to $791 a ton while American producers pay under $3 per million British thermal units for gas against roughly $19 in Europe.
The drag on refining is compliance. CVR booked $216m of Renewable Identification Number expense in the quarter, $11.16 a barrel, cutting its capture of the posted margin by about a quarter. "RIN prices are adding nearly $0.40 a gallon to the price of gasoline in the U.S., and RFS compliance costs are more than twice all the other combined operating costs for many refineries," chief executive Dane Neumann told investors on the July 30 call. Wynnewood's pending 100% small-refinery exemption would lift consolidated capture by roughly nine percent; the precedent is the August 2025 decision that cut CVR's 2020-2024 obligation by more than 424 million RINs, booked as a roughly $488m gain. On August 31 the Environmental Protection Agency decided 34 petitions for the 2025 compliance year, granting 18 full exemptions and pushing the compliance deadline to October 1 — a dated regulatory event sitting inside CVR's month.
The margin itself has a cause outside anyone's control: roughly 40% of Russia's refining capacity is offline after drone strikes, a shock to product-making rather than to crude. The forward curve treats it as temporary — the December 2027 strip sits more than 35% below the September crack.
The parent's meters are not sales
Icahn Enterprises' consolidated revenue rose 27.4% last quarter, and it is almost entirely CVR's fuel and fertilizer sales; the line tells a unitholder nothing. The honest meter is the indicative net asset value the company publishes, $2.602bn at June 30, down $765m in three months. The breakdown: $435m off the CVR position and $243m off the funds on broad-market hedge losses, offset by $97m for the pending $700m Pep Boys sale.
Against 669m diluted units — up 22.75% in a year — that NAV is about $3.89 a unit, against $6.835 on September 10, a premium near 76%, corroborated by 2.54 times book on a balance sheet largely marked to market. The board declared the same $0.50 quarterly distribution on August 3, about $335m on that count, in a quarter when adjusted EBITDA attributable to Icahn Enterprises was minus $134m. What makes it survivable is ownership: Carl Icahn and affiliates held roughly 87% of the units at June 30 and take the payout largely in more units, so the cash out the door is far below the declared figure — and the unit count grows regardless. Energy contributed $102m of attributable EBITDA last quarter; CVR's ten-cent dividend sent about $7m of actual cash upstairs.
The verdict
CVR's advance is largely earned. At eight times trailing enterprise value to EBITDA and a 7.1% trailing free cash flow yield, with $737m of cash, it remains the laggard of a peer group that re-rated 114% to 175% over twelve months, PBF Energy at the top and CVR up 53.8%. What the business has not established is duration: trailing EBITDA is flattered by last year's one-off RIN gain, the forward crack curve is far lower, and the sell side carries four sell ratings, no buys and a $31.40 average target, 36% below spot.
Icahn Enterprises is the opposite case. Its moving-average trend rolled over in June while CVR made a new 52-week high, and the de-rating is doing rational work rather than opening a gap — the units sit well above the company's own published value, after five consecutive years of net losses. The structural point is the one to carry forward: the funds' hedge deliberately neutralizes much of the refining windfall in both directions, so a crack reversal that hurts the CVR mark should help the short book, and a further rally will keep doing what it did last quarter.
The EPA remains delinquent on Wynnewood's 2020 exemption petition, with the 2025 compliance deadline now pushed to October 1. A grant would widen the refinery's capture rate; whether any of it reaches Icahn Enterprises' unitholders depends on a hedge book disclosed once a quarter, in aggregate.