

SolarEdge Set a 2029 Revenue Target of $2.4bn on a Data-Center Line With No Orders
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
SolarEdge spent its investor day selling a business it does not yet have a customer for: a joint white paper with Nvidia, a medium-voltage conversion stage running under load, and no purchase order from any data-center operator. The shares fell while it presented.
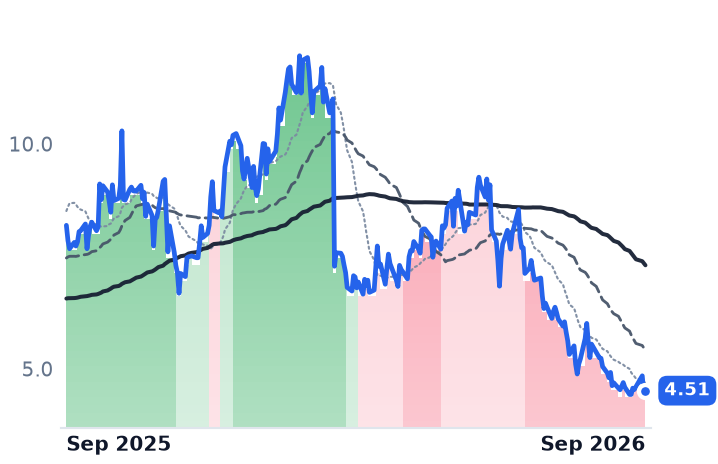
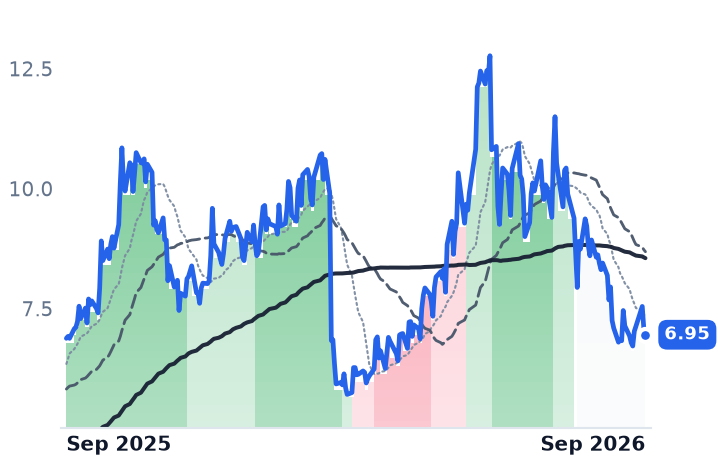
Underneath, the two listed inverter makers are moving in opposite directions. SolarEdge's June-quarter revenue rose 19.6% to $346.2m with gross margin at 27.5%, its sixth straight quarter of expansion; Enphase's revenue fell by the same 19.6%, its third consecutive decline of about a fifth. Both now trade near 7.6 times trailing gross profit — the market pricing the shrinking business and the growing one identically, and paying both for revenue that does not arrive until 2028.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SEDG | SolarEdge Technologies | Inverters & Power Electronics | ⚠️ Emerging Bear | +8.5% | +21.9% |
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −11.3% | +0.2% |
| Compared against · context, not the story | |||||
RUN | Sunrun | Residential Solar Installers | ⚠️ Emerging Bear | −13.8% | −46.7% |
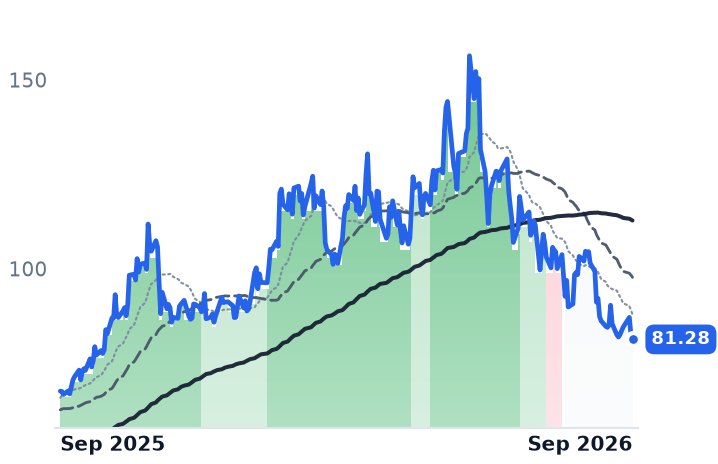
FSLR | First Solar | Solar Module Manufacturers | 🟢 Cont. Bull | −13.2% | +1.9% |
ARRY | Array Technologies | Solar Tracking Systems | ⚠️ Emerging Bear | −14.8% | −44.9% |
SHLS | Shoals Technologies | Solar System Components | 🟢 Cont. Bull | −19.3% | +1.1% |
NXT | Nextpower | Other | 🟢 Cont. Bull | −22.3% | +20.3% |
CSIQ | Canadian Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −17.7% | +20.3% |
FLNC | Fluence Energy | Energy Storage Systems | ⚠️ Emerging Bear | −25.4% | +44.7% |
STEM | Stem | Renewable Utilities | ⚠️ Emerging Bear | −10.9% | −61.2% |
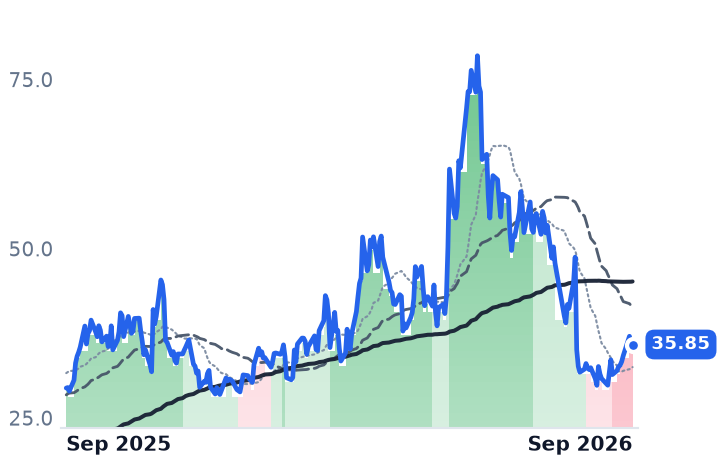
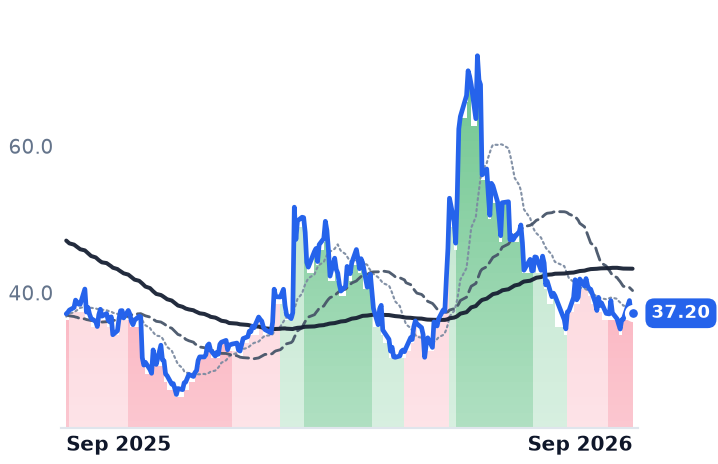
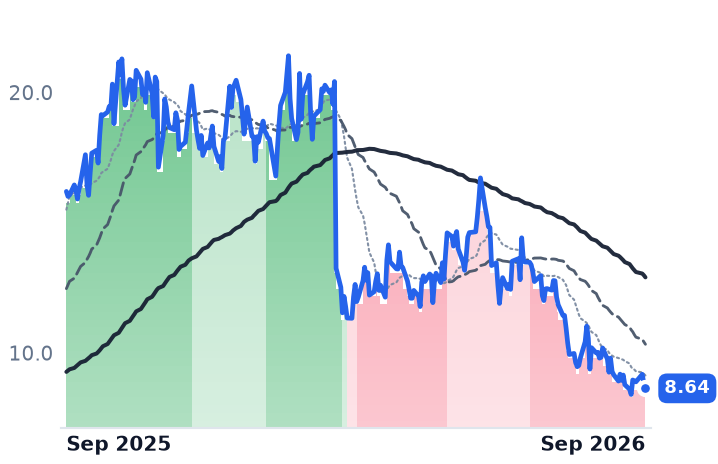
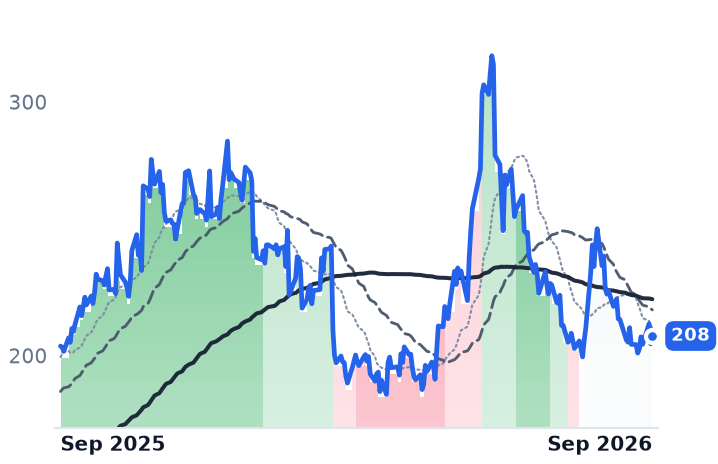
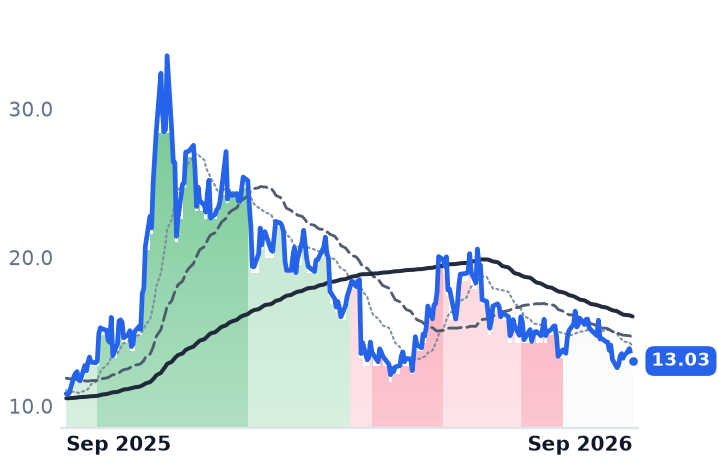
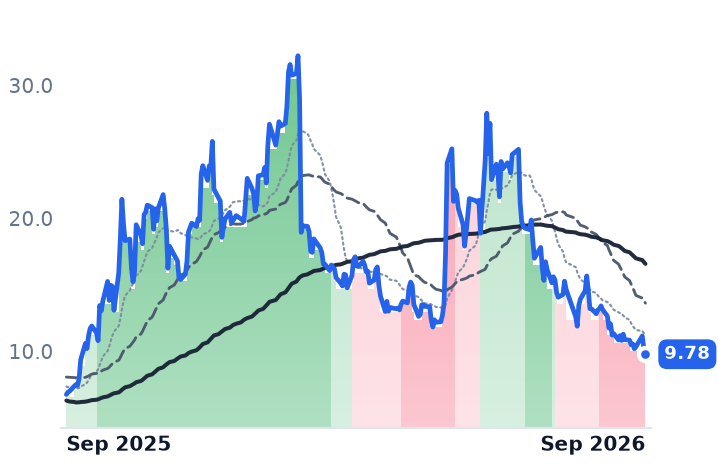
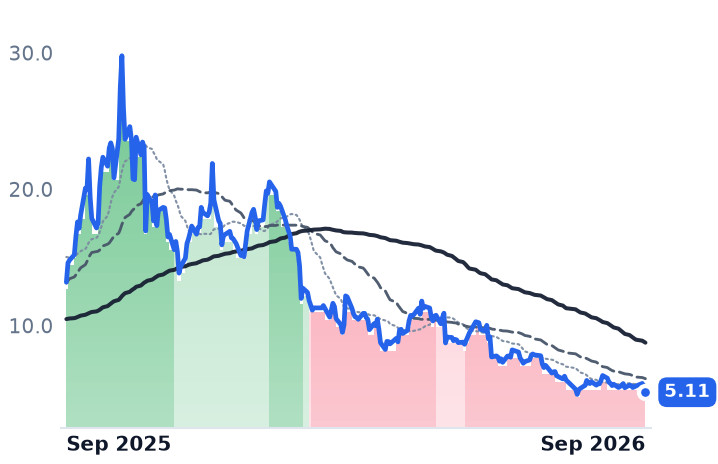
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SEDG | $2.2B | n/m | — | 1.7x | 1.7x | 7.6x | 7.6x | n/m | 4.0% |
ENPH | $4.9B | 36.1x | 18.4x | 3.7x | 4.1x | 7.8x | 8.7x | 27.9x | 3.1% |
RUN | $2.1B | 5.2x | 7.0x | 0.6x | 0.7x | 1.8x | 2.0x | 23.4x | -64.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.0B | 12.6x | 11.8x | 4.1x | 4.4x | 9.3x | 10.0x | 8.4x | 6.8% |
ARRY | $807.6M | n/m | 7.2x | 0.7x | 0.6x | 2.8x | 2.3x | 301.0x | 12.1% |
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
CSIQ | $1.2B | n/m | — | 0.2x | 0.2x | 1.2x | 1.1x | 24.7x | -136.5% |
FLNC | $2.1B | n/m | — | 0.8x | 0.7x | 8.7x | 7.5x | n/m | -6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STEM | $49.4M | n/m | — | 0.3x | 0.3x | 0.9x | 0.9x | n/m | 11.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SEDG | Revenue | +12.0% | +11.1% | +11.4% |
| EPS | −86.2% | −370.0% | +91.7% | |
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +14.0% | +18.9% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
FSLR | Revenue | −1.7% | +17.1% | +11.8% |
| EPS | +19.5% | +34.3% | +25.9% | |
ARRY | Revenue | +14.9% | +9.8% | +5.6% |
| EPS | +9.8% | +23.8% | +13.9% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
CSIQ | Revenue | +9.9% | +17.4% | +6.5% |
| EPS | −38.6% | −236.1% | +107.9% | |
FLNC | Revenue | +17.0% | +32.7% | +20.1% |
| EPS | +49.7% | −139.6% | +159.5% | |
STEM | Revenue | +0.1% | +17.5% | +22.8% |
| EPS | +31.7% | −13.6% | −43.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
SolarEdge gathered analysts on 10 September to describe a business it does not yet have a customer for. The Israeli maker of DC-optimized inverters and power optimizers for rooftop solar told investors it targets $2.4bn of revenue by 2029, at a 35% gross margin and $360m of operating profit, and said the medium-voltage-to-800-volt conversion stage of its AI data-center powertrain is now running under load. It also published a white paper with Nvidia on 800-volt direct-current protection and grounding — and acknowledged it holds no purchase order or agreement with a hyperscaler or neocloud operator. The stock fell during the presentation.
That is the second data-center announcement from this pair in three days. On 8 September Enphase, which sells module-level microinverters and AC batteries into solar distributors and installers, said its solid-state transformer modules had entered production in Texas. Both roadmaps land in the same place: a working system late in 2026, pilots in 2027, volume shipments in 2028. Enphase's own credit treatment for the product is still being finalized. Whatever either company earns from AI power, it earns after two more years of the business it actually has.
The business it actually has
That business has split in two. SolarEdge's June quarter brought revenue of $346.2m, up 19.6% year on year, with gross margin of 27.5% against 11.1% a year earlier and a first non-GAAP operating profit — $10.2m — in nearly three years, plus $3.1m of free cash flow against $601.6m of cash and securities. Europe carried it, rising 36% sequentially to $154.4m; US residential slipped 2% on slow tax-equity funding. The company is still GAAP loss-making, at -$30.8m, and $13.3m of tariff refunds flattered the margin.
Enphase went the other way. Revenue of $291.9m was down 19.6%, the third consecutive drop of roughly a fifth, and US sell-through — systems actually installed — fell 34% year on year. Consensus has revenue falling 19.1% this year and earnings per share 28.8%, and does not restore Enphase to its 2025 revenue of $1.47bn until about 2029. The June quarter included $84.3m of safe-harbour shipments to third-party-ownership partners, "some of whom are supported by strong balance sheets," chief executive Badri Kothandaraman said on the 28 July call, where he also guided to modest under-shipment in the third quarter to work down microinverter channel inventory.
The hole is statutory. The residential 25D tax credit expired at the end of 2025, leaving third-party-owned leases claiming 48E — where the developer picks the hardware — as the federal route for homeowners, and SEIA and Wood Mackenzie see US residential installations falling roughly 18-21% this year. US installations were already down 27% in the first quarter. From 4 December, a Section 232 proclamation sets minimum import prices of $0.38 a watt on modules, raising the cost of the systems inverters attach to.
What the market did with it
Both stocks roughly doubled between 12 May and 2 June on the data-center narrative — Enphase up 93%, SolarEdge 94% — then surrendered it, down 48.6% and 54.3% from those peaks. SolarEdge lost 28.1% in the 5 August session after guiding third-quarter revenue to $310-340m against consensus near $370m. Every distributed-solar name fell over three months: Fluence 54.7%, Sunrun 27.4%, First Solar 16.7%.
One de-rating is earned and one is not. Enphase's price-to-gross-profit multiple has halved from 14.55x in May to 7.81x, and its forward multiple of 8.74x sits above the trailing one — arithmetic that only works if gross profit shrinks, which is exactly what consensus models. SolarEdge fell further, to 7.57x from 16.09x in May, with the forward figure level at 7.64x, meaning no growth is priced into a company whose margin has expanded for six quarters. Against that sits a guided sequential revenue decline, a GAAP loss, and $337m of 2.25% convertible notes due July 2029.
So two companies whose revenue lines point in opposite directions now cost almost exactly the same per dollar of gross profit. The market has stopped distinguishing between them, and both managements have answered by pointing at 2028. SolarEdge's chief executive, Shuki Nir, framed the 800-volt transition as a question of whether such systems can be trusted at scale — a fair engineering answer to an investor question that was about revenue timing.
The next event either company controls is not a lab result. It is a purchase order with a date on it.