

Virginia Ordered Extra Hearings on the Merger That Fixed Dominion at 0.8138 NextEra Shares
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
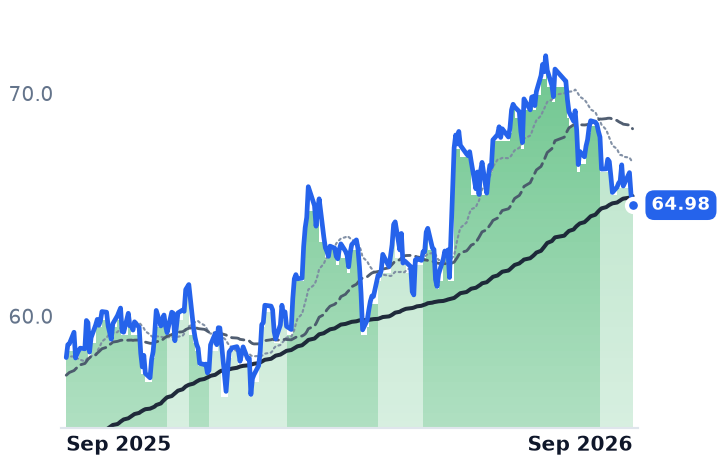
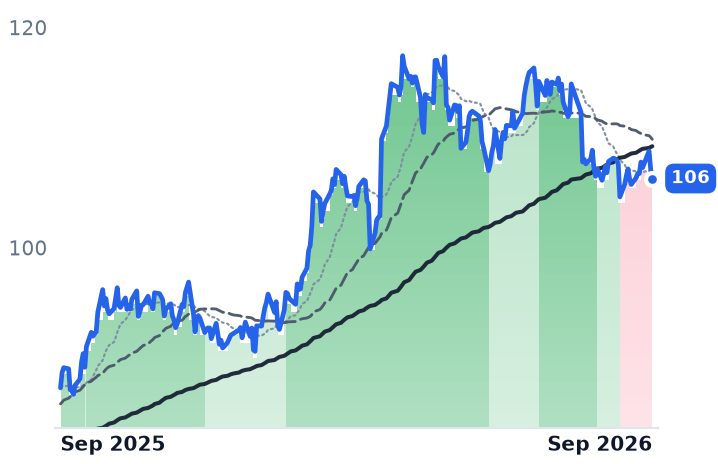
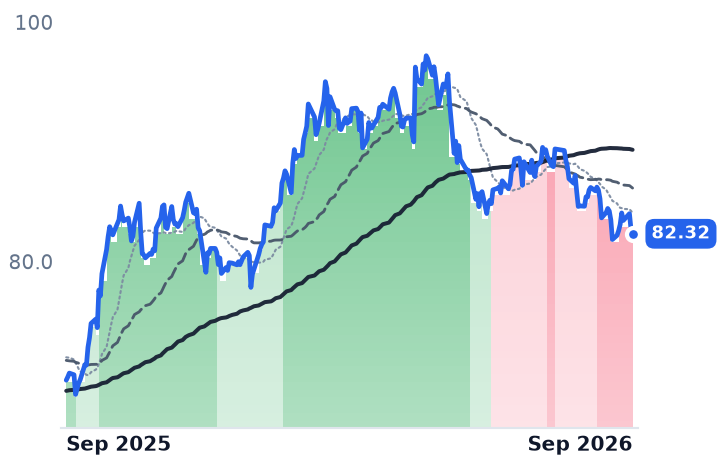
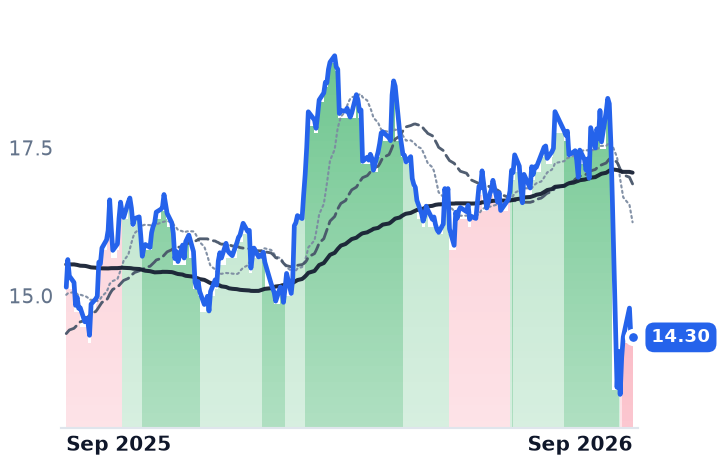
The utility most often named as the purest way to own Northern Virginia's data-center boom has stopped trading on its own fundamentals. Since NextEra agreed in May to buy Dominion Energy entirely in stock, Dominion has moved as a fixed fraction of NextEra, and the two fell almost identically over the past thirty days; the ratio sits about 3% below deal terms. Virginia's regulators, who allowed Dominion a 9.8% return on equity in last year's rate review, are now hearing the merger case instead.
That leaves Entergy as the large regulated operator whose price is still its own — and it has de-rated from 29.9x trailing earnings in May to 26.9x while revenue grew 5.9% last quarter and guidance held. The cost of funding a $67bn capital plan, rather than a worse business, is doing the work.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
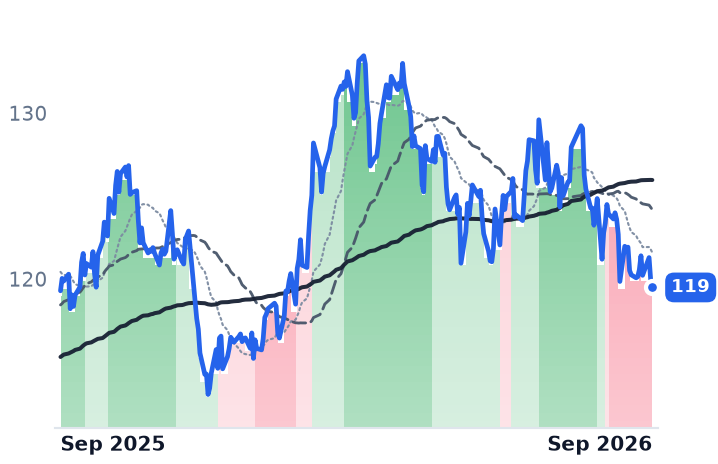
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −3.9% | +11.8% |
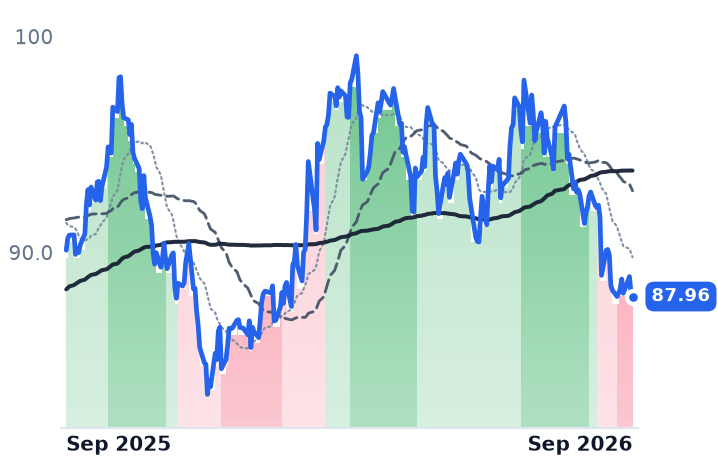
ETR | Entergy | Vertically Integrated Utilities | 🟢 Cont. Bull | −0.4% | +21.8% |
| Compared against · context, not the story | |||||
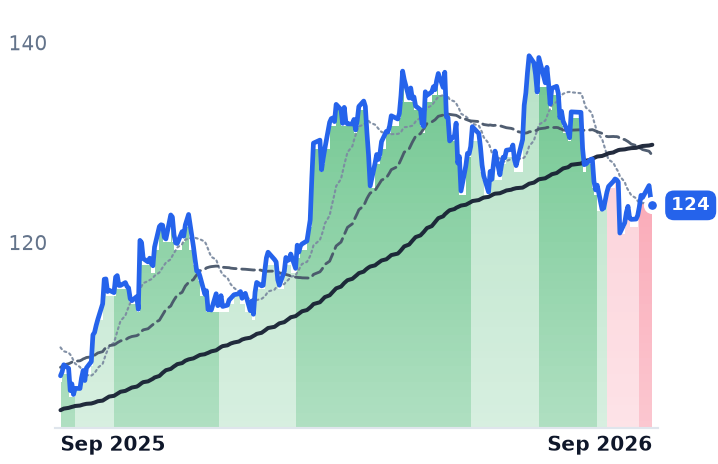
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.6% | +17.5% |
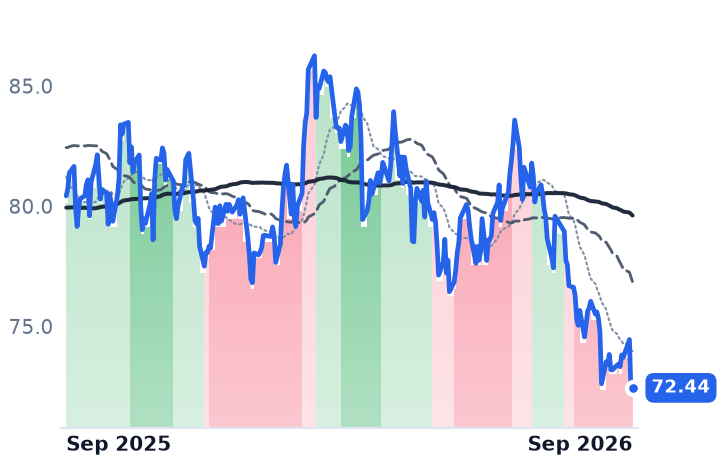
PCG | PG&E | Vertically Integrated Utilities | ⚠️ Emerging Bear | −16.5% | −5.6% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −2.7% | +0.2% |
SO | The Southern | Vertically Integrated Utilities | 🟢 Cont. Bull | −4.2% | −2.4% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | +0.2% | +16.0% |
PEG | Public Service Enterprise Group Incorporated | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.5% | −9.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
D | $57.4B | 22.6x | 18.2x | 3.1x | 3.1x | 6.4x | 6.4x | 15.0x | -11.9% |
ETR | $49.8B | 26.9x | 24.2x | 3.7x | 3.6x | 9.5x | 9.2x | 14.4x | -6.3% |
NEE | $175.3B | 18.8x | 20.9x | 6.0x | 5.7x | 8.4x | 7.9x | 16.0x | -5.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
PEG | $37.7B | 18.7x | 17.3x | 3.0x | 3.0x | 3.5x | 3.5x | 14.2x | 5.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
D | Revenue | +13.7% | +6.5% | +5.8% |
| EPS | +5.0% | +6.3% | +7.0% | |
ETR | Revenue | +8.7% | +9.7% | +9.7% |
| EPS | +12.3% | +16.1% | +13.6% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
PEG | Revenue | +6.5% | +3.5% | +4.9% |
| EPS | +8.1% | +7.0% | +7.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The docket changed subject
Virginia's State Corporation Commission this week ordered three in-person public hearings across Dominion Energy's service territory in the case that would hand the state's largest electric utility to NextEra Energy, an unusual addition to three days of telephonic testimony already scheduled. For the company whose wires serve the densest cluster of data centers on earth, the live regulatory question is no longer what it will be allowed to earn on what it builds. It is who will own it.
The distinction has already emptied Dominion's fundamentals of any effect on its share price. On 18 May NextEra agreed to buy Dominion in an all-stock deal at a fixed ratio of 0.8138 NextEra shares per Dominion share, with a one-time $360m cash payment at closing and completion targeted for the second half of 2027. Both shareholder bases approved the $66.8bn combination on 3 September. Rate base, allowed return, the new large-load tariff, an offshore wind farm four-fifths built — all of it now informs an arbitrage spread rather than a valuation.
Nine-tenths of a decline that belongs to someone else
Over the thirty days to 10 September, Dominion fell 3.9% and NextEra fell 3.6%. The ratio between the two closes moved from 0.7919 to 0.7894 — three-tenths of one percent. On 15 May, before the announcement, that ratio was 0.6612; three sessions later it was 0.7588. At 0.7894 it sits roughly 3% under the 0.8138 the deal promises, which is the market's combined price for deal risk and the wait. Dominion has not been in a downtrend at all this summer; its 50-day average has stayed above its 200-day throughout.
The clock is regulatory. The companies filed their joint petition with the Virginia commission on 15 July under the Utility Transfers Act, and the 60-day statutory deadline falls on 13 September, extendable by 120 days to 11 January 2027.
What the deal froze in place
Dominion's June quarter showed exactly the squeeze the merger now obscures. Revenue rose 19.6% to $4.558bn while operating income fell 2.4% and net income fell 55.3% to $340m. The company reported operating earnings of $0.79 a share against $0.37 on a reported basis and reaffirmed full-year operating guidance of $3.45 to $3.69. Virginia's commission last year raised the authorized return on equity only to 9.8% from 9.7%, against 10.4% requested, and cut the 2026 base-rate increase to $565.7m from the $822m sought. The demand itself is less contracted than the headlines suggest: Dominion discloses more than 53 gigawatts of data-center capacity in various contracting stages but about 12 gigawatts under executed service agreements. The path from load to revenue runs through a new rate class for customers above 25 megawatts, effective January 2027, requiring minimum payment on 85% of contracted transmission and distribution demand and 60% of generation demand. Coastal Virginia Offshore Wind is 81% complete, and its levelized cost has risen to about $62 a megawatt-hour from $56, with owners bearing half of any costs above $10.3bn under the 2022 settlement. At 22.6x trailing and 18.2x forward earnings on consensus growth of 5% this year, none of that clears the price. NextEra does.
The one still trading on itself
Entergy, the New Orleans utility serving about three million customers across Arkansas, Louisiana, Mississippi and Texas from roughly 26,000 megawatts of capacity, about 6,000 of it nuclear, is the remaining unencumbered version of the same demand story — and it has been rolling over since late August, down 3.8% across three months. Its business went the other way. Second-quarter revenue rose 5.9% to $3.524bn and net income 3.4% to $487.8m; adjusted earnings slipped to $1.03 a share from $1.05 as weather normalized, and 2026 guidance of $4.25 to $4.45 was affirmed. Industrial sales grew 10% excluding weather. "We continue to have seven to 12 gigawatts of hyperscale data center potential in our pipeline, as well as three to five gigawatts of interest from traditional industrial segments," chair and chief executive Drew Marsh told investors on 29 July.
The credit and regulatory meters the bear case needs are not cooperating. Entergy Louisiana reported an as-reported return on equity of 11.0% for the twelve months to March in its formula-rate filing — earning above what Dominion is allowed. Funds from operations to debt is running at or above 15% and is projected to stay above S&P's 13% threshold through 2030. Under the Meta agreements, the customer finances more than 5.2 gigawatts of new gas plants and roughly 240 miles of 500-kilovolt transmission while Entergy keeps the regulated assets; Louisiana rate base is expected to roughly double to near $50bn by 2030 inside a $67bn five-year plan.
What that plan costs is the real story in the multiple. Diluted shares went from 431.6m in 2024 to 466.3m by the June quarter, about 8% dilution in eighteen months, including a $2.175bn equity forward in May. The 30-year Treasury yield touched about 5.32% in mid-August, its highest since 2002, and Duke Energy sold $1.75bn of equity units that month at a 7.75% all-in distribution rate against a 9.8% allowed return — roughly two points of spread between what new capital costs and what regulators permit.
The verdict
Entergy's decline is a de-rating, and an honest one, but nothing in the operating record earns it: revenue, industrial volumes, guidance and credit metrics all improved or held. The multiple is falling from 29.9x trailing in May to 26.9x now, 24.2x forward, against a long-run median near 16.8x for vertically integrated utilities — which means the compression is arithmetic catching up to an expensive starting point and a higher discount rate, not a verdict on Meta's megawatts. Consensus still has earnings accelerating 12.3% this year and 16.1% next.
One more correction is worth making about the group these two are filed under. Its 4.3% average thirty-day decline is one broken name: PG&E fell 16.5% after California's legislature passed a wildfire bill stripped of the liability protections utilities expected. Excluding it, the other seven averaged a 2.6% loss.
Virginia spent years litigating what Dominion may charge the data centers. It now has until January, at the outside, to decide who collects.