

Karman's Golden Dome Money Awaits a Bill; BWXT's Navy Reactor Work Is Under Contract
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
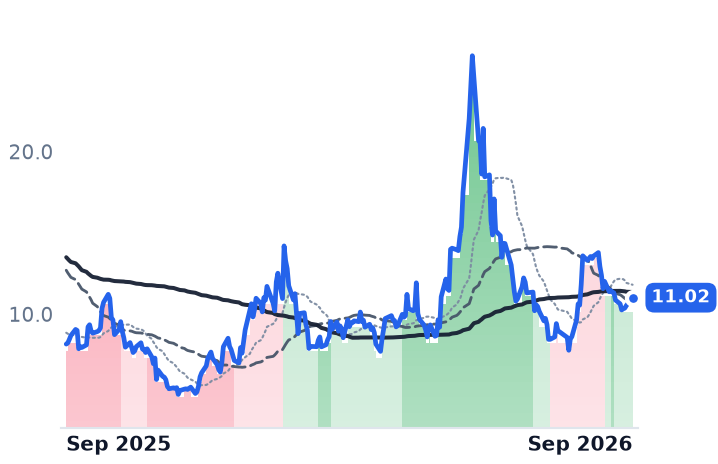
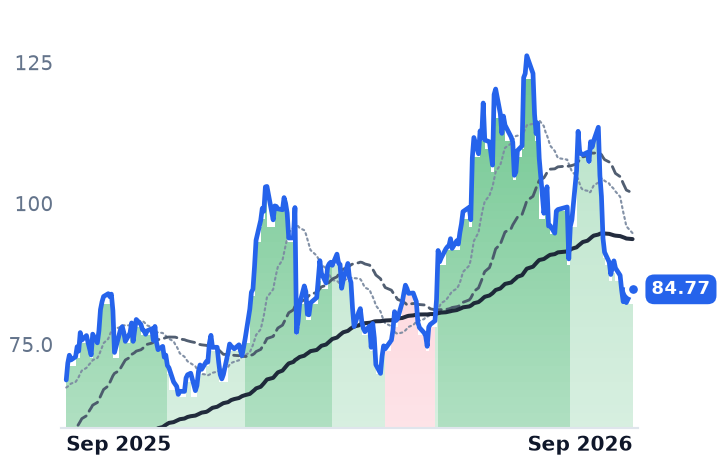
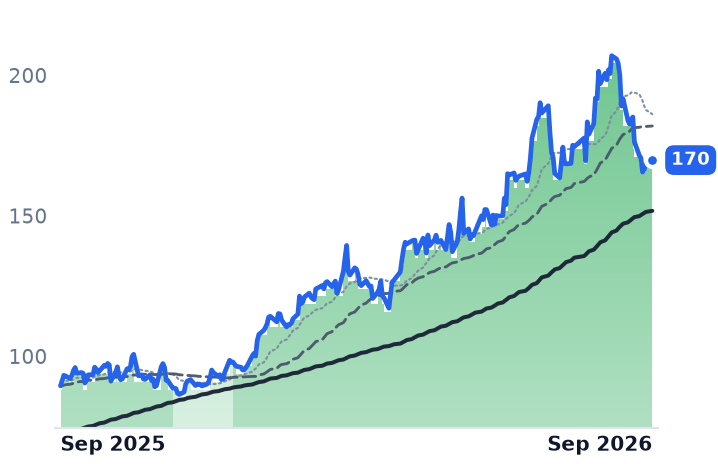
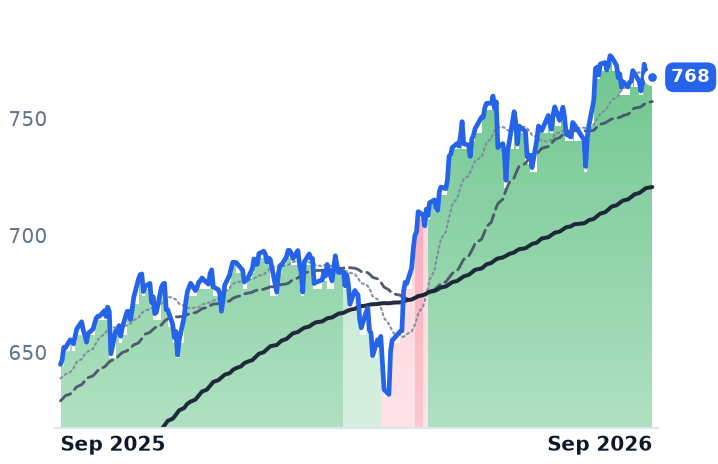
Defense suppliers reported some of the biggest order books in their history this summer and then sold off as a group. Over the past thirty days almost every name in the complex fell — Mercury Systems 22.0%, Kratos 19.9%, HEICO 13.4% — against an S&P 500 tracker that barely moved.
Both of the names carrying the propulsion-and-launch-structures label grew their signed obligations through it. BWX Technologies ended the June quarter with $8.4bn of backlog, up 40% year over year, and raised all four of its 2026 guidance lines. Karman's backlog rose 65% to $1.3bn with 95% of this year's revenue already booked and gross margin widening to 43.0%.
The split is in whose demand is appropriated. The Navy signed $76.6bn of submarine work in July; $17.1bn of the missile-defense architecture underwriting Karman's incremental case sits in a bill that has not passed. BWXT's own defect is margin, ground from 16.3% in 2021 to 10.1% last year.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
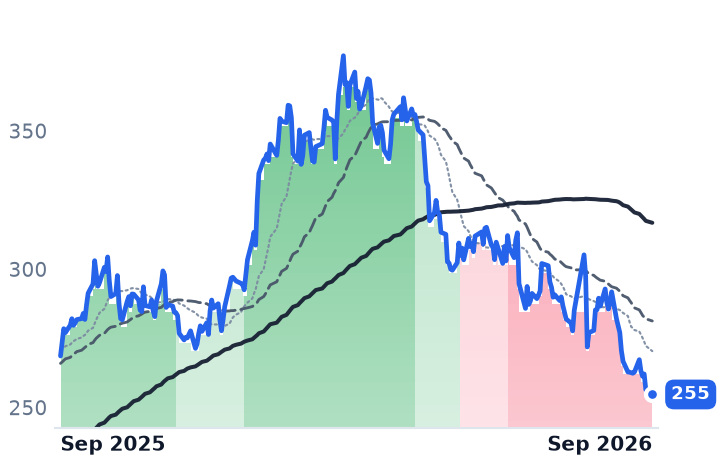
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −5.1% | −0.8% |
KRMN | Karman | Missiles, Weapons & Fire Control | ⚠️ Emerging Bear | −35.4% | −36.5% |
| Compared against · context, not the story | |||||
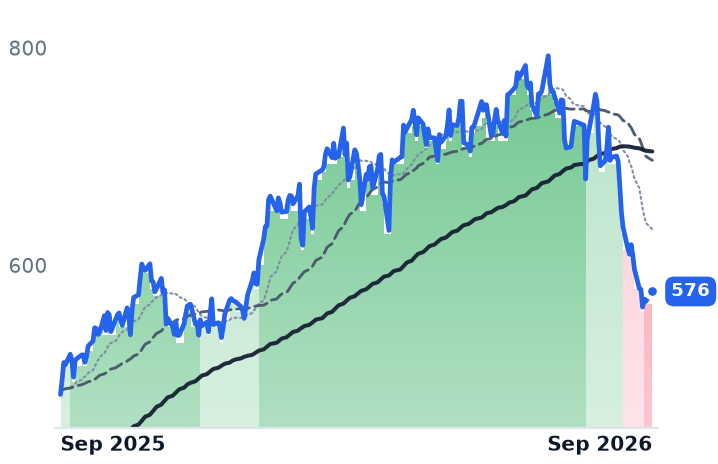
HEI | HEICO | Avionics & Electronic Systems | 🟢 Cont. Bull | −13.7% | +0.7% |
TDG | TransDigm Group Incorporated | Advanced Materials & Components | 🌱 Emerging Bull | −6.2% | −12.3% |
NOC | Northrop Grumman | Large Diversified Primes | ⚠️ Emerging Bear | −11.1% | −9.1% |
LMT | Lockheed Martin | Large Diversified Primes | ⚠️ Emerging Bear | −10.9% | +19.2% |
GD | General Dynamics | Large Diversified Primes | 🟢 Cont. Bull | −10.3% | +12.2% |
HII | Huntington Ingalls Industries | Naval & Shipbuilding | ⚠️ Emerging Bear | −12.6% | +8.8% |
LHX | L3Harris Technologies | Avionics & Electronic Systems | ⚠️ Emerging Bear | −13.0% | −5.2% |
CW | Curtiss-Wright | Flight Controls & Actuation | 🟢 Cont. Bull | −17.3% | +19.7% |
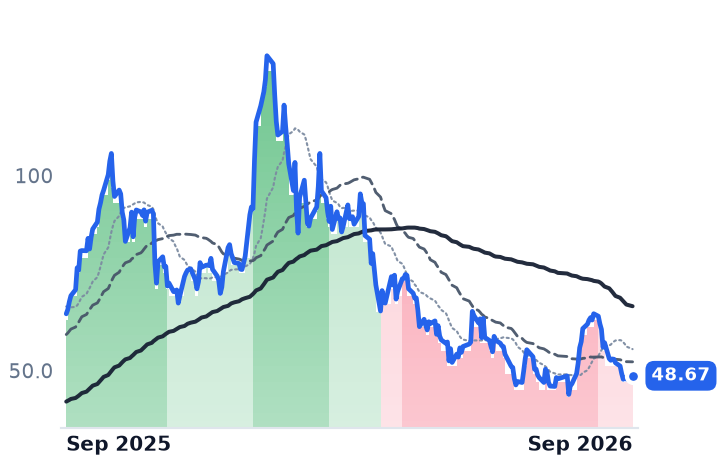
KTOS | Kratos Defense & Security Solutions | Missiles, Weapons & Fire Control | ⚠️ Emerging Bear | −21.4% | −24.6% |
RKLB | Rocket Lab USA | Unmanned Systems & ISR | ⚠️ Emerging Bear | −19.4% | +41.3% |
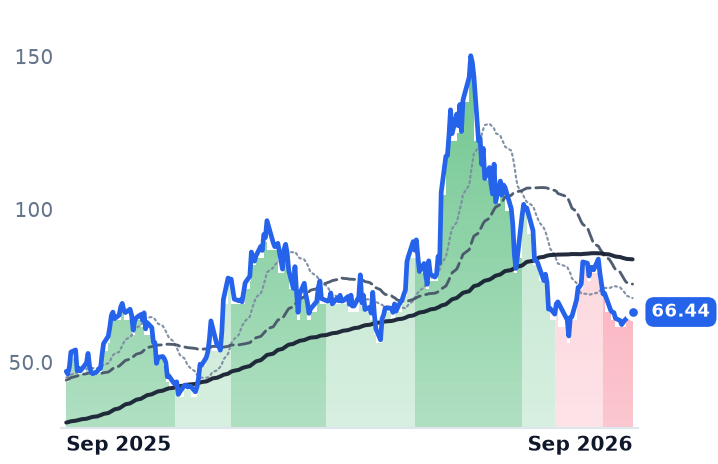
RDW | Redwire | Space Systems & Launch | 🌱 Emerging Bull | −17.2% | +35.0% |
MRCY | Mercury Systems | Other | 🟢 Cont. Bull | −22.3% | +23.4% |
DCO | Ducommun Incorporated | Avionics & Electronic Systems | 🟢 Cont. Bull | −15.4% | +89.7% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.8% | +19.0% |
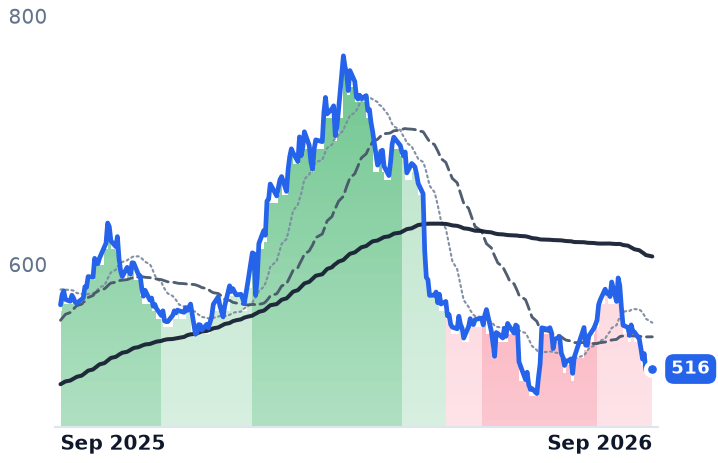
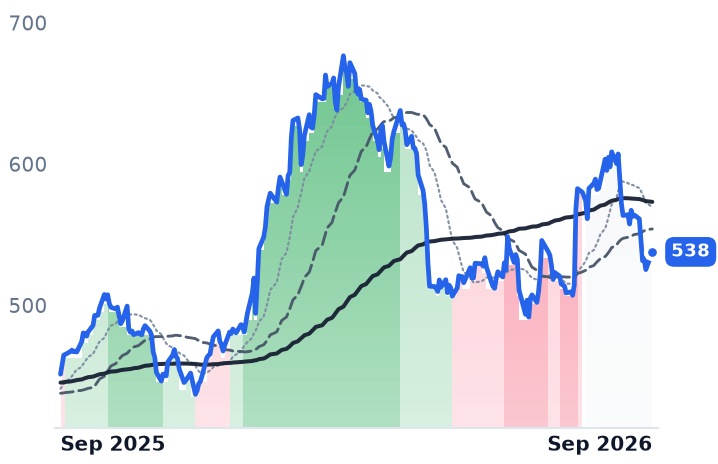
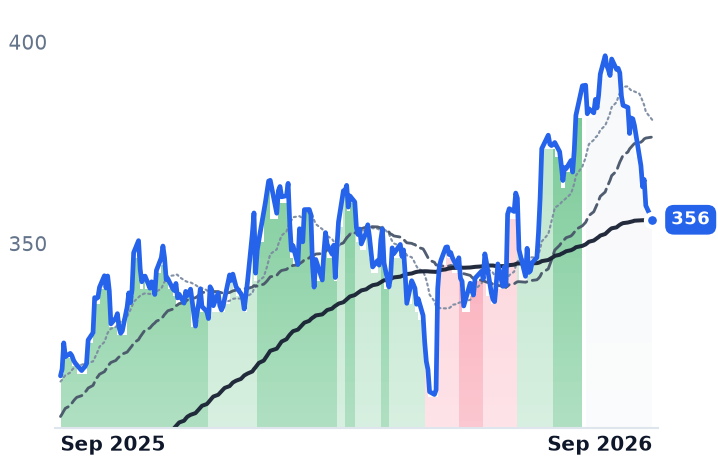
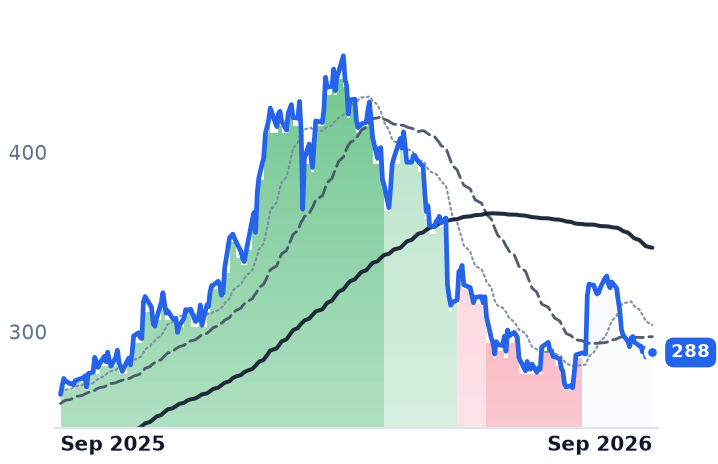
12-month price & trend
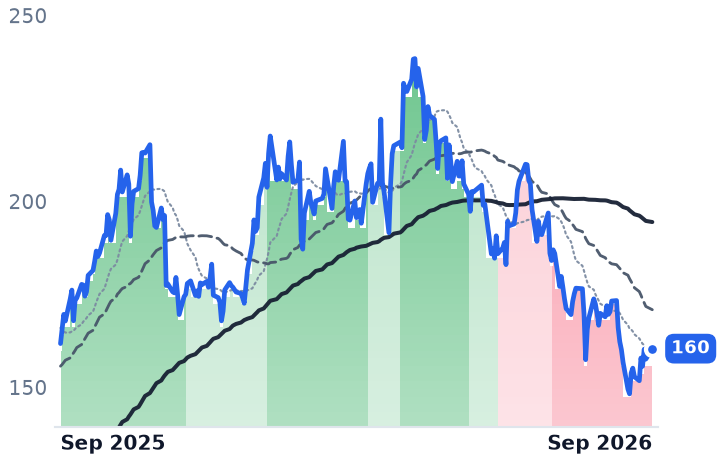
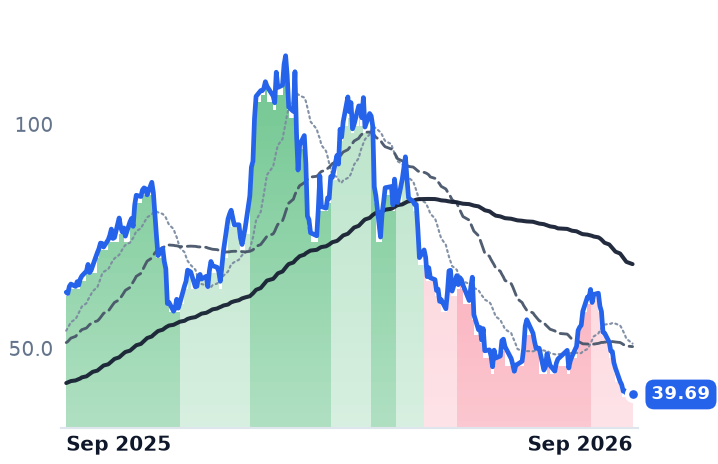
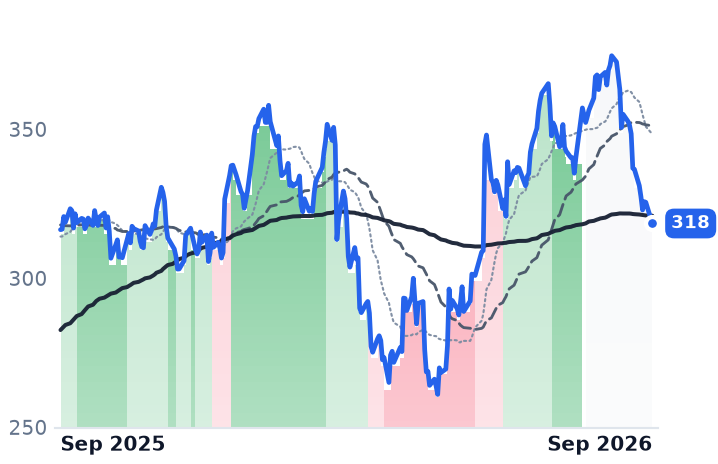
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $14.7B | 41.3x | 33.8x | 4.2x | 3.9x | 19.0x | 17.5x | 29.1x | 2.2% |
KRMN | $5.3B | 139.3x | 67.6x | 8.9x | 7.1x | 21.4x | 17.1x | 42.6x | -0.5% |
HEI | $44.0B | 52.0x | 50.3x | 8.5x | 8.2x | 21.1x | 20.2x | 31.6x | 2.3% |
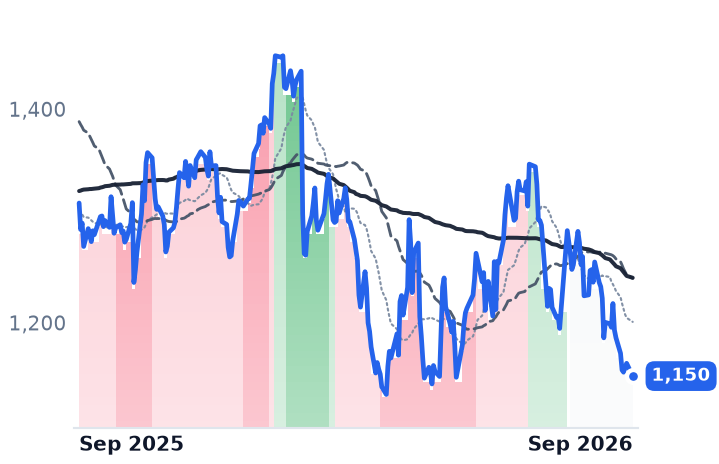
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TDG | $64.1B | 34.7x | 27.9x | 6.4x | 6.1x | 10.7x | 10.2x | 19.0x | 3.0% |
NOC | $76.8B | 16.8x | 19.3x | 1.8x | 1.7x | 8.8x | 8.5x | 12.2x | 4.3% |
LMT | $119.0B | 24.8x | 17.2x | 1.6x | 1.5x | 16.1x | 15.3x | 17.0x | 4.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GD | $90.5B | 20.8x | 20.1x | 1.7x | 1.6x | 11.0x | 10.7x | 15.2x | 6.9% |
HII | $11.3B | 17.0x | 15.3x | 0.9x | 0.8x | 6.8x | 6.7x | 12.7x | 3.3% |
LHX | $51.6B | 27.8x | 23.2x | 2.3x | 2.2x | 8.8x | 8.6x | 16.5x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CW | $26.3B | 51.5x | 46.9x | 7.3x | 7.0x | 19.6x | 18.8x | 36.4x | 2.2% |
KTOS | $9.8B | 302.5x | 62.0x | 6.4x | 5.5x | 29.1x | 24.8x | 71.8x | -1.3% |
RKLB | $72.2B | n/m | — | 106.3x | 79.7x | 290.7x | 218.0x | n/m | -0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RDW | $2.6B | n/m | — | 6.2x | 5.5x | 30.7x | 27.5x | n/m | -3.9% |
MRCY | $5.5B | n/m | 86.8x | 5.7x | 5.8x | 20.6x | 20.8x | 64.1x | 1.3% |
DCO | $3.0B | n/m | 48.1x | 3.5x | 3.4x | 12.9x | 12.5x | 564.5x | -0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.6% | +7.0% |
| EPS | +24.1% | +11.6% | +11.7% | |
KRMN | Revenue | +57.5% | +27.5% | +25.8% |
| EPS | +62.0% | +61.1% | +38.7% | |
HEI | Revenue | +21.1% | +11.1% | +8.7% |
| EPS | +31.4% | +13.5% | +13.1% | |
TDG | Revenue | +19.4% | +10.1% | +7.6% |
| EPS | +12.2% | +17.7% | +15.2% | |
NOC | Revenue | +5.1% | +6.7% | +6.1% |
| EPS | +7.2% | +7.9% | +8.6% | |
LMT | Revenue | +6.1% | +5.4% | +5.5% |
| EPS | +38.4% | +7.1% | +6.2% | |
GD | Revenue | +6.4% | +4.6% | +4.2% |
| EPS | +7.9% | +9.5% | +7.9% | |
HII | Revenue | +10.8% | +6.4% | +6.4% |
| EPS | +23.6% | +12.3% | +16.4% | |
LHX | Revenue | +3.2% | +7.3% | +7.0% |
| EPS | −18.5% | +12.2% | +13.9% | |
CW | Revenue | +9.6% | +8.0% | +8.1% |
| EPS | +15.6% | +12.0% | +12.1% | |
KTOS | Revenue | +34.7% | +23.3% | +21.7% |
| EPS | +57.7% | +34.4% | +28.7% | |
RKLB | Revenue | +51.0% | +39.0% | +27.0% |
| EPS | −41.8% | −100.1% | +68844.3% | |
RDW | Revenue | +44.6% | +18.7% | +21.2% |
| EPS | −55.6% | −52.4% | −57.9% | |
MRCY | Revenue | +8.6% | +9.1% | +10.2% |
| EPS | +164.9% | +44.7% | +39.5% | |
DCO | Revenue | +7.1% | +9.2% | +8.2% |
| EPS | +13.2% | +23.2% | +16.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Every large aerospace and defense supplier lost ground over the past thirty days, and none of their order books did. Mercury Systems, which builds processing subsystems for missile and radar programs, fell 22.0% and the defense drone maker Kratos 19.9%, against an S&P 500 tracker down 0.7%. BWX Technologies — whose backlog grew 40% year over year to $8.4bn — was the shallowest faller in the group at 5.6%, and Karman Holdings the deepest at 31.8%. What began as a single-stock unwind at Karman is now a sector-wide repricing: over six months the index rose 13.2% while Huntington Ingalls fell 32.8%, L3Harris 31.4% and Northrop Grumman 31.0%.
What separates these companies now is not whether the demand is real but whether Congress has already paid for it. The Navy awarded a $76.6bn package on 30 July covering five Columbia-class and nine Block VI Virginia-class submarines. The Pentagon's Golden Dome missile-defense architecture, by contrast, is a $17.9bn fiscal-2027 request of which $17.1bn would arrive through a reconciliation package that has not passed. A senior general said in August that "there is no Golden Dome" unless Congress prioritizes the funding.
The annuity with a margin problem
BWXT makes naval reactor cores, nuclear fuel and missile launch tubes as a sole-source supplier to the Naval Nuclear Propulsion Program, plus commercial steam generators. It announced more than $1.4bn of naval propulsion contracts in May, runs a trailing book-to-bill of 1.7x, and in late August the Army selected its gas-cooled BANR design for a microreactor at Fort Campbell under the Janus program, worth up to $2.2bn across five vendors. "Demand for new nuclear solutions is remarkably deep and broad," chief executive Rex Geveden said in the August 3 results release, the same day the company raised revenue, adjusted earnings, adjusted EBITDA and free-cash-flow guidance, the last by $30m to $345–360m.
The defect is beneath the orders. Gross margin fell to 22.4% in the June quarter from 25.1%, and reported operating income has now declined year over year for four consecutive quarters while revenue grew 18% to 29% in each. Annual operating margin has ground from 16.3% in 2021 to 10.1% in 2025 on 51% more revenue — capacity funded ahead of the awards it serves, with commercial segment margin guidance cut to about 13% for hiring and plant expansion and recovery deferred to 2027. The growth leg the label implies is also leaving: BWXT is selling its medical isotope business to Nordic Capital for $750m base consideration, roughly $130m of annual revenue out the door.
The one whose money is a request
Karman builds payload fairings, interstage structures and propulsion units for missile-defense, hypersonics and launch customers, sole-source on more than 130 programs. Its June quarter was the strongest in its short public life: revenue up 58.2% to $182.1m, roughly $500m of bookings, gross margin at 43.0% against 40.9% a year earlier, guidance lifted to $730–745m. "Some customers are now citing demand to increase certain annual production buys by as much as a factor of 10x," chief executive Jonathan Rambeau told investors on August 6 — a pull HEICO corroborated later that month, reporting 23.1% revenue growth and citing customer expedite requests of two to ten times.
None of that is what moved the shares. A secondary offering priced 14m shares at $61.00 on May 28, 54% above today's price, with sponsor lockup tranches releasing on October 1 and January 1. Chief financial officer Mike Willis steps down effective September 14. And J Capital Research published a bear case attacking acquisitions disclosed as immaterial, landing on a material weakness in internal controls management does not expect to finish testing until early 2027; the shares fell about 11% that week. The cash record is the soft spot the operating record hides: negative $4m of operating cash flow in the first half, 3.7x leverage.
What the price now pays for
BWXT trades at 33.8x forward earnings against roughly 46x recorded in early May, and 41.3x trailing against 55.0x then — while consensus 2026 earnings estimates rose from $4.05 to $4.74 a share over the same stretch. Karman fetches 67.6x forward earnings and 8.92x trailing sales, down from about 24x enterprise value to revenue in May. HEICO, the highest-quality comparison in the group, still commands 50.3x forward earnings; TransDigm, at 27.9x, is the cheapest anchor and the one against which both look dear.
So BWXT's decline is almost entirely premium removal, with one honest business claim on it — four quarters of falling operating income are a real deterioration, and the fifty-day average has sat below the two-hundred-day since early July. Karman's is larger than anything in its operating record explains; the identifiable causes are dated sponsor supply, a finance-chief change and an unremediated control weakness, none of which touch the $1.3bn already booked. The company's contracted base is intact. Its incremental case is a legislative vehicle.
The next tranche of sponsor shares comes free on October 1, and Karman's new finance chief will have been in the seat about three weeks when it does.