

Sunrun's Revenue Grew 53%; the Cash It Books Per New Customer Fell 44%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Sunrun's reported results and its own cash meters point in opposite directions, and only one of them describes the business. The largest US residential solar installer recognizes lease and power-purchase revenue across 20-to-25-year contracts while the money actually arrives up front — from tax-equity partners, from tax credits sold to corporate buyers, and from securitizations priced off a credit spread.
Net subscriber value fell to $9,444 from $17,004 a year earlier, the cost of creating those subscribers rose 92% to $469m, and full-year cash-generation guidance came down to $200-375m. XPLR Infrastructure, the contracted wind and solar partnership sitting in the same group, is the mirror: reported operating income fell while free cash flow before growth held at guidance, with the distribution suspended to fund dated buyouts. These four names are not one trade — their twelve-month returns span 64 percentage points.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
RUN | Sunrun | Residential Solar Installers | ⚠️ Emerging Bear | −11.8% | −44.9% |
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | +3.6% | +19.2% |
| Compared against · context, not the story | |||||
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −1.7% | +14.4% |
FSLR | First Solar | Solar Module Manufacturers | 🟢 Cont. Bull | −13.1% | +0.8% |
12-month price & trend
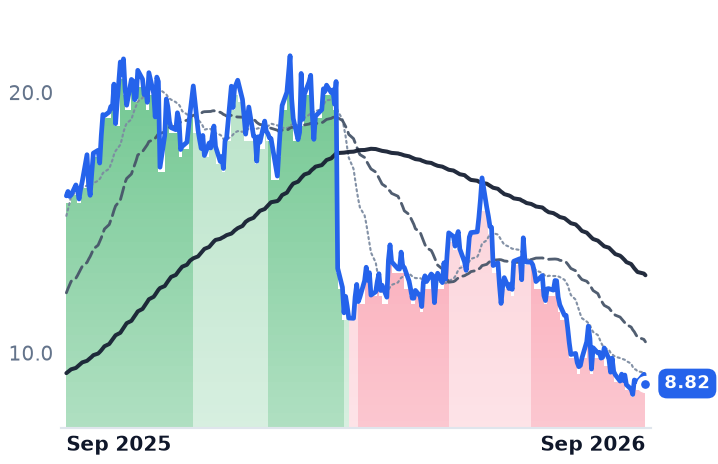
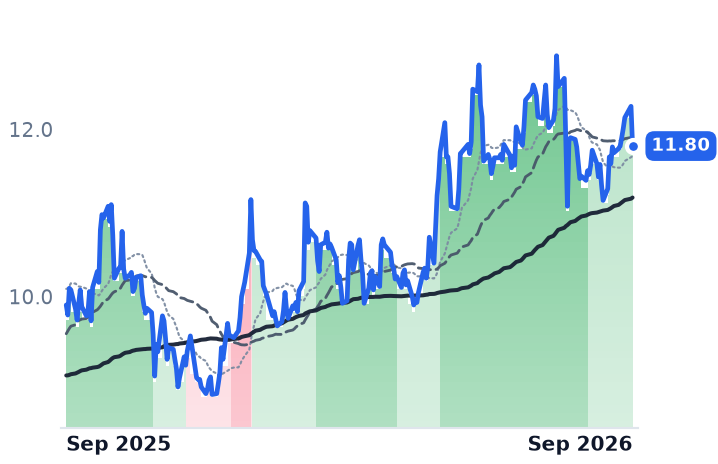
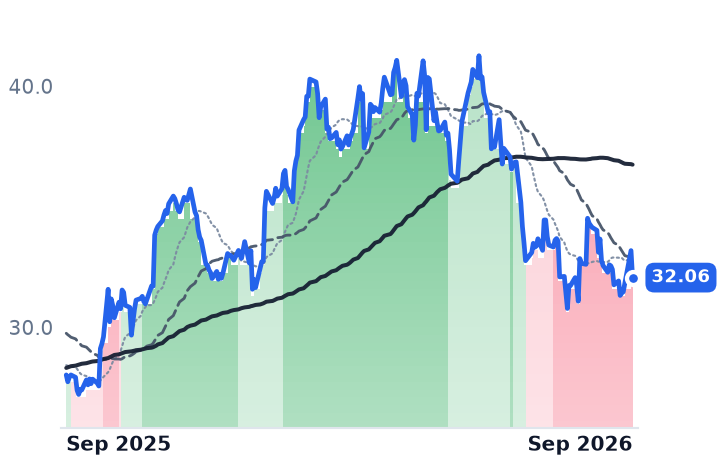
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RUN | $2.1B | 5.2x | 7.0x | 0.6x | 0.7x | 1.8x | 2.0x | 23.4x | -64.1% |
XIFR | $1.1B | 17.7x | 10.4x | 0.9x | 0.8x | 5.4x | 4.8x | 9.0x | -56.8% |
CWEN | $6.5B | 41.4x | — | 4.1x | 3.9x | 7.8x | 7.4x | 14.4x | 10.4% |
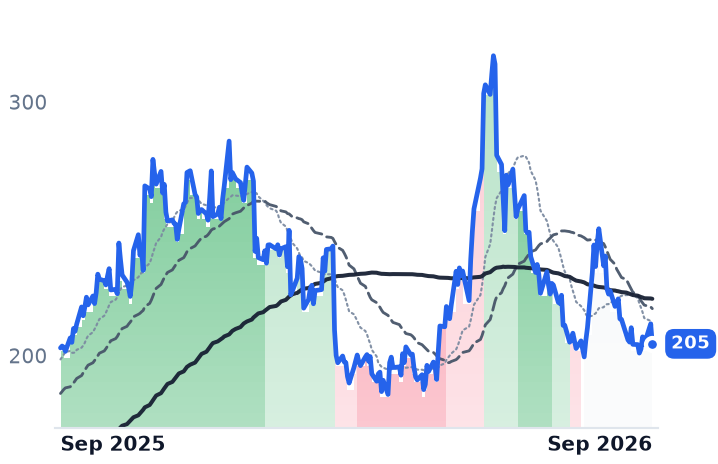
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.0B | 12.6x | 11.8x | 4.1x | 4.4x | 9.3x | 10.0x | 8.4x | 6.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% | |
CWEN | Revenue | +14.8% | +10.8% | +13.4% |
| EPS | −133.6% | −152.5% | +132.7% | |
FSLR | Revenue | −1.7% | +17.1% | +11.8% |
| EPS | +19.5% | +34.3% | +25.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Sunrun added subscribers last quarter and attached batteries to a record share of them, and the value it books on each new customer fell by nearly half. Revenue went the other way, growing 53% year on year to $870m, with gross margin more than doubling to 37.7%.
That gap is not an accident of one quarter; it is the architecture of the business. A residential solar company that owns the systems it installs recognizes customer-agreement revenue across a 20-to-25-year lease or power-purchase contract, while the cash arrives at the front: from tax-equity partners, from investment tax credits transferred to corporate buyers, and from non-recourse securitizations priced off a credit spread. Since the 30% Section 25D homeowner credit expired on 31 December 2025, a third-party-owned system is the only route by which a US household reaches a federal solar credit at all. The monetization chain is now the product.
The meters management itself uses
By those meters the quarter was poor. Net subscriber value fell to $9,444 from $17,004, a 44% decline, and the contracted portion — the part not dependent on customers renewing after year 20 — fell 61% to $5,100. Creation costs carried in operating expenses rose 92% to $469m on smaller volumes, larger systems, higher storage attachment and a costlier shift to in-house direct selling. Cash generation for the quarter was $23m, or $45m before $22m of net investment in safe-harbour equipment. Full-year cash-generation guidance came down to $200-375m from $250-450m, about 18% at the midpoint.
None of that is visible in the income statement, and the operating detail cuts both ways: storage attachment hit a record 74% and subscribers grew 10% to 1,034,738. Volume is fine. Price per unit of capital is not. Chief financial officer Danny Abajian told investors on the August 5 call that Sunrun had seen "some spread benefit" in financing but that higher base rates left its cost of capital "modestly higher than we were expecting coming into the year".
The securitization market disagreed with the equity market. April's $584m deal priced senior notes at a 220 basis-point spread; August's $267m Quintus 2026-2 priced 20 basis points tighter, at 200. The advance rates — 79.3% then 74.2% — measure against different bases and do not compare. Behind those deals sit roughly $14.3bn of asset-level non-recourse debt against $637m of recourse debt and $712m of unrestricted cash at the parent.
XPLR is the same problem read backwards
XPLR Infrastructure, the contracted wind, solar and Texas pipeline owner spun out of NextEra Energy, reported gross profit down 8.8% and operating income down a third, to $60m. Its cash held: adjusted EBITDA of $523m and free cash flow before growth of $257m, with full-year guidance of $600-700m intact. The distribution stays suspended so the money can retire dated obligations. "During the quarter, we completed the first minimum buyout of CEPF 5 and fully repaid our convertible notes with available cash, further simplifying our capital structure," chief executive Alan Liu said on the second-quarter call — a $150m buyout and $500m of converts. Three of these convertible equity portfolio financings are to be bought out by the end of 2027, and roughly $160m of asset sales let it cut planned 2026 corporate debt issuance by $250m. The equity is a retirement schedule with a power portfolio attached: 0.34x book, 8.97x trailing enterprise value to EBITDA, a $1.12bn market value against $600-700m of guided free cash flow before growth.
What the group label conflates
Clearway Energy, the ex-NRG yieldco running about 5,000 net megawatts of wind and solar on 60 employees, cut 2026 cash available for distribution to $430-470m on weak first-half wind, then reaffirmed its 2027 target of $2.70 per share or better and restructured the offtake contracts on all three of its ERCOT wind projects out beyond 2040. First Solar, a cadmium-telluride module manufacturer, holds 45.1 gigawatts of backlog worth $13.6bn — about $0.30 per watt — and earned a 57.3% gross margin on falling revenue, the margin coming from manufacturing credits and $89m of net tariff benefit rather than from price.
So the decline is company-specific where it is severe. Sunrun's 45% twelve-month fall tracks a real 44% collapse in per-customer economics and an 18% guidance cut; XPLR is up 19.2% over the same year. What none of the four earns individually is the September leg, when no company disclosure was discoverable and the 30-year Treasury yield topped 5.33% on 18 August — the likelier reading is the discount rate on long-dated contracted cash flows, applied indiscriminately.
Sunrun's $22m of safe-harbour equipment is now a fixed stockpile: the construction-start window that locked credit eligibility closed on 4 July 2026. When it runs out, every new system prices off whatever rules exist then.