

Ormat's Doubled 2030 Profit Target Excludes Enhanced Geothermal Entirely
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Ormat spent its September 8 investor day promising to roughly double earnings before interest, tax, depreciation and amortization by 2030 — and the plan counts nothing from enhanced geothermal, the technology Fervo Energy is built on. The next session both stocks fell about 8.5% while the broader power complex barely moved.
The fall is not an operating miss. Ormat's contracted power book grew 5.8% last quarter to $169.3m and its named fields improved; what changed is where the growth sits — a third-party construction book at a 9.7% gross margin and merchant battery revenue whose 56.2% margin management guided down toward 40-50%. Consensus has 2026 revenue up 21.4% and 2027 down 1.2%. Fervo, with $113,000 of quarterly revenue and 1,054 megawatts of binding offtake, is priced at roughly 68 times its 2027 consensus sales.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
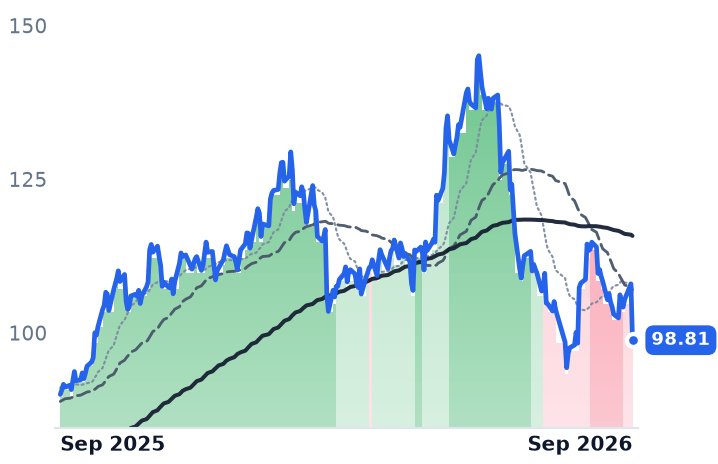
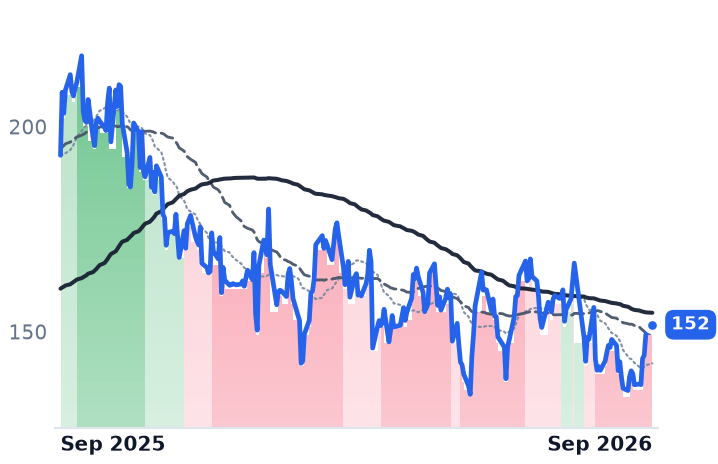
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | −9.1% | +9.8% |
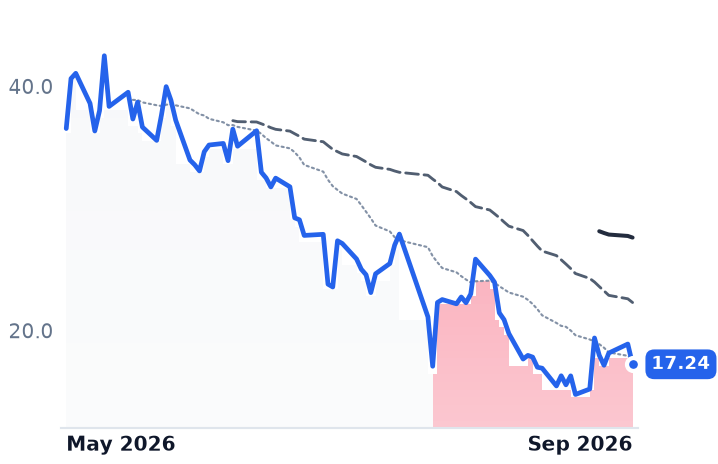
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −29.7% | −52.8% |
| Compared against · context, not the story | |||||
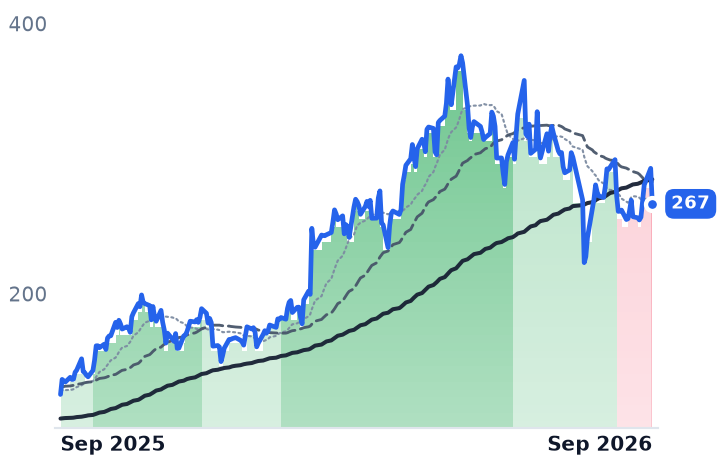
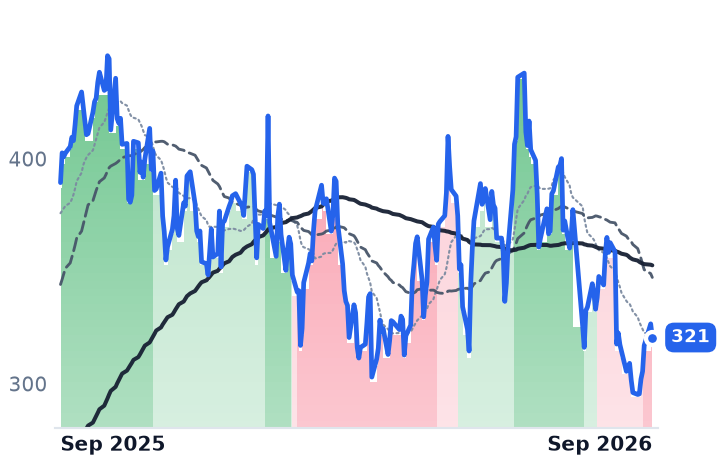
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −1.8% | +112.5% |
CEG | Constellation Energy | Diversified Renewable Generators | ⚠️ Emerging Bear | +8.1% | −1.7% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +5.8% | −21.7% |
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | −6.8% | −17.7% |
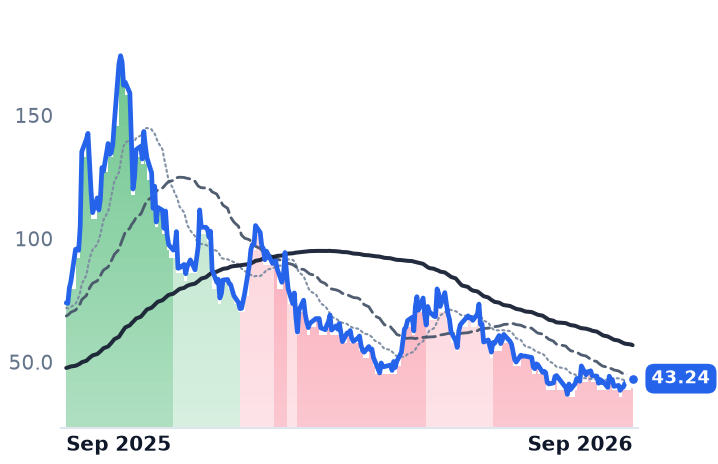
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −3.5% | −41.5% |
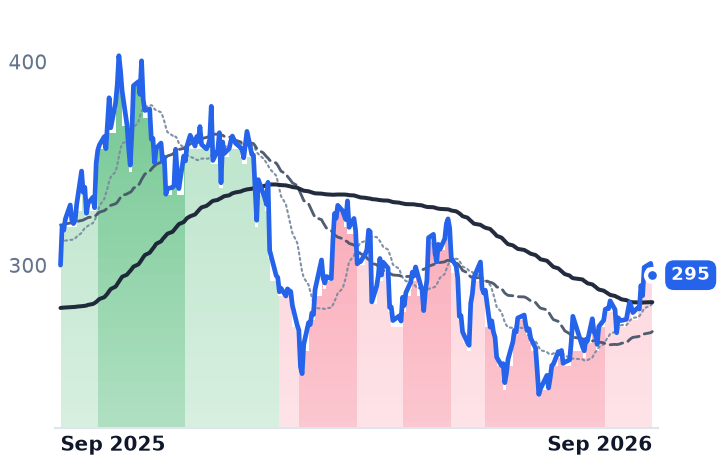
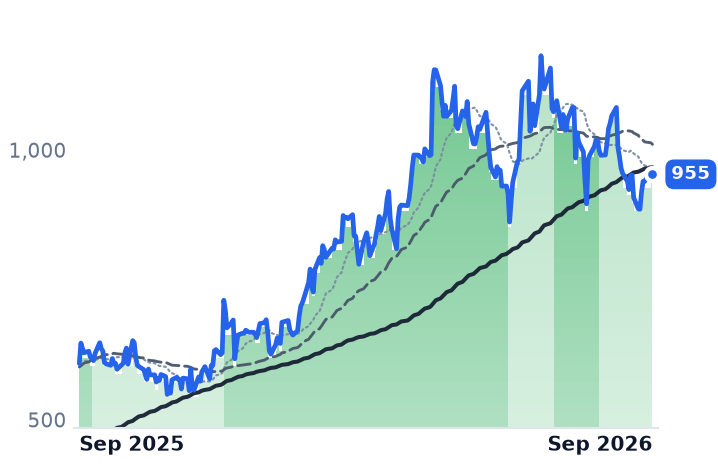
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | −3.6% | +58.0% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.5% | +18.2% |
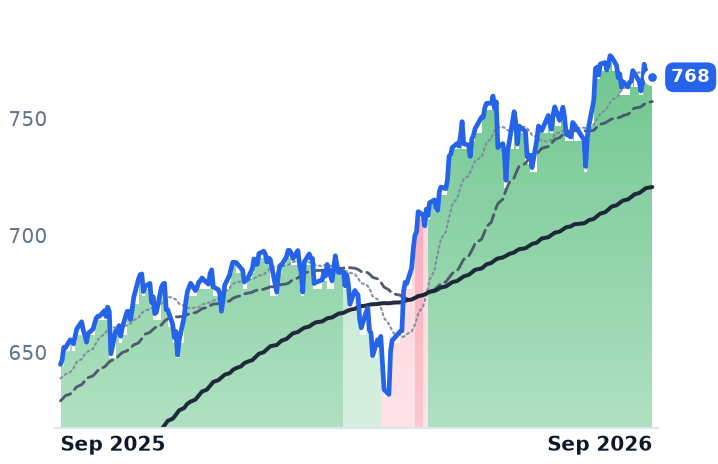
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORA | $6.1B | 47.5x | 38.8x | 5.1x | 5.1x | 18.3x | 18.4x | 20.7x | -4.4% |
FRVO | $4.9B | n/m | — | — | 854.4x | — | — | n/m | -9.0% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $107.4B | 29.1x | 24.8x | 3.4x | 3.2x | 3.6x | 3.4x | 15.4x | 0.3% |
VST | $51.2B | 25.3x | 17.6x | 3.2x | 2.3x | 24.7x | 17.6x | 10.9x | 2.7% |
TLN | $14.4B | n/m | 15.4x | 4.1x | 3.2x | 9.1x | 7.2x | 29.9x | 3.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
GEV | $242.9B | 25.9x | 29.7x | 5.9x | 5.2x | 29.0x | 26.0x | 27.0x | 5.1% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORA | Revenue | +21.4% | −1.2% | +12.0% |
| EPS | +16.4% | −3.5% | +25.9% | |
FRVO | Revenue | +4094.5% | +1158.9% | +186.8% |
| EPS | −92.0% | −19.8% | −26.6% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
CEG | Revenue | +36.6% | +2.6% | +5.5% |
| EPS | +28.7% | +10.1% | +26.3% | |
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% | |
GEV | Revenue | +23.9% | +14.8% | +15.0% |
| EPS | +321.7% | −19.5% | +40.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ormat Technologies, which owns geothermal plants, builds turbines for other owners and runs batteries in wholesale power markets, told investors at the New York Stock Exchange on September 8 that it can roughly double earnings before interest, tax, depreciation and amortization by 2030, to about $1.05bn at the midpoint from $526m, on a 3.5-3.7 gigawatt portfolio. The figure excludes enhanced geothermal — the deep-drilled, engineered-reservoir technique — entirely. The next session the shares closed at $98.81, down 8.5%, on 2.1m shares against an August daily average nearer 400,000. Fervo Energy, a Houston developer whose entire business is enhanced geothermal, fell 8.8% alongside it.
That exclusion is the most honest thing either company has published. Ormat's separate enhanced-geothermal targets are 100 megawatts operating in 2030-2031 and a gigawatt by 2033-2035, led by a 280 MW project at Dixie Valley, Nevada, against which only a 60 MW interconnection agreement has been executed. Asked about Fervo and other startups, management framed its pace as a choice to de-risk first. So the incumbent treats the technology as an option, and the market now prices both companies off schedules that end years from here.
Three books, one label
Ormat's second quarter grew revenue 10.6% to $258.8m and widened gross margin by 2.2 percentage points to 26.5%, while operating income fell 3.2% and net income fell 3.4%. The composition explains it. The contracted power segment — output sold under long-dated fixed-price agreements — grew 5.8% to $169.3m at a 23.7% gross margin. The third-party engineering and turbine book fell to roughly $46.7m at a 9.7% margin, which Ormat's own release attributes to "high expenses related to the construction costs of a project in Europe and the impact of changes in exchange rate on overall manufacturing costs." Merchant battery revenue nearly tripled to $42.8m at a 56.2% margin management guided down to a 40-50% range.
The power annuity is not deteriorating: Puna added about $3m on recovery from the prior year's well-field problem, Olkaria about $2.5m after well-field optimization, and US curtailment cost $4.2m less. What repeats poorly is the rest. Full-year guidance of $1.15-1.2bn leans on the lowest-margin book delivering roughly $85-100m in the second half from a $203m backlog, and about $90m of 2026 cash earnings arrives as sales of transferable tax credits rather than power, $52m of it already collected. Net income has been flat for three years — $124.4m, $123.7m, $123.9m — on revenue that grew from $829m to $990m. Consensus models 2026 revenue up 21.4% and 2027 down 1.2%.
A drilling cost curve
Fervo sells almost nothing yet: $113,000 of revenue last quarter against a $59.5m net loss. Its product is drilling speed. The Sawtooth 7 well reached 19,500 feet and 460°F in 21 days, against more than 70 days for the 11,000-foot wells of its first project. "We're drilling faster, going deeper and hotter, and negotiating hundreds of megawatts of commercial agreements," chief executive Tim Latimer told investors on August 12. On September 1 Google signed a 396 MW agreement for 2028 delivery, lifting binding offtake to about 1,054 MW.
And the shares are down 52.8% from their first close in May. The de-rating began when Fervo published its first hard number: 2027 revenue of $60-80m, wide because a third party's transmission addition will curtail Cape Station in 2027 only. Against consensus 2027 revenue of $72.9m, the $4.95bn market value is roughly 68 times sales, with about 42% of it sitting in cash and no consensus profit until 2029.
What the fall earns
Sell-side reaction to the investor day was positive — Oppenheimer raised its target to $145, RBC held at $130, Jefferies stayed at Hold — so the decline is not a verdict on the 2030 numbers. It was geothermal-specific: Constellation fell 1.9% and Vistra 0.4% that session. The likelier reading is that investors marked the distance between today's price and a target dated four years out, and marked Fervo's longer distance harder.
Ormat trades at 20.7 times trailing EV/EBITDA and roughly 12.3 times 2026 consensus EBITDA of $712m, carrying $2.7bn of net debt at 4.3 times EBITDA — cheapening on a base that is growing, with three years of flat net income as the counter-argument. The business earns the first part of that; nothing in the quarter earns the rest.
Google is the counterparty on Fervo's record contract and on Ormat's portfolio agreement of up to 150 MW through NV Energy. One buyer class's siting decisions now set the contracted revenue on both sides of the geothermal trade, and neither company will know for years which of them it preferred.