

Appian's Contracted Backlog Grew 13.0% Against 19.1% Revenue Growth; Procore's Grew 24%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two beaten-down software vendors turned up together this summer, and the one with the weaker order book got paid far more for it. Appian beat and raised on August 6, but gross margin fell 3.1 points to 71.2%, its professional-services book grew faster than its subscriptions, and the revenue it has signed but not yet recognized grew more slowly than the revenue it reports. Procore's contracted obligations reached $1.67bn, growing eight points faster than revenue, in a year when private nonresidential construction spending outside data centers fell 7.9%.
The judgment: Appian's advance is earned by profitability — adjusted EBITDA of $16.2m against $5-8m guided — and by nothing in its demand meters. Procore's bookings improved and its valuation did not follow.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Low-Code & Process Automation | 🌱 Emerging Bull | −1.8% | +4.2% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🔴 Cont. Bear | −5.6% | −22.5% |
| Compared against · context, not the story | |||||
PEGA | Pegasystems | Low-Code & Process Automation | 🔴 Cont. Bear | +5.3% | −38.9% |
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +2.9% | −29.8% |
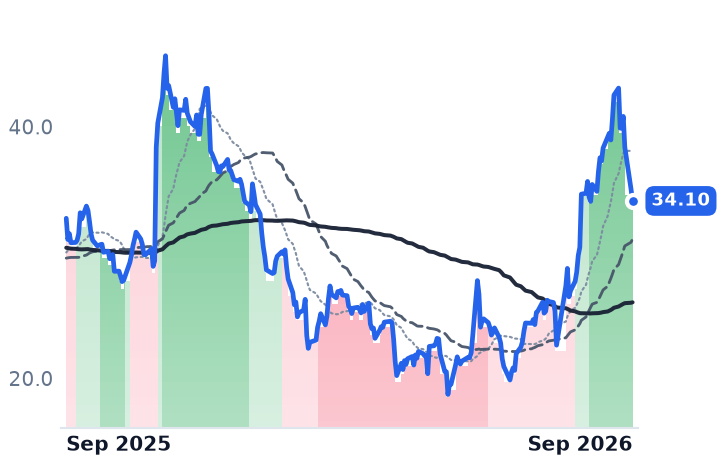
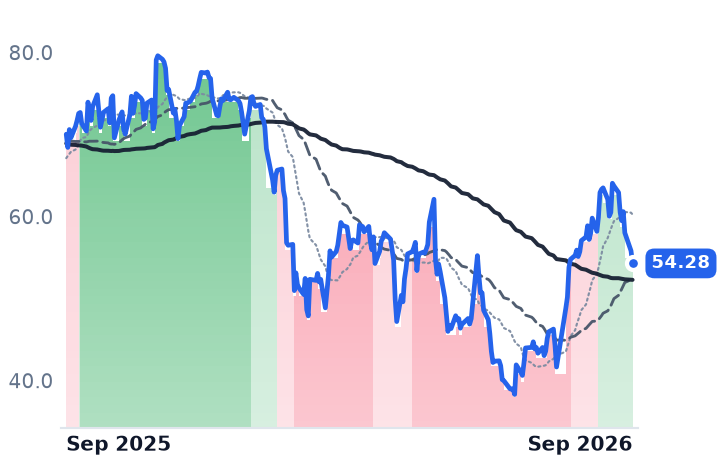
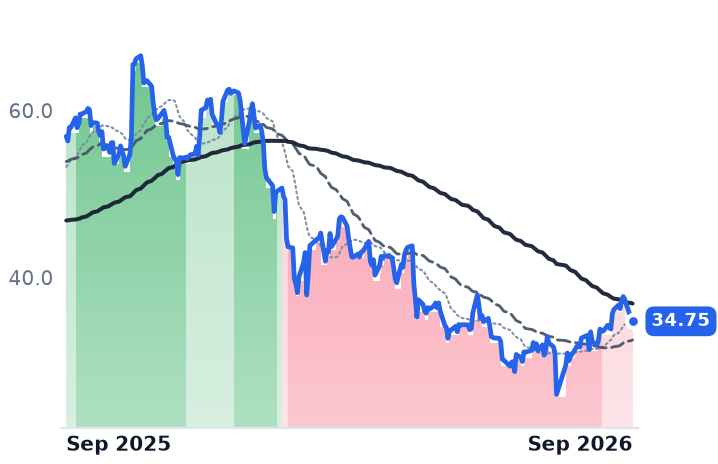
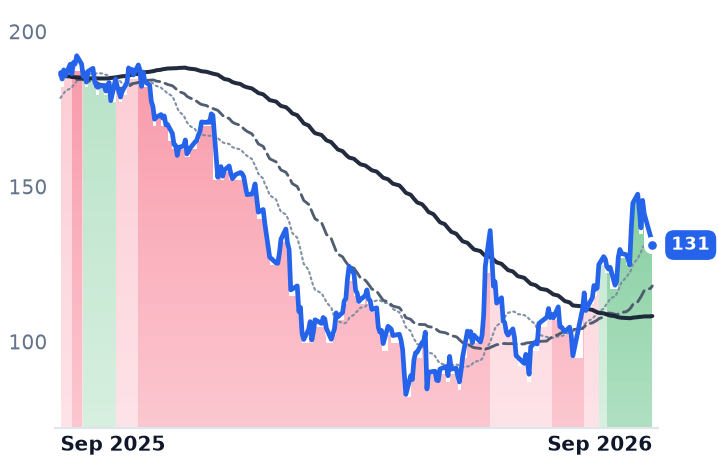
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $2.5B | n/m | 31.7x | 3.2x | 3.0x | 4.4x | 4.1x | 110.1x | 3.0% |
PCOR | $8.2B | n/m | 32.2x | 5.7x | 5.4x | 7.2x | 6.8x | 127.9x | 3.6% |
PEGA | $6.1B | 19.7x | 15.2x | 3.5x | 3.3x | 4.7x | 4.3x | 30.6x | 8.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $132.8B | 79.8x | 31.6x | 9.0x | 8.2x | 12.1x | 11.0x | 39.8x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
PCOR | Revenue | +15.2% | +13.8% | +14.3% |
| EPS | +24.2% | +46.1% | +20.1% | |
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Appian, the McLean, Virginia vendor whose low-code platform lets banks, insurers and federal agencies assemble case-management workflows without hand-coding, beat its own June-quarter forecast and raised full-year guidance on August 6. The meter that normally leads a subscription business did not keep up.
Remaining performance obligations — revenue under contract but not yet recognized — were $625.3m at June 30, against $553.2m a year earlier, growth of 13.0% against reported revenue growth of 19.1%. When the contracted book grows slower than the revenue it feeds, the quarter is drawing down work already sold. At Procore, the Carpinteria, California platform that runs project management, financials and preconstruction for general contractors and owners, the same meter ran the other way: total obligations up 24% to $1.67bn, the current portion up 22%, on revenue growth of 15.8%. Since early June, Appian's shares have gained 41.8% and Procore's 18.7%.
What Appian's quarter contained
Cloud subscription revenue reached $131.7m, up 23%. The sequence matters more than the level: 18% in the December quarter, then 25% in March, then 23%. Full-year cloud guidance of $525-529m against $437.4m delivered in 2025 leaves roughly 17-18% for the second half, and management said as much on the call, citing a dollar headwind and low-to-mid single-digit growth in non-cloud subscriptions.
The mix improvement a platform story implies did not arrive either. Professional services revenue grew 20% to $45.6m — faster than the 19% for subscriptions — holding services at about 22% of revenue, and gross margin compressed 3.1 points to 71.2%. The pressure came from the subscription line, at 84% gross margin against 86% the prior quarter on artificial-intelligence product mix; services margin actually widened to 31%.
What genuinely improved was cash. Adjusted earnings before interest, tax, depreciation and amortization came in at $16.2m against $5-8m guided, operating cash flow swung to $12.1m from an outflow of $1.9m, and Appian bought back $43.9m of stock. Cloud net annual recurring revenue expansion held at 115%. Rather than trimming, the company pulled 2027 hiring forward. "I think it might be an indication of strong pipeline that's unusually strong and also our confidence of being able to win in the current environment," chief executive Matt Calkins told analysts. US federal agencies supplied 25.3% of 2025 revenue, so appropriations timing sits under those bookings.
The price has moved faster than any of it. Appian trades at 4.36 times trailing gross profit, against 3.63x in late July and 3.07x in early May — about 42% of expansion against roughly 14% growth in gross profit itself. Its forward price-to-earnings ratio of 31.7x rests on consensus per-share earnings of $1.08 against roughly $0.53 delivered last year, and the same consensus has revenue growth fading to 7% by 2028.
The name with the better book
Procore posted its first positive quarter of operating income under generally accepted accounting principles, $4.3m against a $30.3m loss a year earlier, raised full-year revenue guidance to $1.510-1.514bn and lifted its non-GAAP operating margin target to 18.5-19%. Customers spending more than $100,000 a year number 2,871, up 14%, with gross revenue retention of 95%. In July it agreed to buy DroneDeploy, a site-capture and robotics platform, for about $845m in cash.
None of that is the cycle helping. Private nonresidential construction spending excluding data centers fell 7.9% year on year in June, and the American Institute of Architects' forecast panel cut its 2026 outlook to a 0.3% decline. "Customers are embracing our solutions, giving us more confidence in our direction, our ability to execute, and our future success," chief executive Ajei Gopal said on the July call, while describing a market uneven enough that manufacturing work is shrinking and data-center work is up 46%. Procore trades at 7.20 times trailing gross profit — below the 7.96x it carried in early May, because gross profit outgrew the shares.
The verdict
A sector tide explains part of this and not the gap. Software broadly is up nearly 40% from its April lows on a dovish read of rate expectations, by CNBC's account, and ServiceNow, the workflow vendor, rose 22.6% over the same three months. Pegasystems, Appian's closest rival for the same process-automation budget, rose 1.7%. So Appian's move is company-specific, and the company-specific evidence under it is a profitability inflection rather than a demand one: the cash swing and the earnings beat are real and dated, while bookings, mix and margin each moved the wrong way. Procore earned a re-rating on its contracted book and has not yet been given one.
Above all of it sits something no software meter forecasts. On January 8 the Supreme Court of Virginia affirmed that the 2022 jury verdict awarding Appian more than $2bn against Pegasystems is vacated, sending liability and damages back to Fairfax County Circuit Court for a full retrial.
No locatable filing says when that retrial begins. Appian's holders have spent the summer paying up for a quarter whose demand meters went backwards; the item that could dwarf all of them sits on a court calendar nobody has published.