

MasTec's Telecom Cut Sold Off EMCOR and Quanta, Which Sell Nothing to Wireless Carriers
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Five contractors lost between a seventh and a third of their market value in nine sessions from 17 August, and the trigger came from telephone companies. MasTec cut full-year Communications revenue guidance to $3.25bn on wireless spectrum equipment unavailable until 2027; Dycom pushed roughly $150m of wireless work into fiscal 2028.
Neither EMCOR nor Quanta sells to wireless carriers. EMCOR grew June-quarter revenue 19.8% and posted a record 10.6% operating margin; Quanta grew 41.1%, a fourth straight quarter of acceleration, and both raised full-year guidance on 30 July.
The group has split on price. EMCOR now trades at 8.4x forward gross profit, the cheapest of the four names measured that way, against 16.9x at Quanta — improving business at both, but only one of them cheapened.
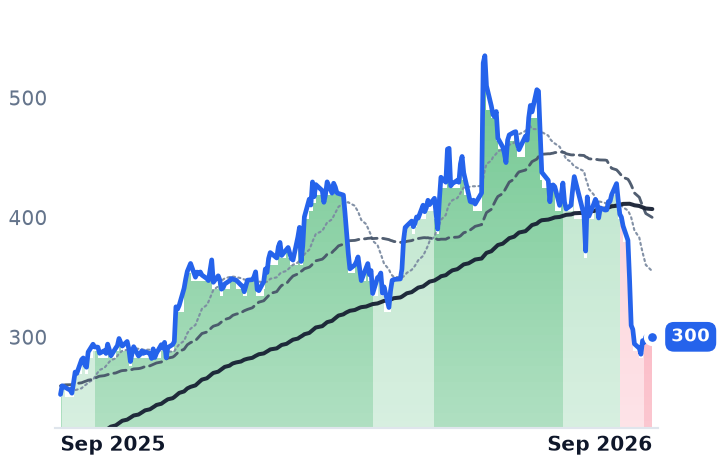
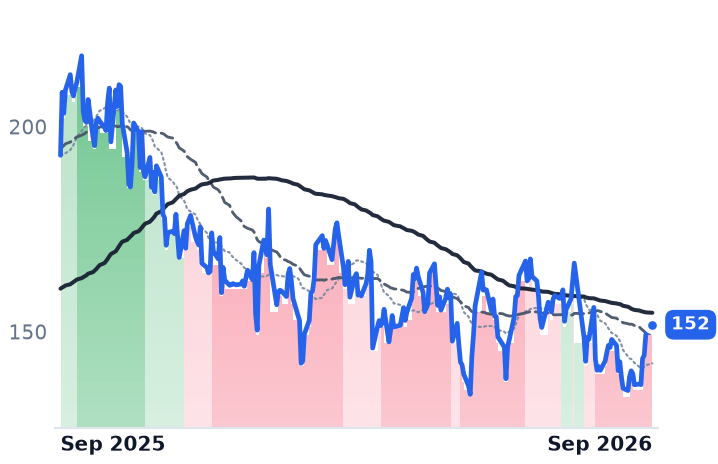
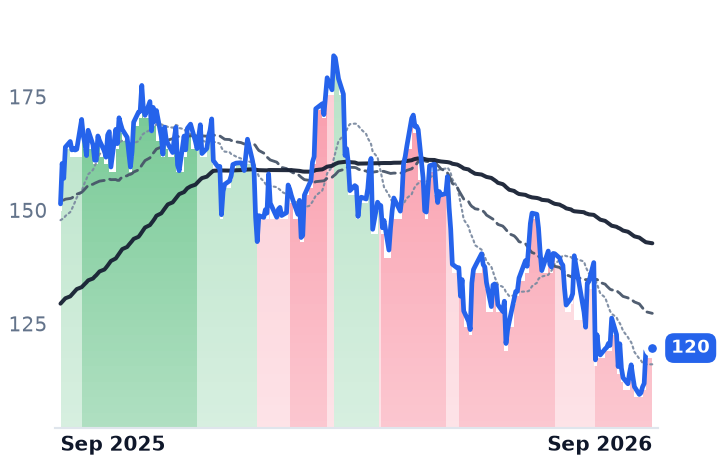
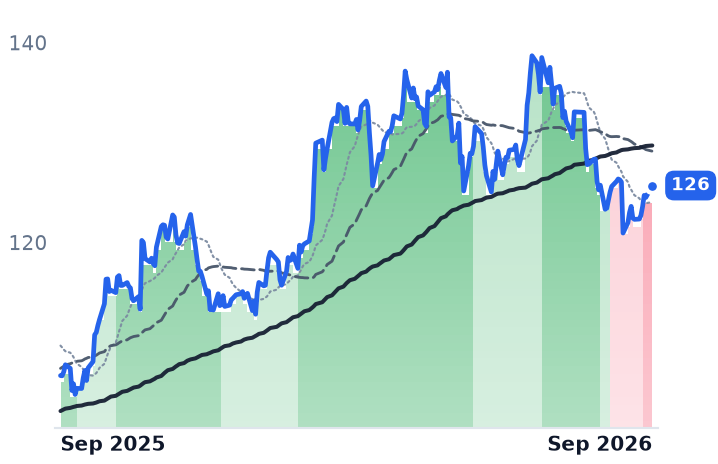
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
EME | EMCOR | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −6.9% | +22.7% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | −4.0% | +70.7% |
| Compared against · context, not the story | |||||
MTZ | MasTec | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −8.7% | +42.1% |
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | −7.6% | +74.6% |
DY | Dycom Industries | Electrical & Power Infrastructure | 🟢 Cont. Bull | −26.1% | +19.1% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +6.2% | −21.4% |
NRG | NRG Energy | Integrated Retail & Generation | 🔴 Cont. Bear | +0.2% | −21.0% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | +1.9% | +17.8% |
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −1.4% | +29.1% |
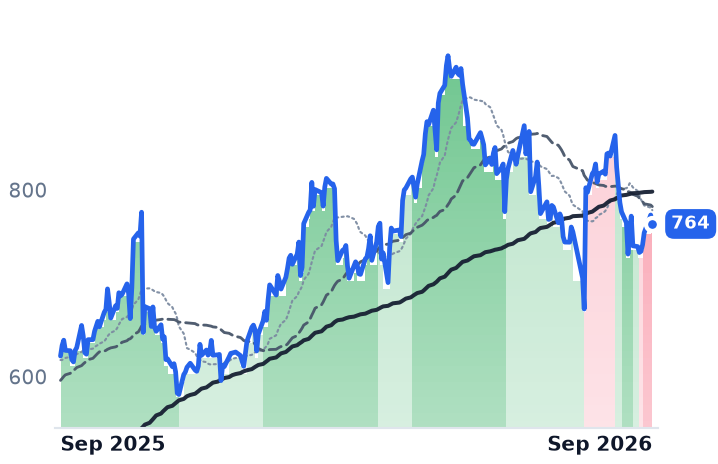
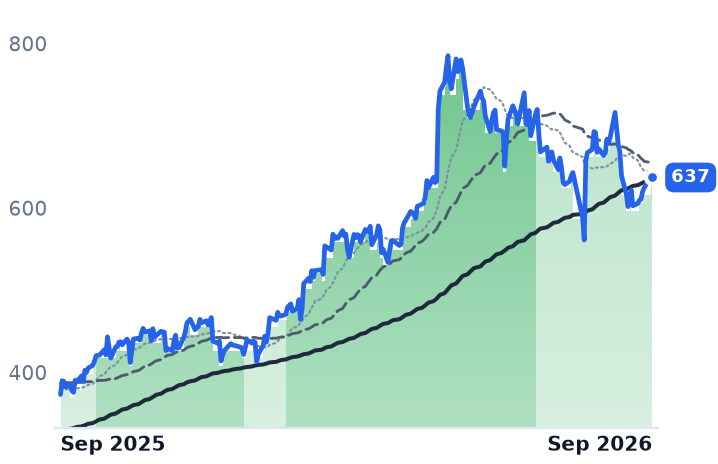
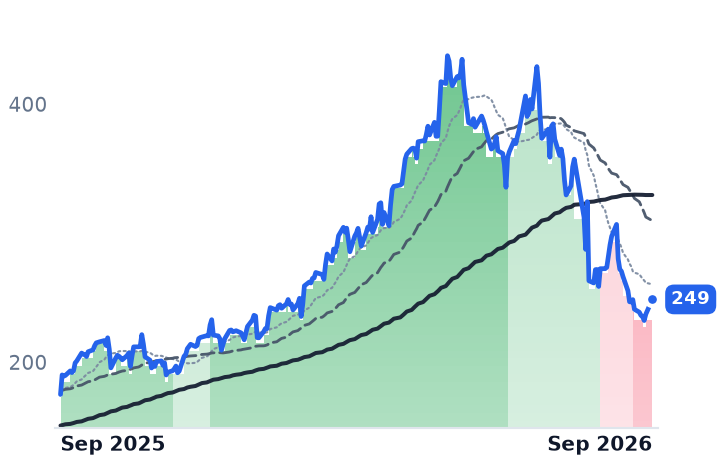
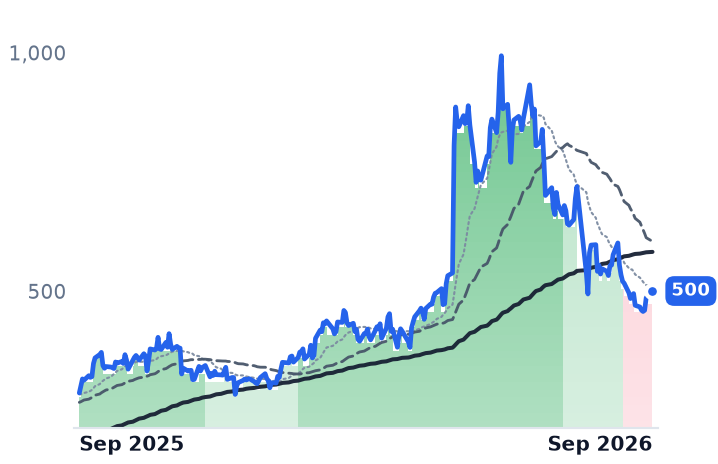
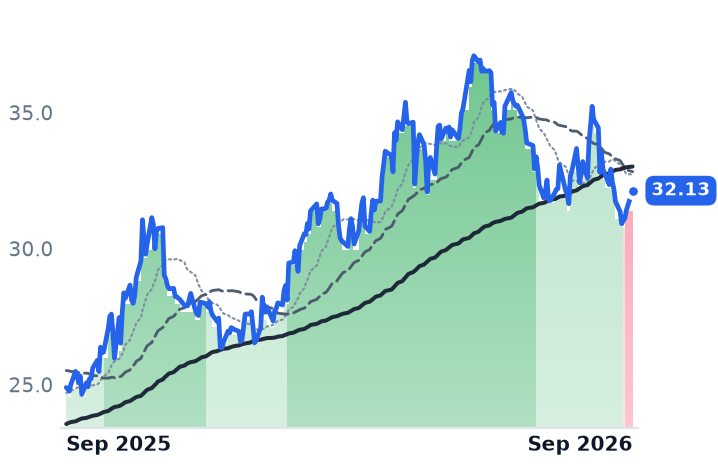
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EME | $33.7B | 23.9x | 23.2x | 1.8x | 1.7x | 9.2x | 8.4x | 14.9x | 3.5% |
PWR | $95.8B | 72.1x | 38.1x | 2.9x | 2.4x | 20.3x | 16.9x | 33.6x | 2.5% |
MTZ | $19.7B | 38.7x | 26.3x | 1.2x | 1.1x | 10.7x | 9.5x | 17.2x | 1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $15.3B | 35.6x | 25.2x | 4.5x | 3.8x | 18.9x | 16.0x | 21.1x | 3.1% |
DY | $11.8B | 37.0x | 23.7x | 1.9x | 1.5x | 9.6x | 7.9x | 13.4x | 3.7% |
VST | $51.2B | 25.3x | 17.6x | 3.2x | 2.3x | 24.7x | 17.6x | 10.9x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NRG | $25.2B | 31.3x | 13.5x | 0.7x | 0.7x | 4.2x | 4.4x | 11.5x | 1.4% |
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
BEP | $9.6B | 68.3x | — | 1.5x | 1.4x | 6.2x | 5.9x | 9.8x | -49.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EME | Revenue | +21.4% | +10.9% | +8.3% |
| EPS | +30.1% | +13.0% | +13.2% | |
PWR | Revenue | +40.6% | +16.5% | +12.9% |
| EPS | +57.5% | +17.5% | +16.7% | |
MTZ | Revenue | +29.2% | +19.1% | +15.4% |
| EPS | +45.5% | +34.3% | +30.0% | |
STRL | Revenue | +71.5% | +21.2% | +17.3% |
| EPS | +91.2% | +28.0% | +20.6% | |
DY | Revenue | +17.1% | +40.1% | +11.3% |
| EPS | +39.5% | +47.1% | +20.3% | |
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.6% | +15.4% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
BEP | Revenue | +3.8% | +9.0% | −3.4% |
| EPS | +14.0% | −11.7% | +9.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Between 17 August and the first days of September, five contractors that build electrical systems, transmission lines and data-center sites shed between a seventh and a third of their market value in nine sessions. Two earnings reports did it, and neither was about data centers.
MasTec, the Coral Gables infrastructure contractor whose segments run from wireless towers to gas pipelines, cut its full-year Communications revenue guidance to $3.25bn with margins about a point below the prior year, blaming wireless spectrum equipment that will not be available until 2027 and deferred wireline projects. The shares fell 18.5% to $264.36 despite record backlog of $21.4bn, up 30%, and raised full-year earnings guidance of $9.30 a share. Days later Dycom Industries, which lays fiber and builds wireless sites for telephone and cable carriers, fell about 13% after shifting roughly $150m of wireless revenue into fiscal 2028. Its fiber-to-the-home revenue had risen nearly 60% in the first half.
That is a carrier capital-spending problem, and it was then applied to companies with no carriers among their customers. MasTec's own non-telecom segments accelerated in the same quarter — Power Delivery revenue up 20%, Clean Energy up 43% — and the two largest names dragged down by the episode sell almost nothing to a phone company.
What the two protagonists actually reported
EMCOR Group, the Norwalk mechanical and electrical trade contractor with 44,000 employees, grew June-quarter revenue 19.8% to $5.155bn and posted a record 10.62% operating margin. Remaining performance obligations — signed work not yet billed — hit $17.14bn, up 44% and almost entirely organic. "Our strong performance during the first half of 2026, combined with the visibility provided by our record RPOs, supports a substantial increase to our full year 2026 earnings guidance," chief executive Anthony Guzzi told investors on the second-quarter call. The 30 July raise took full-year earnings to $32.00-33.25 a share from $29.75-30.75.
The margin comes from the construction trades, not the maintenance book: Electrical and Mechanical Construction together billed $3.96bn at a 13.1% operating margin, while the Building Services facilities book grew 5.6% at 7.6%. Electrical Construction margin widened 210 basis points to 13.9% on network and communications work up 45% — that is data-center and campus wiring, sold to owners rather than to carriers.
Quanta Services, the Houston utility contractor with 69,500 employees, grew revenue 41.1% to $9.557bn, a fourth consecutive quarter of acceleration, with gross margin 296 basis points wider than a year earlier. It lifted full-year revenue guidance to $39.3-39.7bn. Its record $53.4bn backlog contains $19.8bn of estimated master-service-agreement volume above the $33.6bn of signed obligations, so the headline number is part forecast. Asked whether crews were the binding constraint, chief executive Earl Austin said on 30 July: "We're nowhere near capacity."
The customer is spending more, not less. Alphabet, Amazon, Microsoft and Meta together plan roughly $725bn of 2026 capital expenditure, up 77% from $410bn.
The group no longer trades as one thing
From May highs, EMCOR is down 18.1% and Quanta 18.6%. Sterling Infrastructure, the Texas site-development contractor serving data-center and semiconductor clients, is down 49.6% after growing revenue 90% to $1.168bn at a 19.8% operating margin; Dycom is down 43.9% and MasTec 43.2%. All five have bounced off the early-September low, EMCOR by 5.5% and Quanta by 6.2%.
Measured against a year of gross profit, EMCOR is the cheapest of the four at 8.4x forward, ahead of MasTec at 9.5x, Sterling at 16.0x and Quanta at 16.9x. EMCOR's trailing reading of 9.2x is down from 12.1x on 7 May while its gross profit grew 22.6% — the multiple did the falling. Quanta at 33.6x trailing enterprise value to earnings before interest, taxes, depreciation and amortization remains roughly twice EMCOR's level even after the decline.
Rates explain the August leg down: the 30-year Treasury yield sat at 5.245% in early September and a hot payrolls print pushed the implied probability of a September rate rise to 58%, which is hostile to contractors whose signed work converts over a longer horizon. But these shares rose into that print, so the September stabilization reads more like an oversold bounce than a verdict on rates.
The honest split is this. At EMCOR, growth held near 20% for a third straight quarter and the price fell by roughly a fifth; nothing in the disclosures explains the gap. At Quanta the business improved too, but it still carries the highest price per dollar of gross profit of the four, so its de-rating took it back toward its peers rather than below them. The only order-flow warning anywhere in the group came from Sterling, whose management flagged softer third-quarter awards and a possible sequential backlog decline, and called it timing rather than demand.
EMCOR spent about $750m upfront this year buying union electrical contractors, and Quanta bought a permitting and right-of-way specialist to shorten interconnection timelines. Companies short of work do not buy crews.