

Knife River's Record $1.2bn Backlog Is 85% Public Work at Thinner Margins Than Last Year
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The best operating quarter in American aggregates this summer belongs to the stock with the deepest drawdown, and the reason is what the company sells rather than how much of it moves. Knife River shipped 14% more stone at mix-adjusted prices up 8% — better on both counts than Vulcan or Martin Marietta — and still watched operating income fall 7.9%. Its largest revenue line is percentage-of-completion paving, not quarried rock, which is why 12.6% revenue growth produced a 17.3% gross margin against Vulcan's 29.0%.
Management raised full-year revenue guidance to $3.40bn-$3.60bn and reaffirmed adjusted earnings before interest, taxes, depreciation and amortization at $520m-$560m: more work, the same profit. The June 30 backlog is a record and, by the company's own disclosure, carries slightly lower margins than a year ago — aimed at lettings funded by an authorization that expires September 30.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
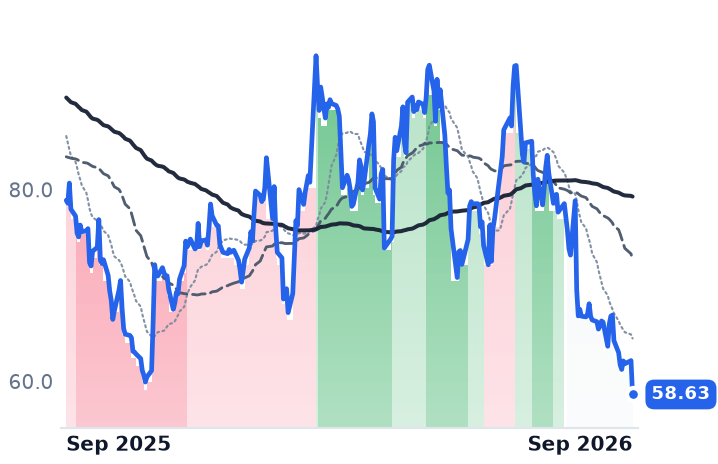
KNF | Knife River | Aggregates & Concrete | 🌱 Emerging Bull | −12.1% | −25.7% |
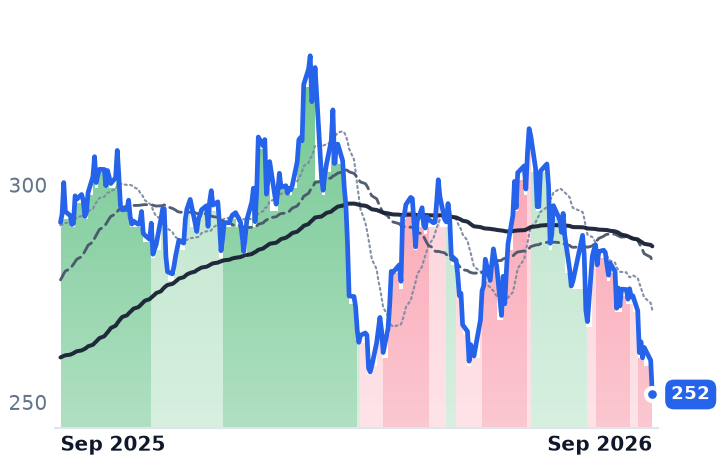
VMC | Vulcan Materials | Aggregates & Concrete | ⚠️ Emerging Bear | −11.6% | −13.6% |
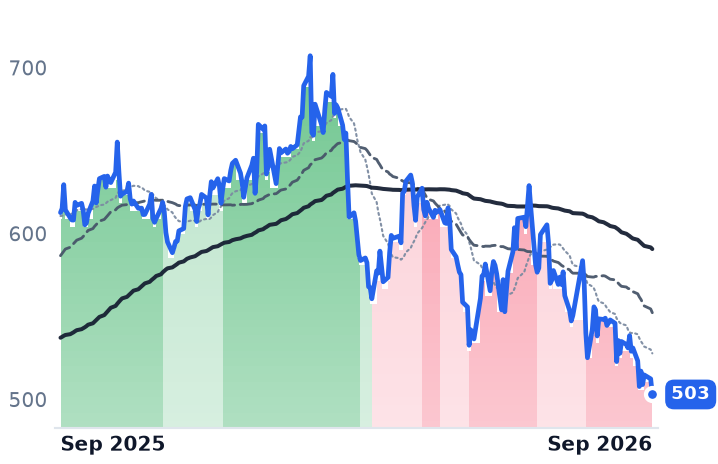
MLM | Martin Marietta Materials | Aggregates & Concrete | ⚠️ Emerging Bear | −8.3% | −17.9% |
| Compared against · context, not the story | |||||
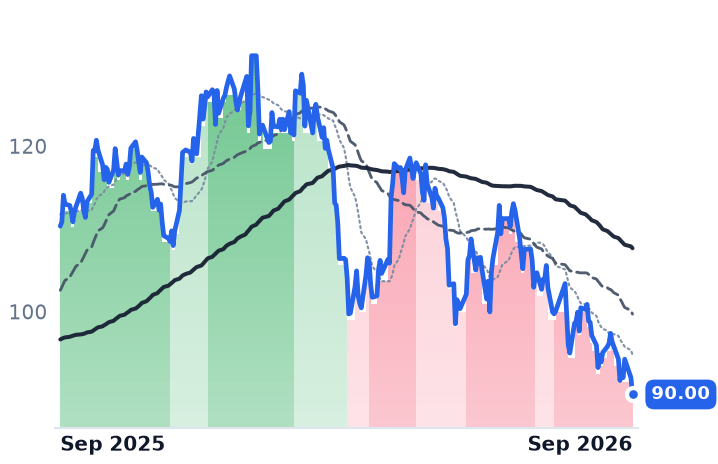
CRH | CRH | Integrated Cement & Materials | ⚠️ Emerging Bear | −10.3% | −18.4% |
EXP | Eagle Materials | Specialty Building Products | 🔴 Cont. Bear | −11.2% | −18.2% |
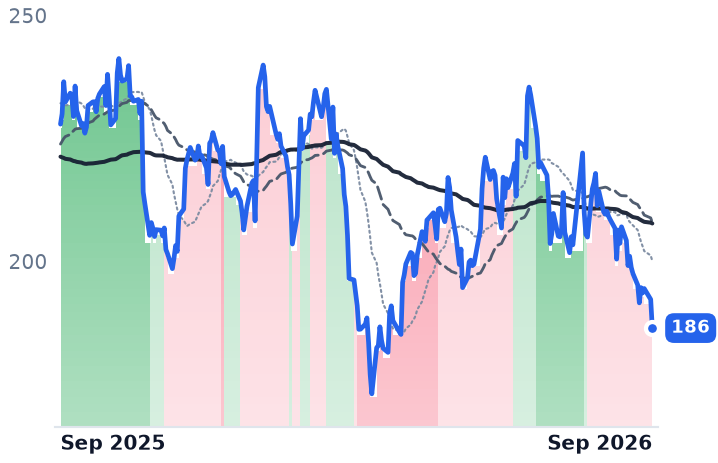
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KNF | $3.3B | 23.6x | 19.9x | 1.0x | 0.9x | 5.6x | 5.3x | 11.2x | 1.3% |
VMC | $32.4B | 29.4x | 27.3x | 4.0x | 4.0x | 14.6x | 14.5x | 14.5x | 3.2% |
MLM | $30.2B | 12.3x | 27.6x | 4.5x | 4.2x | 16.0x | 14.8x | 17.3x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRH | $69.0B | 13.7x | 17.3x | 1.2x | 1.7x | 3.5x | 4.9x | 7.9x | 4.2% |
EXP | $6.1B | 14.6x | 15.1x | 2.7x | 2.6x | 9.4x | 9.3x | 9.6x | 3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KNF | Revenue | +11.2% | +5.7% | +3.9% |
| EPS | +11.5% | +21.6% | +8.9% | |
VMC | Revenue | +2.3% | +6.0% | +6.8% |
| EPS | +8.8% | +17.4% | +16.6% | |
MLM | Revenue | +8.8% | +7.1% | +8.3% |
| EPS | +0.5% | +19.3% | +17.1% | |
CRH | Revenue | +5.9% | +5.1% | +6.8% |
| EPS | +6.8% | +12.7% | +12.0% | |
EXP | Revenue | +0.5% | +1.9% | +5.8% |
| EPS | −9.4% | −0.1% | +13.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Knife River sold 10.0 million tons of aggregates in the June quarter, 14% more than a year earlier and at mix-adjusted prices up 8%. It earned less money doing it. Operating income fell 7.9% to $81.1m while revenue rose 12.6% to $938.6m, and the company raised full-year revenue guidance to $3.40bn-$3.60bn while reaffirming adjusted EBITDA at $520m-$560m — more work booked for the same profit.
That arithmetic is the company, not an accident. Knife River, spun out of MDU Resources and run from Bismarck, North Dakota, quarries stone and makes asphalt and ready-mix like its larger peers, but its biggest revenue line is contracting services: heavy-civil paving, grading and site work billed as the job progresses, for state and municipal customers. Contracting revenue grew 20% in the quarter, and the June 30 backlog reached a record of roughly $1.2bn, of which about 85% is publicly funded work, mostly streets and highways. The same disclosure says margins on that backlog are expected to be slightly lower than on the backlog a year ago. Bigger and thinner at once.
Why the margin is structurally lower
A quarry is a local freight-radius franchise: crushed stone does not travel far economically, so price is set submarket by submarket and drops toward the bottom line. Paving is bid work with fuel, crews and weather between the award and the profit. Knife River's 17.3% gross margin in the June quarter sits well below Vulcan's 29.0% for the same three months, and its seasonality is a different animal too — the March quarter produced $410.1m of revenue, a gross loss of $2.8m and an operating loss of $84.2m. Management assigned roughly $24m of the June quarter's profit shortfall to higher diesel costs, weather delays and the type and timing of contracting work, and guided second-half contracting margins merely in line with last year's.
"With the majority of the construction season still ahead of us, we have opportunities to execute on our $1.2 billion contracting services backlog, driving volume and gross profit improvement in all of our product lines," chief executive Brian Gray said with the second-quarter results in August.
The majors have the same problem from the other side
Vulcan Materials, the largest US aggregates producer, lifted mix-adjusted prices 5% on shipments up 1% and still saw operating income fall 9.7%, with cash gross profit per ton at $12, up 14 cents. Martin Marietta, the number two, grew organic shipments 2.3% and organic pricing 3.7%; its reported operating income fell 17.2%, though a $52m inventory step-up from purchase accounting on the Quikrete and New Frontier assets did most of that damage. All three are converting price into less profit than a year ago, and all three named energy.
The market is paying for the difference in mix. Knife River trades at 11.2 times trailing enterprise value to EBITDA, against 14.5 times at Vulcan and 17.3 times at Martin Marietta, and at 19.9 times forward earnings versus 23.6 times trailing. Its trailing free-cash-flow yield of 1.31% is less than half Vulcan's 3.17% — working-capital-heavy contracting converts worse. Vulcan's 27.3 times forward earnings is a real compression against the roughly 30-35 times recorded in May, but it is close to its own 29.4 times trailing, which means almost no growth is being underwritten.
On September 9 all three closed at 52-week lows, with Knife River 37.6% below its high, and the analyst calls split the group: Wells Fargo cut Vulcan to underweight with a $254 target while raising Martin Marietta to overweight at $609; JPMorgan moved Knife River to underweight.
The verdict
Knife River's discount is earned, and it is a business-mix discount rather than a mispricing: two-thirds of the majors' gross margin, a third of Vulcan's cash yield, and a first quarter that loses money by design. What the discount does not explain is the ranking — the name with the best volume and price prints of the three has the deepest drawdown of the three. The swing factor is whose demand is contracted. Vulcan and Martin Marietta sell into awards already funded; Knife River's growth is the next round of lettings.
The federal surface transportation program authorized by the Infrastructure Investment and Jobs Act expires on September 30. The House Transportation and Infrastructure Committee approved the five-year, $580bn BUILD America 250 Act by 62-2 on May 22, but it has not reached the House floor and the Senate has neither released a proposal nor set a timeline. Every such bill since 1991 has needed a stopgap. A stopgap is fine for a quarry that already has the order; it is the whole question for the crew waiting on the next letting.