

Sherwin-Williams Raised Paint Prices 8% on September 1 and Expects 60-70% to Stick
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A coatings maker sells a spread, and both halves of it are moving the wrong way at once. Crude-derived resins and solvents are inflating with Brent at $97.41 a barrel, titanium dioxide took four price increases in the first half on sulphur costs up more than 90%, and the offsetting price list is administered on contracts that push realization into 2027.
Sherwin-Williams' revenue growth has accelerated four quarters running to 7.5%, yet its gross margin slipped 21 basis points in the June quarter — the squeeze showing up at the top of the income statement before it reaches earnings. PPG's chief executive said the company covers about 90% of its cost inflation with price today.
The one coatings name in an established uptrend, Axalta, is there because of an approved all-stock merger with AkzoNobel, not because collision-repair volumes turned; repairable claims fell 9.7% in 2025.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
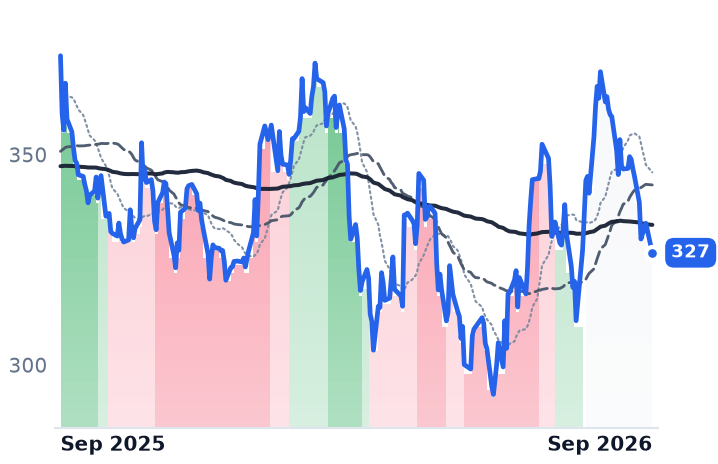
SHW | The Sherwin-Williams | Paints & Coatings | 🔴 Cont. Bear | −9.9% | −12.5% |
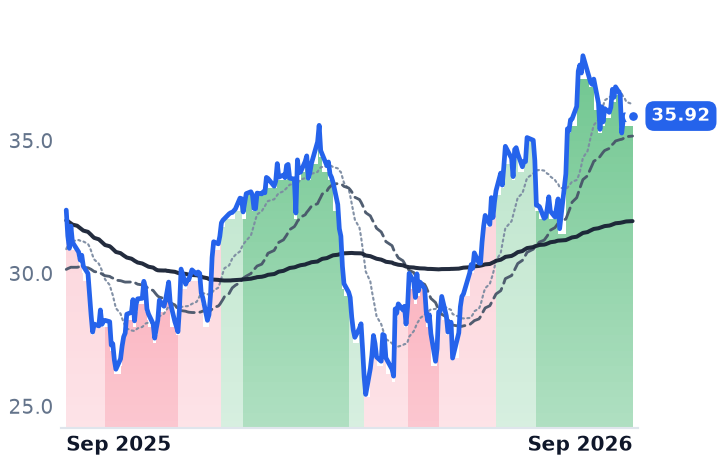
AXTA | Axalta Coating Systems | Paints & Coatings | 🌱 Emerging Bull | −4.4% | +10.9% |
| Compared against · context, not the story | |||||
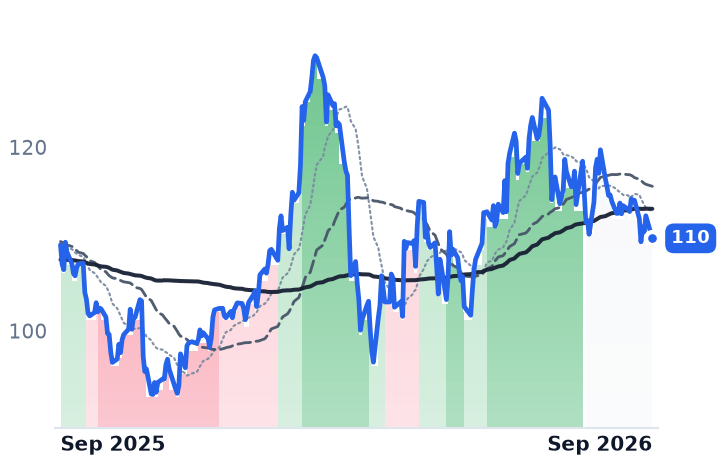
PPG | PPG Industries | Paints & Coatings | 🌱 Emerging Bull | −5.6% | +0.7% |
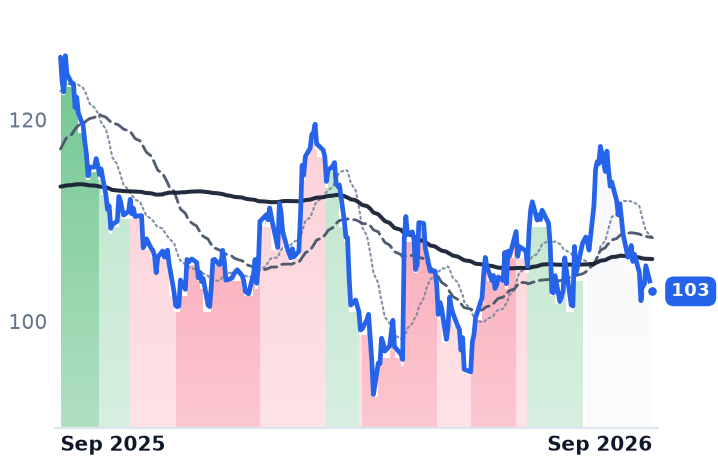
RPM | RPM International | Adhesives, Sealants & Construction | 🔴 Cont. Bear | −10.4% | −18.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHW | $79.3B | 29.8x | 27.0x | 3.2x | 3.2x | 6.6x | 6.4x | 20.9x | 4.1% |
AXTA | $7.6B | 21.9x | 13.5x | 1.5x | 1.5x | 4.6x | 4.5x | 11.1x | 6.5% |
PPG | $24.5B | 15.7x | 14.0x | 1.5x | 1.5x | 3.7x | 3.6x | 10.9x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RPM | $12.2B | 18.2x | 17.4x | 1.6x | 1.6x | 3.8x | 3.8x | 13.4x | 4.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SHW | Revenue | +6.8% | +4.5% | +4.6% |
| EPS | +6.5% | +12.3% | +10.9% | |
AXTA | Revenue | +2.3% | +3.3% | +2.7% |
| EPS | +6.5% | +8.0% | +7.7% | |
PPG | Revenue | +6.7% | +3.3% | +2.9% |
| EPS | +3.4% | +9.4% | +9.3% | |
RPM | Revenue | +6.9% | +5.3% | +4.0% |
| EPS | +6.1% | +7.0% | +12.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Sherwin-Williams put a new price list into its roughly 5,000 North American stores on September 1 — an 8% architectural paint increase — and told investors to expect its historical realization rate of 60% to 70%, with the remainder phasing into 2027 through contract customers.
That lag is the business. A paint company sells a spread between an input basket it does not control and a price it sets by letter rather than by quote, on gallons that move with existing-home turnover. Both halves of the basket are now inflating on supply disruption. Brent crude stood at $97.41 a barrel on September 8, up 11% in a month and 47% on the year after attacks halted operations at Saudi energy facilities including the 400,000-barrel-a-day Jazan refinery; resins, solvents and additives are crude derivatives. Titanium dioxide, the pigment that whitens the can, went through four rounds of increases in the first half totaling roughly $450 to $500 a tonne, driven by sulphur prices up more than 90% this year — the sulphuric-acid route consumes three to four tonnes of acid per tonne of pigment. Over the past month Sherwin-Williams fell 11.6%, PPG 8.1% and Axalta 5.9%.
The squeeze arrives at the gross line first
Sherwin-Williams, which develops paint and sells it mostly through its own stores to professional contractors, is not obviously a company in trouble. Revenue growth has accelerated four quarters running, from 3.2% year-on-year to 7.5% in the June quarter, and operating margin widened to 18.13% from 17.41%. But gross margin went the other way, slipping to 49.17% from 49.38%. Part of the top-line acceleration is bought rather than earned: Consumer Brands grew mid-teens with the contribution from Suvinil, the Brazilian decorative paints business acquired from BASF for $1.15bn and closed last October, and only mid-single digits without it.
The gallons are real but modest. Paint Stores Group same-store sales rose 4.2%, split between low-single-digit price increases and low-single-digit volume growth, with residential repaint up a mid-single-digit percentage. The demand meter underneath has not turned: existing-home sales edged down 1.7% in July and have never recovered from the 30-year low of 2023. Management's guidance assumes no broad demand recovery. "We know growth will need to come from what we do, not from what the market gives us," chief executive Heidi Petz told investors on the July 28 call. Her chief financial officer, Ben Meisenzahl, was blunter about the cost side: "We are seeing the impact of higher oil and related cost pressures... We expect inflation in our raw material basket to be up in the high single digit range in the second half."
PPG, which sold its US and Canadian architectural business — the Glidden and Pittsburgh Paints brands — to American Industrial Partners for $550m in December 2024 and is now an industrial, aerospace and auto-OEM mix, put a number on the industry's recovery rate. "We covered about 90% of our cost of goods sold inflation with pricing, and we expect to reach 100% coverage by the fourth quarter," chief executive Tim Knavish said on July 29. Ninety percent coverage is under-recovery, described as progress.
The one uptrend belongs to a merger
Axalta is the only one of these names with a positive twelve-month return and the only one whose 50-day average has sat above its 200-day since early July. Its June quarter was genuinely good: Refinish sales up 6% to $545m, record adjusted profit before interest, tax, depreciation and amortization of $305m, and net leverage of 2.2x, the lowest in company history. "We far exceeded our normal run rate with more than 1,900 new net Body shops secured in the first half," chief executive Chrishan Villavarayan said on July 28. Reported operating income still fell 17.3%, on merger costs.
Those merger costs are the point. Shareholders of both companies approved an all-stock merger of equals with AkzoNobel on August 5 at a fixed 0.6539 ratio, tethering Axalta's price to AkzoNobel's and to antitrust review — a US Federal Trade Commission second request, with reporting that an in-depth European probe over powder coatings and refinish overlap may follow. Underneath the ratio, the unit meter shrinks: repairable claim volume fell 9.7% in 2025, and management expects collision claims down mid-single digits, with back-half volume resting on body-shop wins.
What the businesses earn
The part of this the businesses earn is the margin: cost programs, share gains, an acquisition, and price letters that stick two-thirds of the time. What none of them earns is a demand inflection, because there isn't one — the gallon count is crawling and the repair count is falling. Sherwin-Williams still trades at 29.8 times trailing and 27.0 times forward earnings, against 31.6x at the end of last year and against PPG at 15.7x trailing and 14.0x forward; barely two turns have come out while the business improved, which leaves the multiple, rather than the operations, carrying the risk. Axalta's 11.1 times trailing enterprise value to that same profit measure is supported by the numbers, but its share price now answers to a merger ratio and a regulator.
The next paint price increase will be decided in the Strait of Hormuz rather than in the housing market, and it will reach contract customers sometime in 2027.