

Quanta's $53.4bn Backlog Omits 95% of Its Generation Work as EMCOR's Converts Slower
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two of the largest electrical contractors in the AI buildout reported record order books on the same day in July, raised guidance, and have since traded down about a fifth from their May levels. The order books did not thin — but the two most-quoted measures of them do not mean what the headlines assume.
Quanta's backlog reached $53.4bn while its remaining performance obligations — the portion meeting the accounting definition of signed work — were $33.6bn, and management says roughly 95% of its generation work sits outside both. EMCOR's obligations hit a record $17.14bn, up 44% and 95% organic, but now convert over a longer horizon: about 75-76% within twelve months against 85% historically.
Revenue accelerated at Quanta to 41.1% growth and held near 20% at EMCOR; both lifted full-year guidance. What changed is when the signed work pays, and what that duration is worth at a 5.25% long bond.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
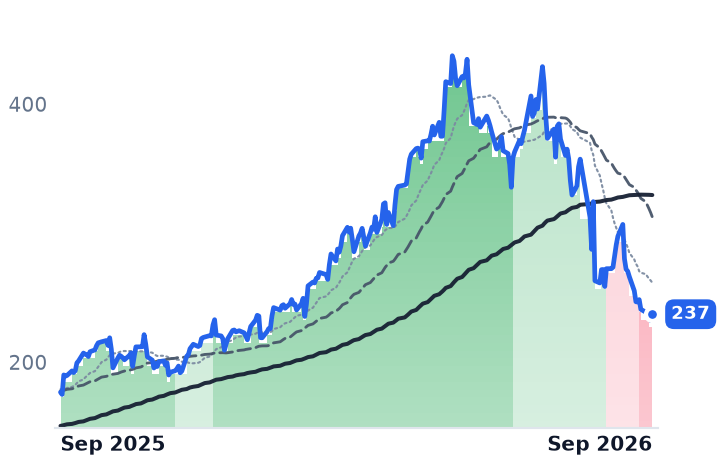
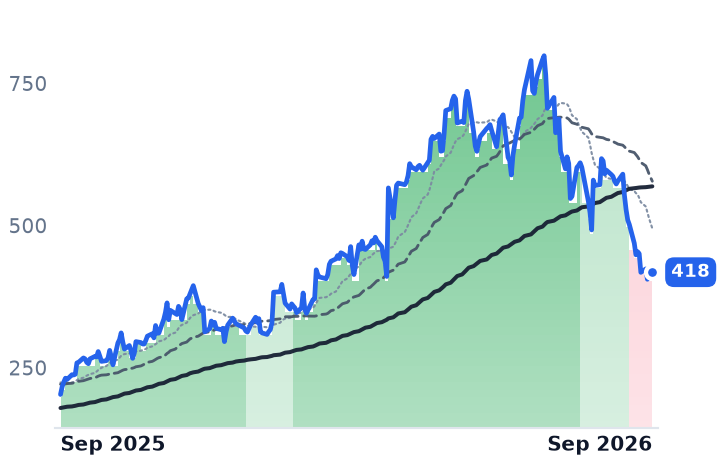
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | −5.9% | +66.4% |
EME | EMCOR | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −8.0% | +21.5% |
| Compared against · context, not the story | |||||
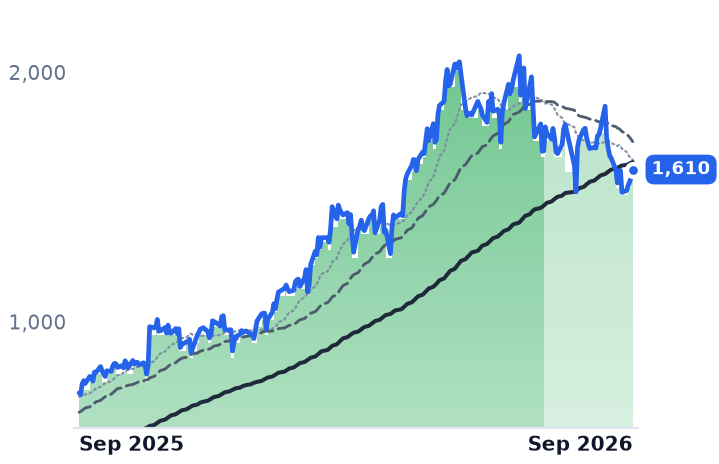
IESC | IES | MEP & Building Systems | 🟢 Cont. Bull | −57.2% | −10.6% |
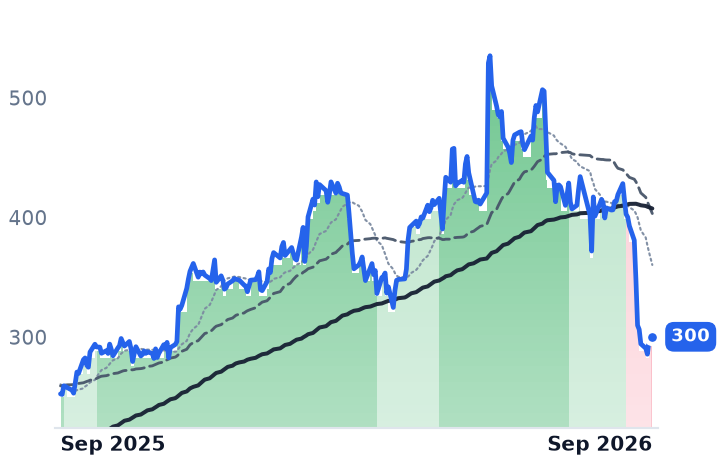
PRIM | Primoris Services | Energy & Power Project Solutions | ⚠️ Emerging Bear | −7.9% | −35.7% |
MTZ | MasTec | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −13.0% | +34.2% |
AGX | Argan | Energy & Power Project Solutions | 🟢 Cont. Bull | −29.1% | +105.9% |
FIX | Comfort Systems USA | MEP & Building Systems | 🟢 Cont. Bull | −5.2% | +125.2% |
DY | Dycom Industries | Electrical & Power Infrastructure | 🟢 Cont. Bull | −26.1% | +18.9% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.5% | +19.7% |
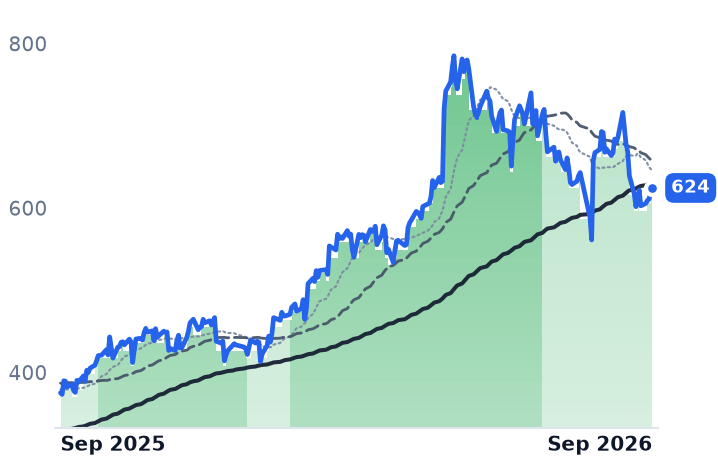
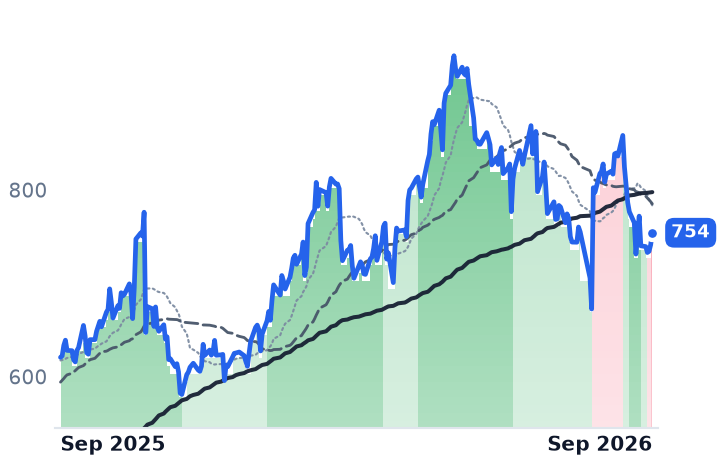
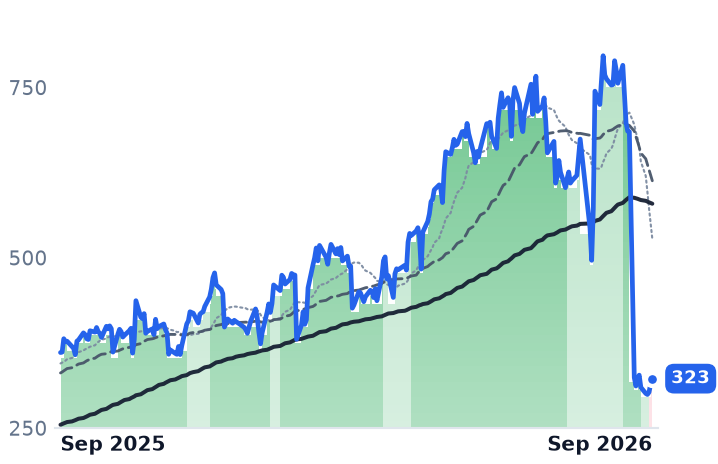
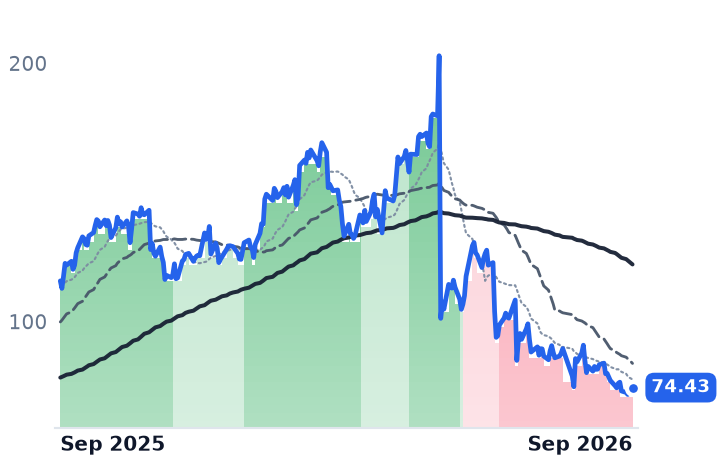
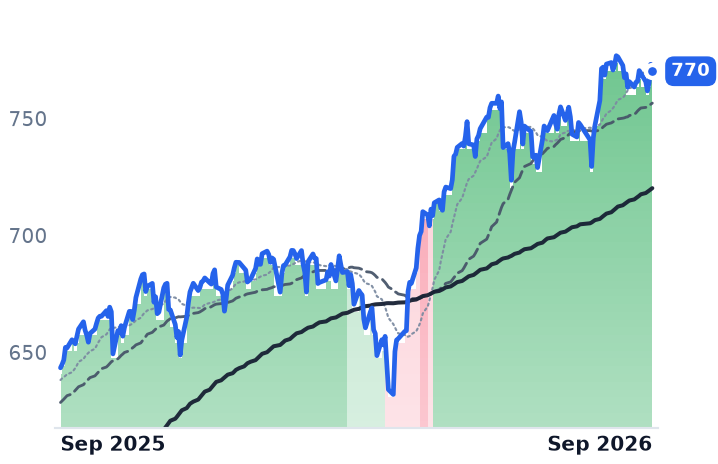
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $93.9B | 70.6x | 37.3x | 2.9x | 2.4x | 19.9x | 16.5x | 32.9x | 2.5% |
EME | $33.3B | 23.6x | 22.9x | 1.8x | 1.6x | 9.1x | 8.3x | 14.7x | 3.5% |
IESC | $12.9B | 28.3x | 27.9x | 3.2x | 3.0x | 12.5x | 11.7x | 21.4x | 1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PRIM | $4.2B | 29.9x | 34.9x | 0.6x | 0.6x | 6.7x | 6.7x | 16.6x | 2.1% |
MTZ | $21.1B | 41.4x | 28.6x | 1.3x | 1.2x | 11.4x | 10.0x | 21.9x | 1.2% |
AGX | $7.0B | 43.1x | 41.9x | 6.7x | 5.5x | 32.3x | 26.3x | 35.6x | 6.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIX | $58.3B | 40.7x | 33.8x | 5.2x | 4.5x | 20.2x | 17.5x | 29.0x | 3.7% |
DY | $11.8B | 37.0x | 23.7x | 1.9x | 1.5x | 9.6x | 7.9x | 13.4x | 3.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PWR | Revenue | +40.6% | +16.7% | +12.5% |
| EPS | +57.5% | +17.8% | +16.7% | |
EME | Revenue | +21.4% | +10.9% | +8.3% |
| EPS | +30.1% | +13.0% | +13.2% | |
IESC | Revenue | +27.7% | +48.1% | +18.8% |
| EPS | +76.1% | +16.3% | +17.1% | |
PRIM | Revenue | −3.4% | +12.0% | +10.4% |
| EPS | −60.0% | +138.8% | +21.4% | |
MTZ | Revenue | +30.5% | +20.3% | +14.5% |
| EPS | +43.0% | +34.8% | +28.0% | |
AGX | Revenue | +12.1% | +36.0% | +25.1% |
| EPS | +65.8% | +42.8% | +28.8% | |
FIX | Revenue | +47.4% | +20.2% | +17.6% |
| EPS | +86.6% | +22.8% | +23.4% | |
DY | Revenue | +17.1% | +40.1% | +11.3% |
| EPS | +39.5% | +47.1% | +20.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Quanta Services books hundreds of millions of dollars a quarter of data-center electrical work that never appears in its backlog, and management says roughly 95% of the power generation it expects to build is not in there either.
That matters because the order book is the number investors trade these companies on. Quanta, a Houston specialty contractor that self-performs 80-85% of its work building transmission lines, substations and distribution for utilities and technology customers, and EMCOR Group, the Norwalk, Connecticut mechanical-and-electrical contractor that wires and cools data halls and separately runs a recurring building-services business, both reported record signed work on July 30 and both raised full-year guidance. Both stocks are roughly a fifth below their May 6 levels, over a stretch in which the S&P 500 exchange-traded fund rose 5.0%. Late August took the pair down further before they steadied into early September; the question the order books answer is whether contracted work is thinning, or whether the same work is simply getting paid later.
Two numbers, one book
Quanta's June-quarter backlog was a record $53.4bn against remaining performance obligations of $33.6bn, per the company's release. The $19.8bn gap is the master-service-agreement layer: estimated orders under multi-year utility agreements, including estimated renewals, which do not qualify as accounting performance obligations. Neither figure is the ceiling. Quanta admits a data-center project to backlog only once a limited notice to proceed exists, and its data-center master agreements book and bill within the quarter without ever passing through the reported number. Technology and load-center work is now 15-20% of revenue.
The income statement is doing what the mechanism implies. Revenue grew 41.1% to $9.557bn, the fourth straight quarter of acceleration from 15.6% a year ago, and gross margin widened 296 basis points to 16.2%. Guidance went up, to revenue of $39.3-39.7bn. Asked on the July 30 call whether crews were the binding constraint, chief executive Earl "Duke" Austin said: "We're nowhere near capacity." The company spends about $250m a year training craft labor against a four-year journeyman pipeline.
EMCOR's book got longer
EMCOR's remaining performance obligations hit a record $17.14bn, up 44% year over year with 95% of that organic — against first-half revenue of $9.78bn, bookings of roughly 1.4 times what it billed. Operating margin reached a record 10.6% and full-year earnings guidance rose about 10% to $32.00-33.25 a share.
The honest complication is inside the mix. Electrical construction, the scarce-labor business, grew 24% and added 210 basis points of margin to 13.9%. Mechanical grew faster, at 31%, and lost 110 basis points to 12.5% as roughly 9-10% of that book moved to guaranteed-maximum-price and construction-manager forms where equipment passes through at thin markup. And the work pays out later. "Historically, we would say that 85% or so of our RPOs burn in 12 months. where we're sitting today, it's more like 75% or 76%," chief financial officer Jason Nalbandian told investors on July 30, citing project size and the water and wastewater mix. Management also said the record quarterly margin is unlikely to repeat. EMCOR bought five union electrical contractors this year — B&B Electric, Sidney Electric, Giles, Schmidt Electric and Connelly Electric, together $625m of revenue for about $750m upfront — buying crews rather than backlog.
What actually broke, and where
The fixed-price accident the sector fears did happen — at Primoris Services, the pipeline and renewables contractor, which cut 2026 adjusted earnings guidance to $4.80-5.00 from $5.80-6.00 on renewables cost overruns. It is the only name in this group down over twelve months.
IES Holdings, the electrical contractor serving data centers and housing, looks like a catastrophe and is not one. Its unadjusted price series shows a 52.7% one-day drop on August 24; the company distributed a two-for-one stock split after the close on August 21. Its June quarter grew revenue 40% with backlog of $4.5bn, and it trades at a higher price per dollar of gross profit than EMCOR does.
The verdict
Nothing in either order book earns the decline. Quanta's price against a dollar of its trailing gross profit fell from about 29.3x in early May to 19.86x while that gross profit grew 16% — the multiple did the falling. Part of that is a rational de-rating of an extreme: at 32.9x enterprise value to EBITDA and 37.3x forward earnings, Quanta is priced far above EMCOR on both measures, and consensus 2026 earnings sit inside management's own guidance rather than above it. EMCOR is the cleaner case, at 22.9x forward earnings — almost exactly where it stood in May, because guidance rose as the shares fell.
What the fall does earn is duration. EMCOR's signed work converts over a longer horizon than it used to, Quanta's largest transmission corridors are still in engineering, and a 30-year Treasury yield above 5.2% discounts cash that arrives later. No company-specific disclosure explains the August leg down; the likelier reading is a rate-and-sector repricing that arrived while the order books were still growing.
The biggest scopes in Quanta's book are not crews in the field but drawings — its largest corridors do not reach field execution until the second half of 2027. Until then, the buildout pays its contractors on paper, and paper is what a long bond marks down first.