

West's Sales Rose on Upgraded Stoppers, Not More of Them; Stevanato Is Still Building
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
West Pharmaceutical's growth is a repricing rather than a volume boom. Its high-value injectable components — upgraded elastomer seals and plungers — grew 18.4% organically in the June quarter and now make up 49% of company sales, while its contract-manufacturing arm grew 0.8%. The driver is a European sterility rule pushing drugmakers to convert commodity stoppers into premium ones; West sizes the candidate pool at roughly 6 billion components.
Stevanato bills the mirror meter and is not being paid for it yet. Its high-value solutions grew 16%, but the Engineering segment that sells filling lines shrank, its Indiana plant does not fully ramp until end-2028, and free cash flow was minus €32m in the quarter. West trades at 19.6x trailing gross profit against Stevanato's 13.5x, and about two-thirds of West's advance off its 2025 low is multiple expansion rather than earnings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
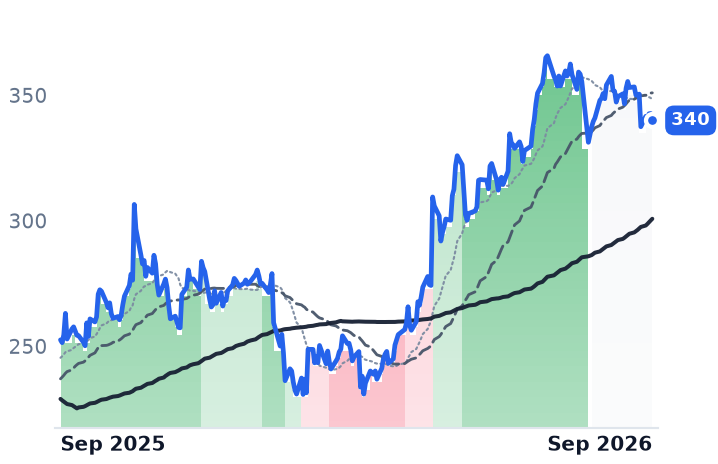
WST | West Pharmaceutical Services | Drug Delivery & Containment | 🟢 Cont. Bull | −4.9% | +34.6% |
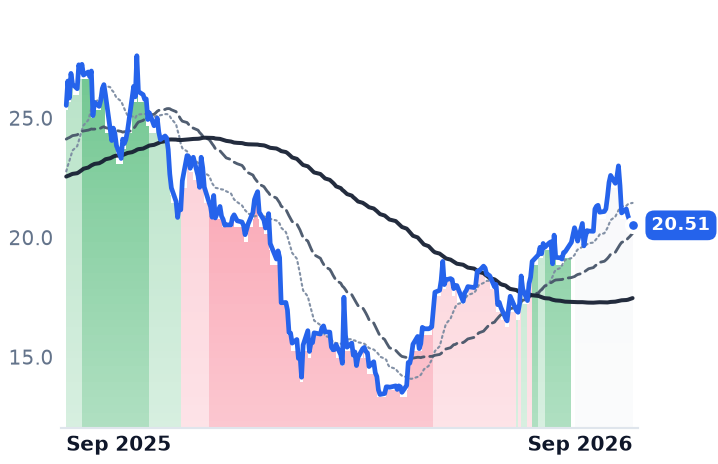
STVN | Stevanato Group S.p.A | Drug Delivery & Containment | 🌱 Emerging Bull | +1.2% | −19.7% |
| Compared against · context, not the story | |||||
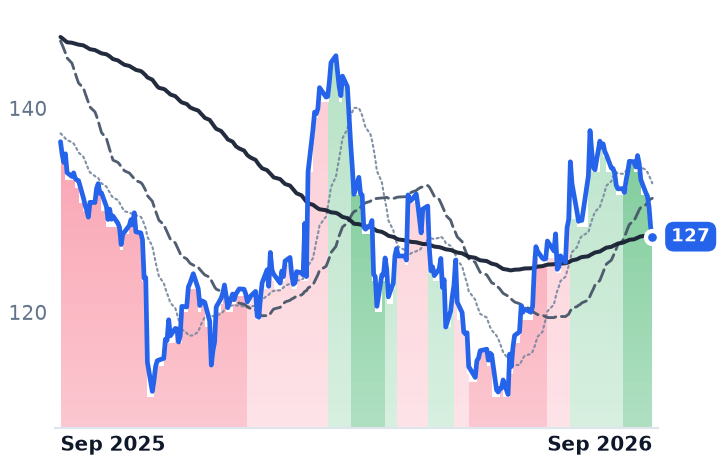
ATR | AptarGroup | Drug Delivery & Containment | 🌱 Emerging Bull | −5.0% | −6.8% |
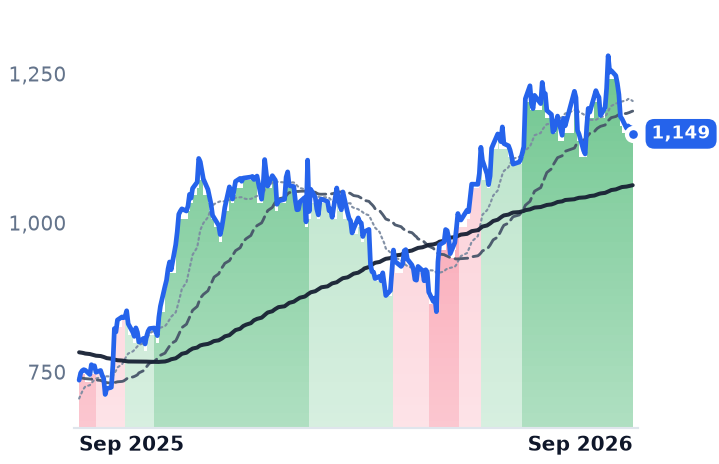
LLY | Eli Lilly and | Oncology | 🟢 Cont. Bull | −5.2% | +56.1% |
NVO | Novo Nordisk A/S | GLP-1 & Metabolic Diseases | 🌱 Emerging Bull | −1.3% | −11.0% |
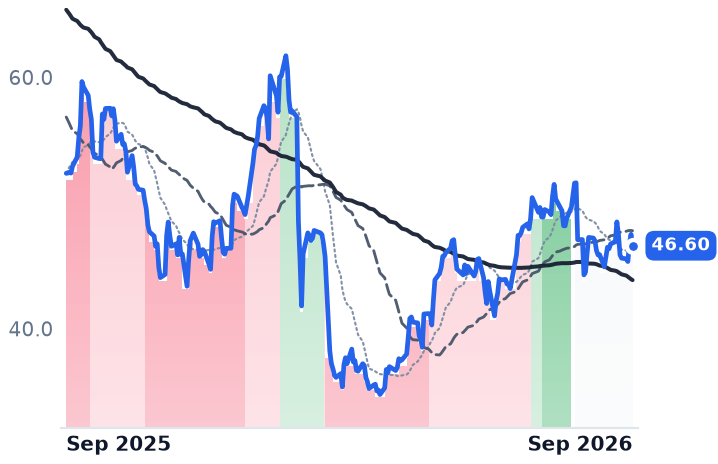
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WST | $23.9B | 43.2x | 37.9x | 7.2x | 7.1x | 19.6x | 19.3x | 28.9x | 1.8% |
STVN | $5.6B | 36.8x | 33.3x | 3.9x | 4.3x | 13.5x | 14.9x | 19.0x | -0.5% |
ATR | $8.1B | 22.8x | 23.1x | 2.1x | 2.0x | 7.3x | 7.2x | 11.4x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LLY | $946.4B | 35.6x | 27.5x | 13.1x | 11.2x | 15.7x | 13.4x | 29.7x | 1.4% |
NVO | $198.8B | 10.9x | — | 4.1x | — | 5.0x | — | 7.9x | 2.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WST | Revenue | +10.1% | +6.2% | +7.2% |
| EPS | +26.4% | +11.3% | +13.7% | |
STVN | Revenue | +10.1% | +9.2% | +9.5% |
| EPS | +17.4% | +19.7% | +18.1% | |
ATR | Revenue | +7.9% | +4.0% | +7.2% |
| EPS | −3.4% | +14.5% | +12.8% | |
LLY | Revenue | +32.8% | +15.7% | +12.0% |
| EPS | +54.8% | +21.6% | +15.4% | |
NVO | Revenue | −3.9% | +2.4% | +7.4% |
| EPS | −8.3% | +0.3% | +9.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
West Pharmaceutical Services spent the June quarter selling its customers the same rubber parts at a higher grade. The Pennsylvania company makes the elastomer stoppers, seals and syringe plungers that keep injectable drugs sterile, and its high-value versions of those parts — coated, pre-washed, pre-sterilized — did $424.1m in the quarter, up 19.4% reported and 18.4% organically, reaching 49% of total company sales. Over the same three months West Vantage, the contract-manufacturing arm that assembles finished injection devices, grew 0.8% organically.
That gap is the whole mechanism. The growth is not arriving as more doses filled; it is arriving as the same doses filled with a more expensive component. The EU Good Manufacturing Practice Annex 1 revision, effective August 2023, tightened container-closure-integrity rules for sterile products, and West has identified roughly 6 billion of its components as upgrade candidates, worth about two points of 2026 revenue growth. A regulator, in effect, raised the price of a stopper.
What the upgrade does to the accounts
West's reported revenue growth went from 7.5% in the fourth quarter of 2025 to 21.0% and then 13.8% — the shape of a company exiting the 2023-2025 destocking cycle that had dragged its annual gross margin from 41.5% in 2021 to 34.6% in 2024. June-quarter gross margin was 37.7%, up from 35.7% a year earlier. Management raised full-year guidance for the second time, to net sales of $3.345bn-$3.380bn and adjusted earnings of $8.85-$9.05 a share, with the third quarter guided to $820m-$835m.
"This was driven by our three growth drivers, which include biologics and biosimilars, HVP upgrades including Annex 1, and continued strength in GLP-1 elastomers," chief executive Eric Green said of the result on July 23. HVP is the company's shorthand for those high-value parts. GLP-1 obesity and diabetes therapies were 18% of West's sales in the March quarter, split between elastomers and device assembly.
The mirror meter, unpaid
Stevanato Group, the family-controlled Italian converter that makes the glass vials, cartridges and syringes those stoppers seal — and separately sells the filling and inspection machinery — is running the same play one cycle behind. Its high-value solutions grew 16% to €135.9m in the June quarter, 45% of revenue and guided to 47%-48% for the year. But the Engineering segment fell 2% to €35.8m and is guided to a mid-single to low-double-digit decline for the full year, with a return to prior form targeted only in 2027. Reported operating income fell 5.5% and net income 22.6%, the latter on a one-time charge from divesting a California contract manufacturer.
The cash tells the rest. Stevanato spent €52m of capital expenditure in the quarter and produced negative free cash flow of €32m, against net debt of €360.3m; full-year free cash flow is guided to €0-€20m. Its Fishers, Indiana plant has completed initial qualification on a vial line, but the first device program only reaches commercial production later in 2026 and full ramp is not expected until the end of 2028. "We are heavily investing into our plants in Europe, United States," chairman and chief executive Franco Stevanato told analysts on August 4, citing more than 9,000 injectable assets in the global drug pipeline. Depreciation from those plants is already in the margin; the volume is not.
AptarGroup, filed under the same industry label, is a useful reminder that the label bundles unlike businesses. Its pharma unit sells nasal pumps and inhaler valves alongside injectable elastomers, June-quarter core sales grew 1% across the group, and consensus has its 2026 earnings falling 3.4% while West's rise 26.4%. It trades at 23.1x forward earnings against 22.8x trailing — the forward reading above the trailing one, which is what an expected earnings decline looks like.
What the shares have already priced
West closed at $339.97 on September 4, up 37.3% over twelve months and 78.6% above its April 2025 low of $190.39. That advance was two days: a 7.5% jump on February 6 and a 12.9% jump on April 23 after the March-quarter print. At the 2025 low the shares carried about 27x then-forward earnings; today it is 37.9x forward against 43.2x trailing. Forward earnings expectations rose roughly 26% over that stretch, so about two-thirds of the move is the multiple — though it remains well below the roughly 60x the March 2024 peak carried. Stevanato, at $20.51, is still down 11.0% over twelve months and 36% below its own 2024 high, at 13.5x trailing gross profit against West's 19.6x, and near 29x forward earnings once its euro consensus is converted at current rates, up from roughly 19x at its March trough.
Both suppliers wobbled in late August alongside Eli Lilly, which fell 7.1% in a week; no company-specific disclosure was discoverable for either, so rotation out of the obesity complex is the likelier reading.
The verdict
West has earned its earnings: the mix shift is real, gross margin moved with it, and guidance went up twice. What it has not earned is the re-rating, which arrived faster than the profit and now leaves the stock priced for the upgrade cycle to keep compounding after 2026, when consensus already has revenue growth halving. Stevanato's discount is not skepticism about its mix — that is improving on the same meter — it is the bill for plants that will not be full for two more years. The two names are not one trade.
The bear case has arrived on schedule and is not yet biting. Novo Nordisk's oral Wegovy has drawn more than 3 million US prescriptions since its January launch, and Lilly's orforglipron was approved for obesity on April 1. Every pill swallowed is a cartridge, a plunger and a stopper that never ships. But the pill's share of total Wegovy scripts has held at 35% while the franchise's weekly total still grew — so far it is adding patients rather than draining vials. The number that matters to a stopper maker is not how many people take the pill. It is the first quarter in which the injected total stops going up.