

Ambarella and CEVA Booked Their Biggest AI Wins on Revenue That Starts in 2028
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two listed companies built entirely around putting AI inference into devices both reported inside the last month, and both showed the same thing on completely different meters: the volume is arriving, the money is dated later. Ambarella, paid when a chip ships, grew revenue 13.2% in the July quarter — its fifth straight deceleration — and guided the current quarter to a midpoint implying about 10%. CEVA, paid a royalty on every device its licensees make, saw those licensees ship 567m units, up 16%, and collected $10.8m of royalty, up 1%: the rate per device fell to roughly 1.9 cents from 2.2 cents. Ambarella's new accelerator, its 2nm custom chip and CEVA's flagship neural-processor license all carry first revenue in 2028. One of the two share prices has a business reason for falling; the other's case rests on a royalty rate, not a revenue line.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
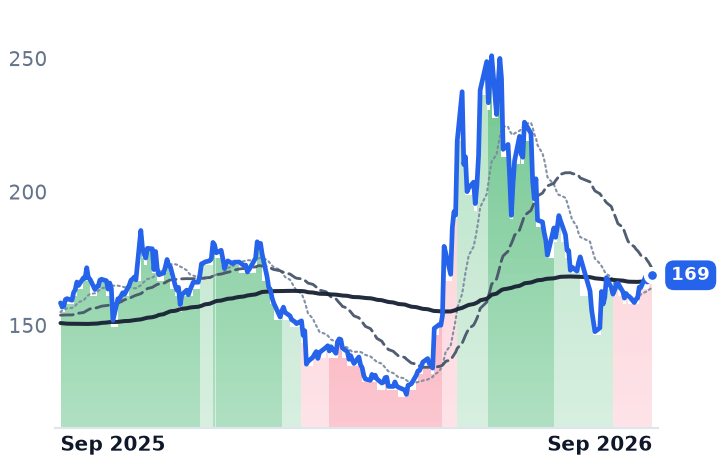
AMBA | Ambarella | Specialty Semiconductors | 🌱 Emerging Bull | −24.4% | −25.1% |
CEVA | CEVA | Specialty Semiconductors | 🌱 Emerging Bull | −19.6% | +16.0% |
| Compared against · context, not the story | |||||
NXPI | NXP Semiconductors | Analog & Mixed-Signal | 🟢 Cont. Bull | −3.1% | +2.5% |
ARM | Arm Holdings plc American Depositary Shares | Specialty Semiconductors | 🟢 Cont. Bull | −6.5% | +81.2% |
SYNA | Synaptics Incorporated | Other | 🟢 Cont. Bull | −6.5% | +40.3% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −9.0% | +15.3% |
ON | ON Semiconductor | Analog & Mixed-Signal | 🟢 Cont. Bull | −8.2% | +52.2% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | −6.4% | +46.5% |
LSCC | Lattice Semiconductor | Specialty Semiconductors | 🟢 Cont. Bull | −10.6% | +73.8% |
HIMX | Himax Technologies | Specialty Semiconductors | 🌱 Emerging Bull | −8.6% | +62.3% |
INDI | indie Semiconductor | RF & Wireless | 🌱 Emerging Bull | +0.0% | −15.1% |
MBLY | Mobileye Global | Advanced Safety & Autonomous Tech | 🔴 Cont. Bear | −3.3% | −42.3% |
QCOM | QUALCOMM Incorporated | RF & Wireless | 🟢 Cont. Bull | +2.8% | +6.5% |
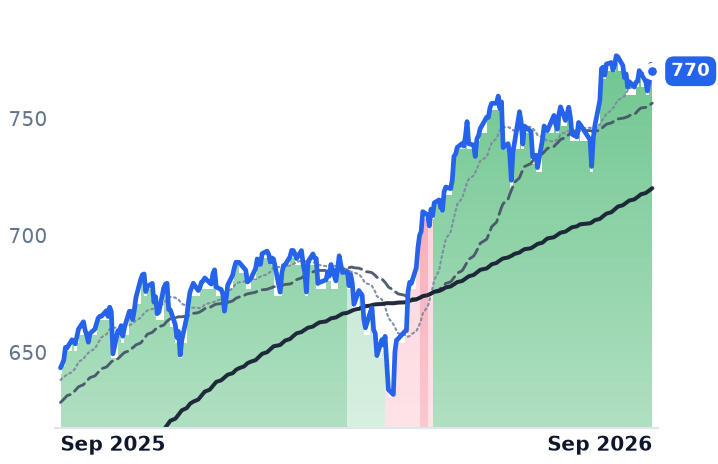
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.5% | +19.7% |
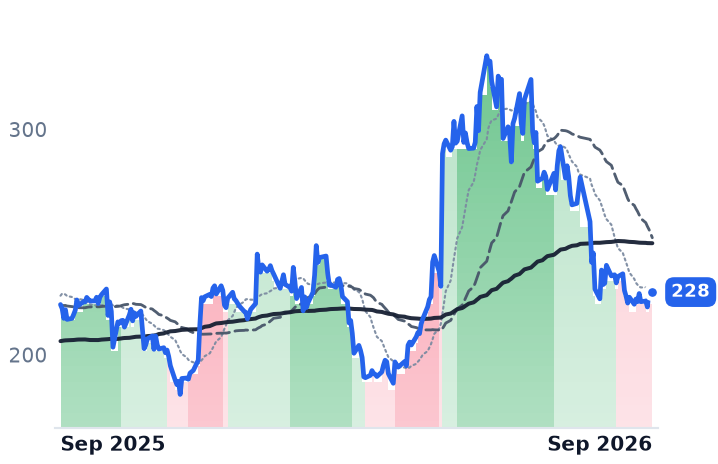
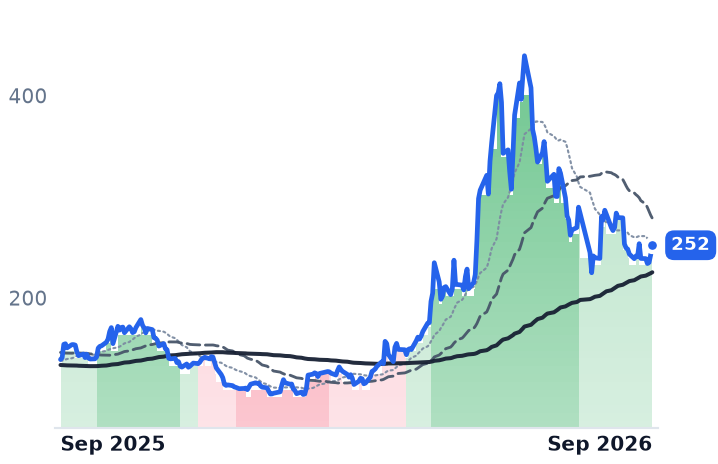
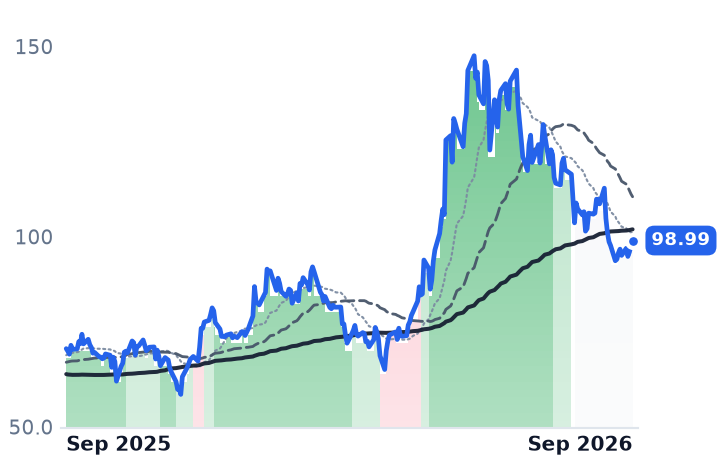
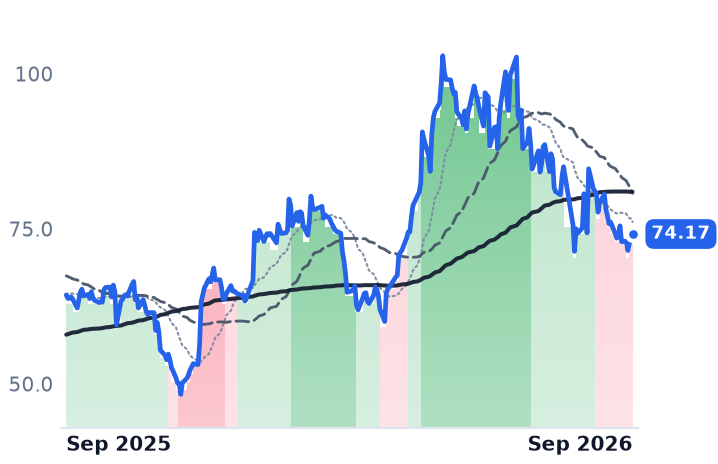
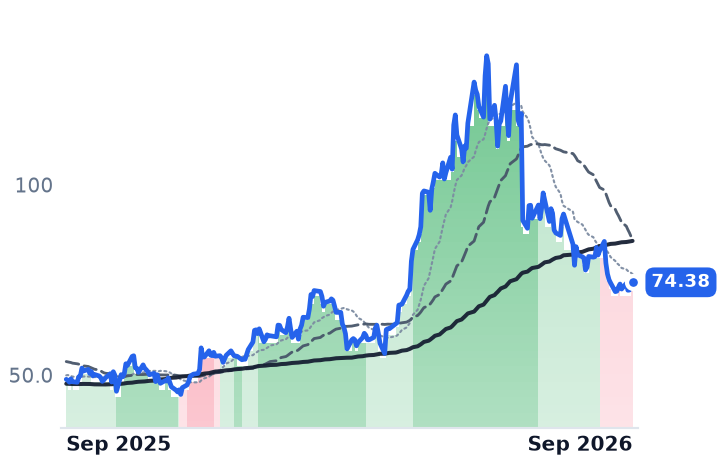
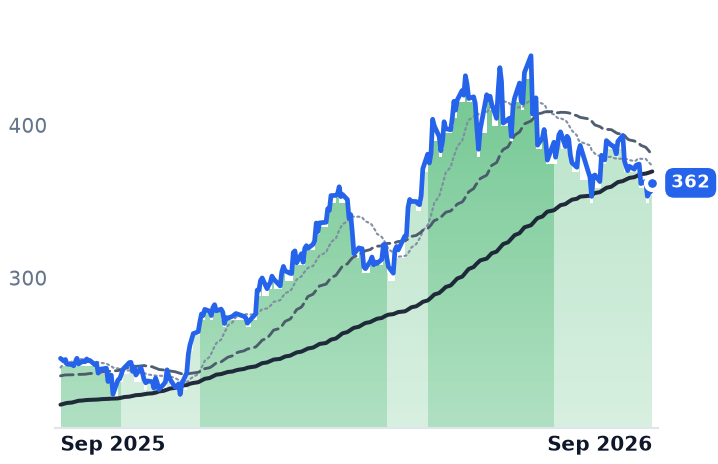
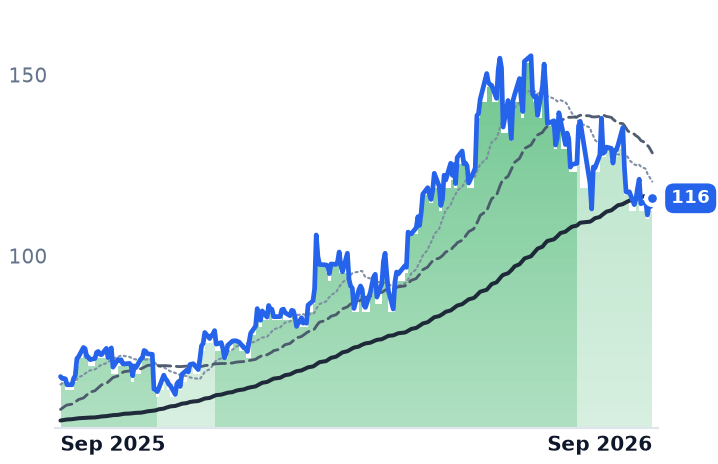
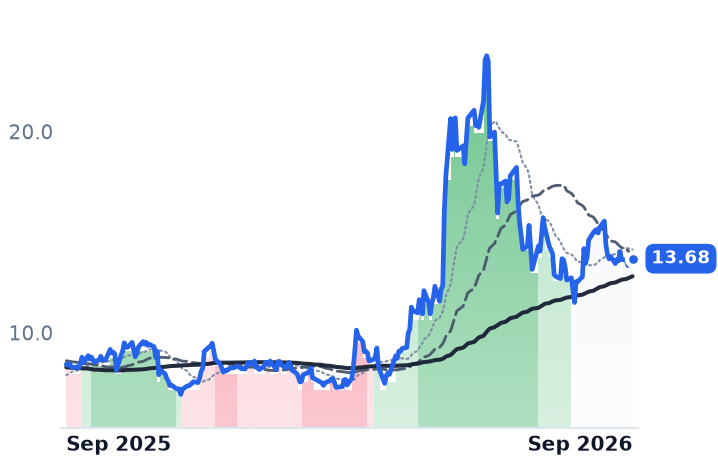
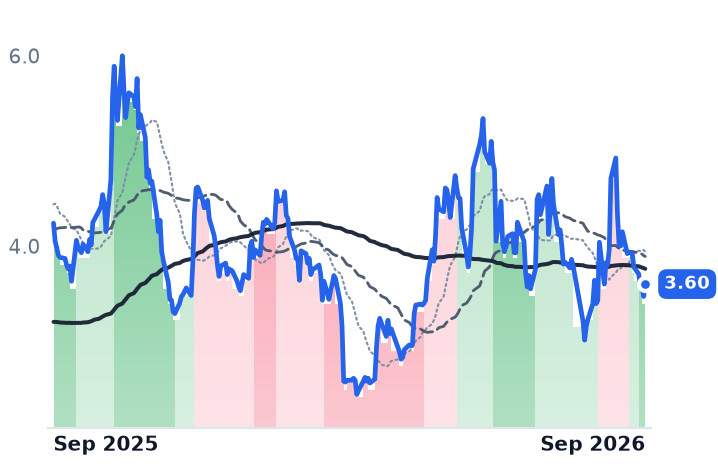
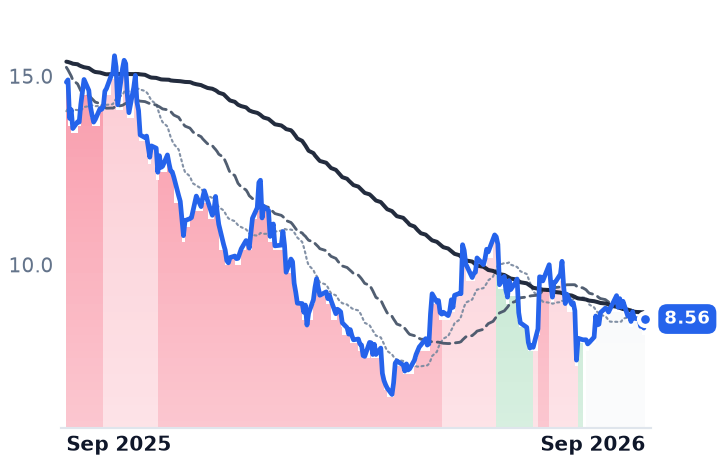
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMBA | $2.8B | n/m | 78.2x | 6.6x | 6.3x | 11.3x | 10.7x | n/m | 0.7% |
CEVA | $750.8M | n/m | 49.2x | 6.5x | 6.0x | 7.4x | 6.9x | n/m | -0.1% |
NXPI | $56.9B | 19.1x | 15.0x | 4.3x | 4.0x | 7.7x | 7.1x | 13.2x | 5.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARM | $259.9B | 250.8x | 109.3x | 50.4x | 42.9x | 52.9x | 45.0x | 187.4x | 0.6% |
SYNA | $3.9B | n/m | 19.2x | 3.3x | 3.0x | 7.4x | 6.8x | n/m | 2.6% |
MCHP | $40.2B | 102.6x | 20.3x | 7.8x | 6.3x | 13.0x | 10.4x | 26.9x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $32.5B | 52.8x | 26.1x | 5.2x | 5.0x | 14.0x | 13.2x | 26.4x | 5.5% |
ADI | $181.1B | 43.9x | 28.9x | 13.0x | 12.0x | 19.8x | 18.2x | 28.8x | 2.7% |
LSCC | $16.1B | 445.0x | 55.3x | 24.8x | 17.5x | 36.6x | 25.9x | 184.5x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HIMX | $3.3B | 104.1x | 47.6x | 4.1x | 3.6x | 13.4x | 11.7x | 49.4x | 2.1% |
INDI | $846.2M | n/m | — | 3.7x | 3.2x | 17.0x | 14.8x | n/m | -9.9% |
MBLY | $7.0B | n/m | 17.4x | 3.5x | 3.5x | 7.3x | 7.4x | n/m | 5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QCOM | $170.3B | 18.5x | 15.3x | 3.9x | 3.9x | 7.1x | 7.3x | 13.4x | 6.1% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AMBA | Revenue | +39.8% | +13.1% | +12.0% |
| EPS | −311.2% | +35.0% | +31.2% | |
CEVA | Revenue | +14.3% | +13.0% | +12.8% |
| EPS | +31.8% | +45.2% | +36.4% | |
NXPI | Revenue | +16.7% | +11.5% | +8.3% |
| EPS | +28.0% | +20.5% | +15.3% | |
ARM | Revenue | +22.5% | +23.7% | +35.6% |
| EPS | +7.9% | +27.0% | +35.7% | |
SYNA | Revenue | +11.4% | +8.8% | +12.7% |
| EPS | +26.7% | +14.3% | +24.5% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
ON | Revenue | +9.2% | +12.9% | +13.5% |
| EPS | +37.1% | +41.7% | +31.7% | |
ADI | Revenue | +37.7% | +21.9% | +11.1% |
| EPS | +65.6% | +29.0% | +17.0% | |
LSCC | Revenue | +2.3% | +76.6% | +45.0% |
| EPS | +11.9% | +102.7% | +50.7% | |
HIMX | Revenue | +12.6% | +24.3% | +21.9% |
| EPS | +63.3% | +115.0% | +72.1% | |
INDI | Revenue | +22.8% | +35.4% | +44.7% |
| EPS | −44.1% | −131.9% | +471.0% | |
MBLY | Revenue | +6.3% | +9.5% | +22.5% |
| EPS | +37.4% | +2.4% | +39.5% | |
QCOM | Revenue | −1.3% | +4.2% | +15.1% |
| EPS | −10.8% | −2.6% | +26.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ambarella closed its July quarter with the fifth consecutive slowdown in its rate of revenue growth, and every product it announced alongside the result bills later. Revenue was $108.1m for the quarter ended July 31, up 13.2% year on year, the company reported on September 3; the guidance midpoint for the current quarter, $119.5m, implies about 10.2% growth, a sixth step down. Adjusted earnings of $0.18 a share beat estimates.
That matters beyond one print because Ambarella and CEVA are the two listed companies whose whole business is moving AI inference into devices, and they bill on opposite meters. Ambarella designs the low-power vision chips inside internet-protocol security cameras, dashcams and automotive driver-monitoring systems, and is paid when silicon ships. CEVA never ships a chip: it licenses digital signal processor, neural processor, Bluetooth and Wi-Fi blocks to chipmakers, taking a fee upfront and a per-unit royalty on every device a licensee manufactures, reported a quarter in arrears. Both meters have now been read, and neither shows edge inference arriving as revenue yet.
Ambarella: the ramp is real, the new money is FY2028
The operating leverage is genuine. Gross profit rose 13.4% on revenue up 13.2% with operating expenses held, narrowing the operating loss to $8.1m from $22.0m and taking operating margin from -23.0% to -7.5%. Automotive set a revenue record on commercial vehicles, and the 5nm CV75 and CV72 chips are in a steep ramp.
The announcements, though, are dated. The X7 — Ambarella's first standalone AI accelerator, entering a field management itself described as including NVIDIA, Qualcomm and roughly 50 startups — is only sampling. The semi-custom 2nm CV8 expects first production revenue in fiscal 2028. Two seven-year channel partnerships were sized by chief executive Fermi Wang on the September 3 call: "When we talk to both CapGemini and Macnica, the range of revenue we are expecting from this collaboration is $0.5 billion with each one of them" — with meaningful revenue two to three years out.
What is not dated is cost. Non-GAAP gross margin of 59.3% missed the company's own guided midpoint, and management flagged memory-supply risk for the fourth quarter. Memory makers have shifted wafer capacity from conventional DRAM to high-bandwidth memory for AI accelerators; data centers now absorb an estimated 70% of world memory output, with contract prices up more than 50% quarter on quarter entering 2026. The AI buildout is currently reaching Ambarella as an input cost.
CEVA: sixteen percent more chips, one percent more money
CEVA's licensees shipped 567m units in the June quarter, up 16%, and paid $10.8m of royalty — up 1%. That is roughly 1.90 cents a device against about 2.19 cents a year earlier, because the growth came from low-rate Wi-Fi, up 28%, while higher-earning Bluetooth units fell 16%.
The reported line is otherwise improving. Licensing revenue rose 21% to $18.2m, the best in three years, on 10 agreements including two with first-time customers; full-year growth guidance went up to 13-15% and non-GAAP operating margin to 11% from 3%. "We are seeing increasing demand for our technologies across AI, connectivity, and sensing, strong adoption of broader hardware and software platforms, and continued diversification of our royalty base," chief executive Amir Panush said on August 10. But the flagship win — its NeuPro-M neural processor selected for custom AI silicon by a large computing platform company — runs 18 to 24 months to production, so royalties start in 2028. The identified fix for the rate per device, Bluetooth HDT, ramps meaningfully in 2027-28.
What the shares have done
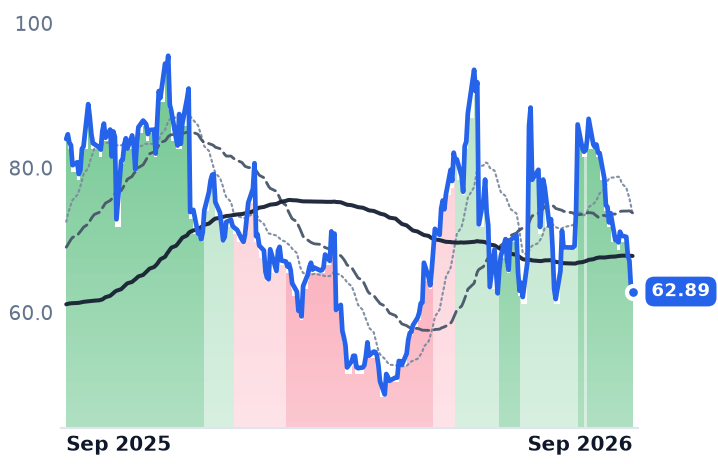
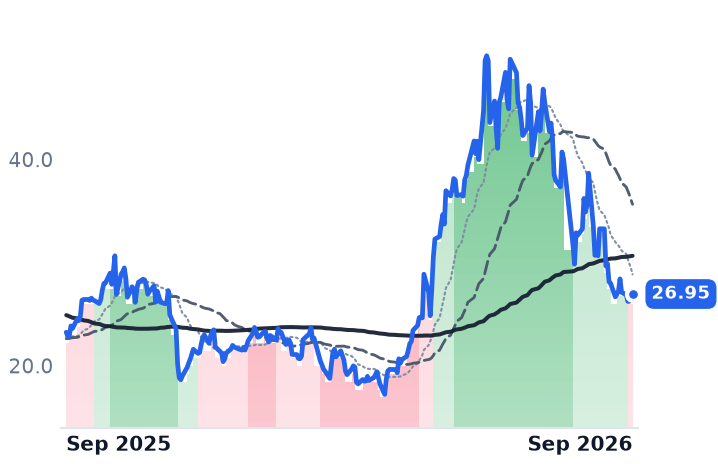
Ambarella closed at $62.89 on September 4, down 27.5% from its August 7 high and 15.1% below the $74.09 it closed at before the Financial Times reported NXP Semiconductors was in talks to buy it for more than $3bn — the entire takeover premium and more, given back. Its 10.7% fall over September 1-4 was its own: NXP rose 1.8% and Arm 5.5% across the same sessions. CEVA, at $26.95, is down 45.6% since early June, but so is the small-cap chip complex around it — Himax -42.8%, onsemi -43.6%, Arm -35.9%.
Gross margins differ by nearly 30 points, so price against forward gross profit is the only comparison that holds: Ambarella at 10.7x, down from roughly 14.8x at its August peak, and CEVA at 6.9x from about 12.8x in June. Ambarella carries 78.2x forward earnings on consensus growth of 13%; CEVA 49.2x, falling to about 34x on 2027 estimates.
Ambarella's de-rating is earned. Five quarters of deceleration and a guide to a sixth, on a chip that has to be manufactured through a memory squeeze, do not support a multiple set for acceleration. CEVA's is not earned by its reported numbers, which are going the other way — but the royalty rate per device is real deterioration, and the company's own remedies for it are 2027 and 2028 events. Two businesses, two meters, one answer: what edge AI is worth to either of them will not be measurable this fiscal year.
The cleanest test costs nothing to run. CEVA reports its licensees' unit shipments and its royalty dollars every quarter. When 16% more devices start producing more than 1% more money, the story will have arrived.