

EchoStar Cashed Out Its Spectrum and Now Trades $13bn Below the Value of Its SpaceX Stake
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
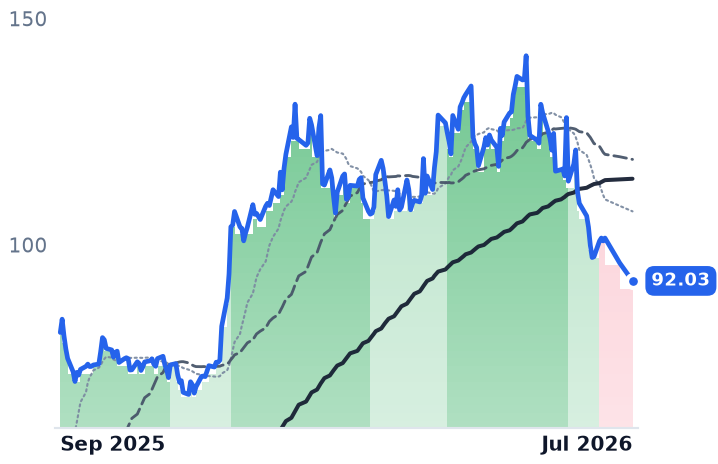
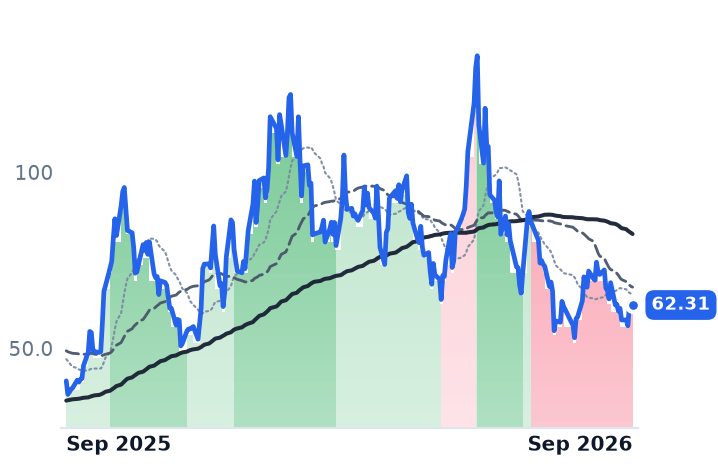
EchoStar no longer runs the businesses its filings describe, and its equity has become a claim on somebody else's stock. The company sold its terrestrial mobile airwaves to AT&T for $20.25bn of proceeds and to SpaceX largely for shares, leaving it holding roughly 261.8m SpaceX shares, marked near $38.7bn on September 5 against a market value of about $25bn.
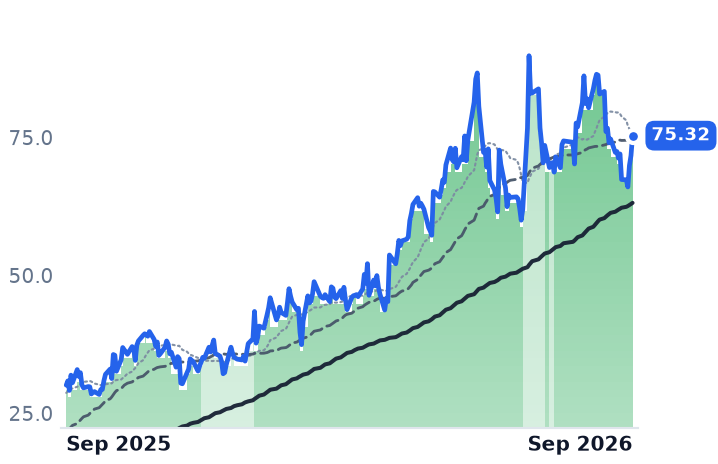
The discount is not free. EchoStar itself sizes SpaceX-transaction and tax obligations at $5-7bn, its Hughes unit filed for Chapter 11 in August after failing to repay $1.5bn of bonds, and Hughes creditors are contesting cash moved upstairs. Underneath, revenue fell 4.0% to $3.576bn and pay-TV lost 241,000 subscribers in the quarter. Viasat, the segment's other large name, still bills an operating meter — and its re-rating this year came from the multiple rather than the revenue line.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SATS | EchoStar | Satellite & Broadband Services | ⚠️ Emerging Bear | — | +14.1% |
VSAT | Viasat | Satellite & Broadband Services | 🟢 Cont. Bull | −6.3% | +150.2% |
| Compared against · context, not the story | |||||
TSAT | Telesat | Satellite & Broadband Services | 🟢 Cont. Bull | −23.8% | +104.3% |
GILT | Gilat Satellite Networks | Satellite & Broadband Services | ⚠️ Emerging Bear | −9.9% | −4.3% |
ASTS | AST SpaceMobile | Satellite & Broadband Services | ⚠️ Emerging Bear | −13.4% | +52.8% |
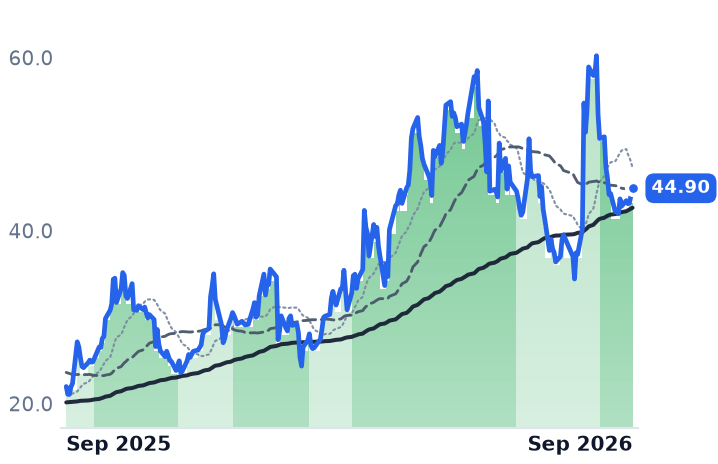
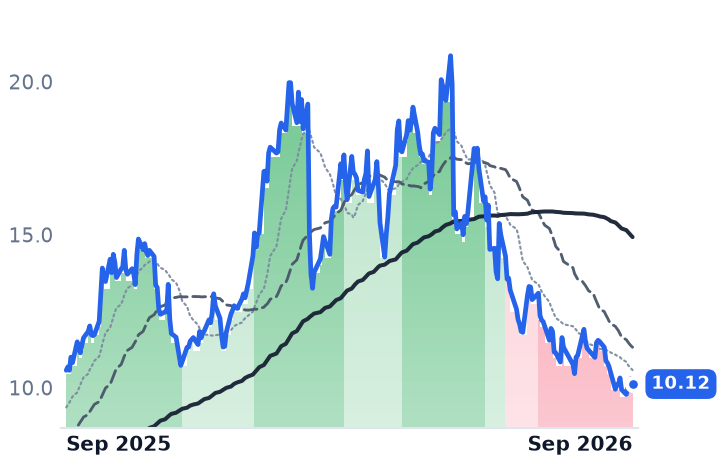
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SATS | $25.1B | n/m | 4.6x | 1.7x | 1.7x | 5.8x | 5.9x | n/m | -1.1% |
VSAT | $10.4B | n/m | — | 2.2x | 2.1x | 7.4x | 7.0x | 8.7x | 5.6% |
TSAT | $699.7M | n/m | — | 2.7x | 2.2x | 5.9x | 4.8x | n/m | -76.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GILT | $808.3M | 23.3x | 17.4x | 1.7x | 1.6x | 5.5x | 5.3x | 12.4x | -0.4% |
ASTS | $27.3B | n/m | — | 236.7x | 171.8x | — | — | n/m | -6.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SATS | Revenue | −4.0% | −5.7% | −7.6% |
| EPS | −141.8% | −86.6% | +31.6% | |
VSAT | Revenue | +3.6% | +3.9% | +4.6% |
| EPS | −66.9% | +40.3% | +1.5% | |
TSAT | Revenue | −22.5% | −14.0% | +101.1% |
| EPS | +52.5% | +7.6% | −25.1% | |
GILT | Revenue | +13.2% | +11.7% | +10.6% |
| EPS | +6.6% | +16.3% | +13.3% | |
ASTS | Revenue | +172.1% | +330.7% | +167.9% |
| EPS | +37.1% | −48.4% | −180.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The company that sold its reason to exist
EchoStar has sold the spectrum that was its entire asset base, and what remains is mostly somebody else's stock. AT&T's purchase of about 30 megahertz of nationwide 3.45 gigahertz airwaves and about 20 megahertz of 600 megahertz airwaves has closed, handing EchoStar $20.25bn of proceeds plus a further $2.4bn that AT&T deposited into a trust the Federal Communications Commission requires against the shutdown of EchoStar's own network; $2bn of senior secured notes were repaid on July 28. SpaceX bought the 2 gigahertz and H-block licences for $17bn and then added the unpaired AWS-3 licences for about $2.6bn, paid largely in shares — approximately 261.8m of them.
That holding is now the company. SpaceX listed on Nasdaq on June 12, pricing at $135 and closing its debut at $161. At $147.90 on September 5 the EchoStar stake marks near $38.7bn — some $13bn more than EchoStar's whole $25.07bn market capitalization, and that is before $14-15bn of cash. In early August the same shares closed at an all-time low of $108.27, valuing the stake at roughly $28.3bn. Holders of a stock that swapped the ticker SATS for ECHO in June are underwriting one asset whose mark moved $10bn inside a month.
The meter still running underneath
The operating businesses are shrinking on every line. June-quarter revenue fell 4.0% to $3.576bn. The headline $8.46bn of net income is an accounting event: excluding a non-cash gain on deconsolidation of about $9.73bn, net income attributable to EchoStar was roughly $49.5m. Pay-TV shed about 241,000 net subscribers to 6.39m, split between DISH TV and Sling; wireless lost 118,000 to end at 7.375m, which the company blamed on discounted rival plans and deeper competitor device subsidies. On the August 3 call management said of Boost Mobile that it had "treaded water for 4 years" and that they "haven't cracked the code." Consensus has revenue contracting every year to $11.22bn by 2030.
So the earnings multiples do not function — trailing price-to-earnings of -4.37x, trailing enterprise value to EBITDA of -7.75x — and even the 4.57x forward reading is built on the same non-cash gains. Price-to-book of 1.78x and price-to-sales of 1.71x trailing against 1.75x forward, the forward figure higher because sales fall, are what is left.
Claims on the cash
Hughes Satellite Systems and certain US subsidiaries filed for Chapter 11 in the Southern District of Texas on August 3, after failing to repay $1.5bn of bonds that matured two days earlier. Hughes bondholders allege EchoStar drained more than $1.5bn from the unit beforehand, contesting roughly $1.029bn of dividends paid up to the parent in 2024, about $196m of tax reimbursements, the J3 satellite lease and the referral of Hughes consumer subscribers to SpaceX. Against the asset side sit EchoStar's own figures given on that August call: $2.4bn escrowed in the FCC trust, roughly $5bn of debt excluding Hughes, $1.9bn of convertibles in the money, and a self-estimated $5-7bn of SpaceX-transaction and tax liability. The board lifted the buyback authorization to $5bn and has bought nothing, because bond indentures block repurchases — even with the stock at about half of the company's own net-asset estimate.
The other meter
Viasat, the Carlsbad multi-orbit operator whose Inmarsat arm holds the L-band maritime distress franchise, is the mirror image: it still sells minutes. June-quarter revenue slipped 1.2% to $1.157bn and adjusted EBITDA fell 7% to $381m, but aviation revenue rose 11% on 4,530 aircraft in service and government satellite communications rose 10%, while US fixed broadband fell 27% to 115,000 subscribers. Net debt of $4.84bn at 3.2x EBITDA funds guided capital spending of $950m to $1bn this fiscal year against roughly $180m of free cash flow, and the shares trade at 8.68x trailing enterprise value to EBITDA. Chief executive Mark Dankberg told investors on August 4 that "the best way to hold onto your spectrum is to put it in use for public benefit for the nations which have granted those market access rights" — the opposite of the EchoStar trade — and kept the long-promised separation of the defense unit unresolved.
Both stories are being marked down together. From August 4 to September 4 Viasat fell 12.6%, Telesat 18.0%, Gilat 15.0% and AST SpaceMobile 11.4%; EchoStar sat out because it had already dropped about 30% from $124.64 on June 4. With no fresh operating news at Viasat in the window, the likelier reading is a give-back of the spectrum-and-defense-award premium those names carried into August. Viasat's own re-rating is measurable: price-to-sales has gone from 1.71x in early May to 2.24x, on revenue that fell.
What each side earns
EchoStar's discount to its assets is real and is not free — the marked stake alone moved $10bn in a month, the tax and termination bill is the company's own estimate rather than a settled number, and creditors are suing over the cash. What the market is refusing to pay for is the certainty of the arithmetic, and that refusal is rational. Viasat's case is the reverse: the mix migration is genuine, aviation and government growth offsetting the Starlink-exposed broadband line almost exactly, which is why consolidated revenue went nowhere. Nothing in the June quarter earned the multiple expansion of the spring.
The DISH Wireless bankruptcy confirmation hearing is set for October 13. Until then EchoStar's largest asset will be repriced daily by a stock it does not control and cannot sell into.