

Ormat Faces Investors Monday With Consensus Modeling 2027 Revenue Down 1.1%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
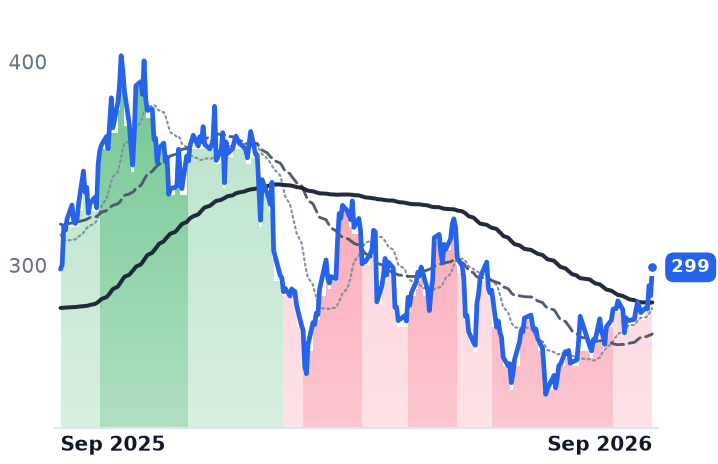
Ormat's shares have fallen roughly a quarter in three months while the business got better on the top two lines — June-quarter revenue rose 10.6% and gross margin widened 220 basis points to 26.5%. The composition is why the market disagreed: contracted geothermal electricity revenue grew 5.8%, merchant battery revenue nearly tripled, and consensus now models 2026 revenue up 21% followed by a 1.1% decline in 2027 as a lumpy turbine-delivery year does not repeat.
The analyst who opened the de-rating with an Underperform rating in June closed it on Friday, calling the multiple fair two working days before Ormat's September 8 investor day. That leaves Monday carrying the growth case — 2028 targets, and an enhanced-geothermal roadmap whose first well is not scheduled to spud until the fourth quarter, by which time Fervo expects to be making test power.
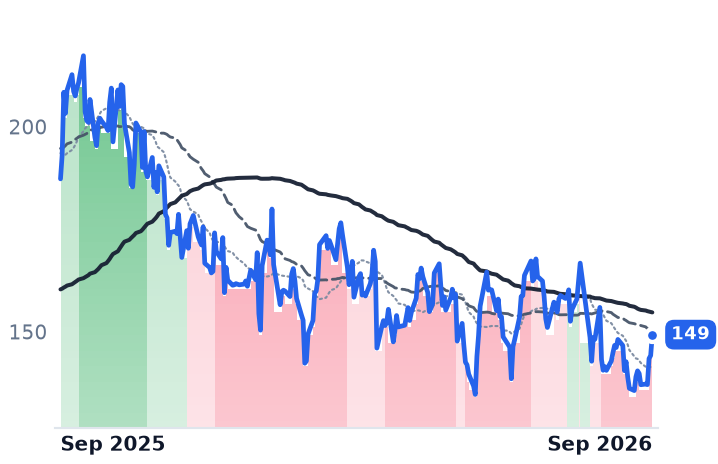
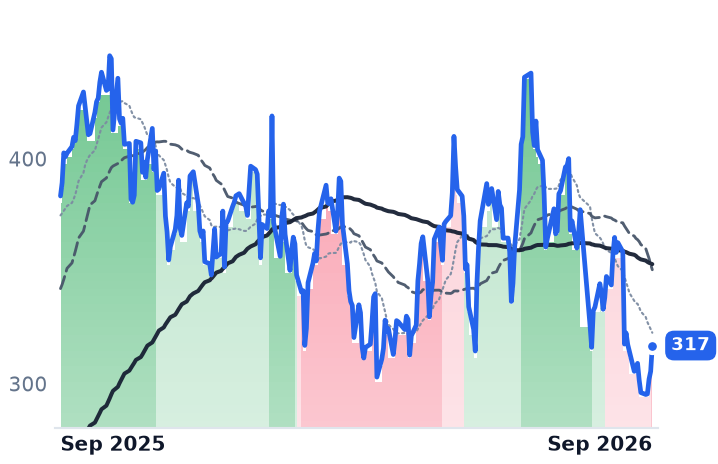
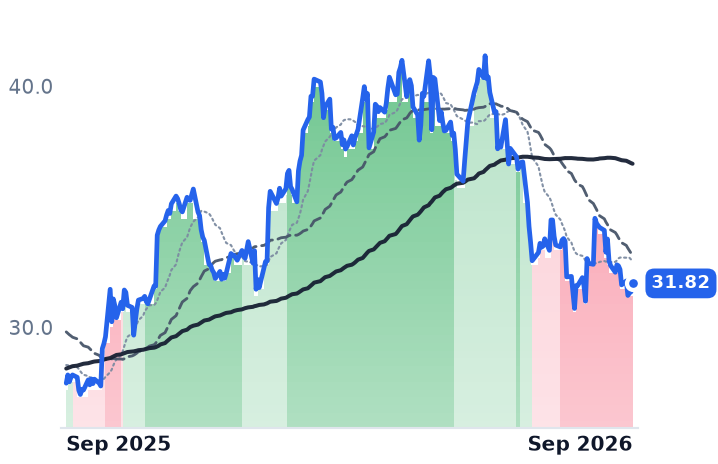
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
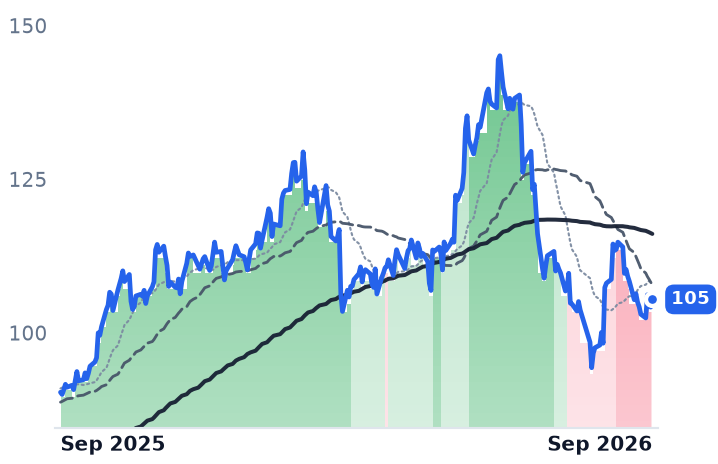
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | −2.4% | +16.7% |
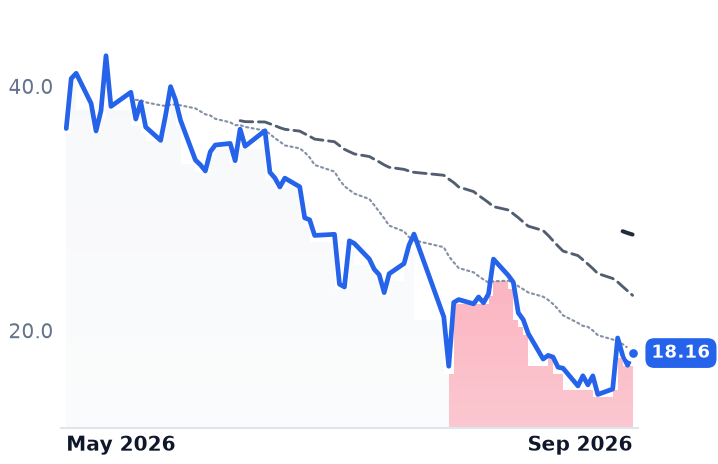
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −29.7% | −50.3% |
| Compared against · context, not the story | |||||
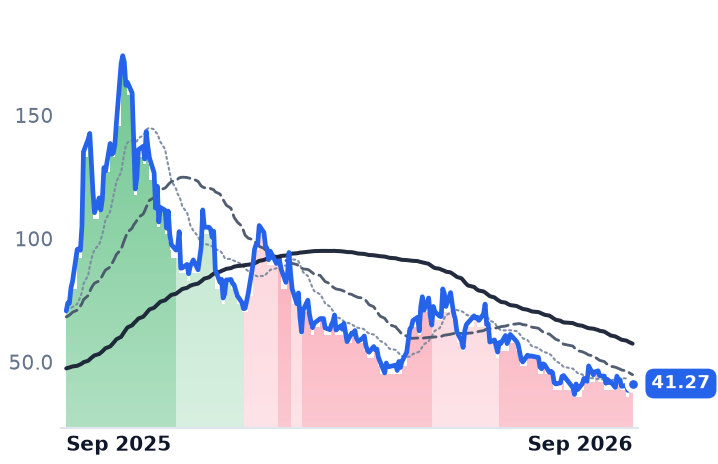
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −14.8% | −41.6% |
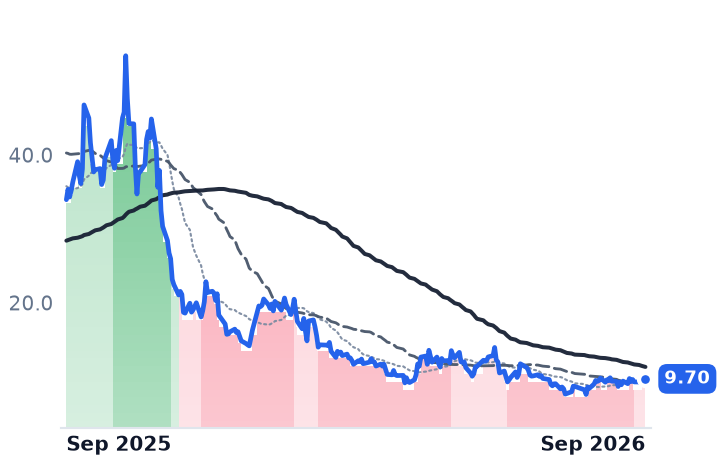
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −1.2% | −71.4% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | +10.8% | +0.3% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +6.2% | −20.3% |
TLN | Talen Energy | Wholesale Power Producers | 🔴 Cont. Bear | −8.8% | −17.3% |
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −2.5% | +14.9% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −1.4% | +21.2% |
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | −4.9% | +57.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORA | $6.5B | 50.7x | 41.4x | 5.5x | 5.5x | 19.5x | 19.7x | 21.6x | -4.1% |
FRVO | $5.2B | n/m | — | — | 900.0x | — | — | n/m | -8.5% |
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $2.8B | n/m | — | 261.9x | 91.1x | — | 432.7x | n/m | -27.7% |
CEG | $107.4B | 29.1x | 24.8x | 3.4x | 3.2x | 3.6x | 3.4x | 15.4x | 0.3% |
VST | $50.3B | 24.9x | 17.3x | 3.2x | 2.2x | 24.3x | 17.3x | 10.8x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $14.4B | n/m | 15.4x | 4.1x | 3.2x | 9.1x | 7.2x | 29.9x | 3.5% |
CWEN | $6.5B | 41.4x | — | 4.1x | 3.9x | 7.8x | 7.4x | 14.4x | 10.4% |
NEE | $175.3B | 18.8x | 20.9x | 6.0x | 5.7x | 8.4x | 7.9x | 16.0x | -5.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $242.9B | 25.9x | 29.7x | 5.9x | 5.2x | 29.0x | 26.0x | 27.0x | 5.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORA | Revenue | +21.4% | −1.1% | +12.1% |
| EPS | +16.4% | −3.5% | +25.9% | |
FRVO | Revenue | +4094.5% | +1158.9% | +186.8% |
| EPS | −92.0% | −19.8% | −26.6% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% | |
SMR | Revenue | −26.7% | +434.9% | +101.2% |
| EPS | −74.7% | +33.4% | −18.3% | |
CEG | Revenue | +36.6% | +2.6% | +5.5% |
| EPS | +28.7% | +10.1% | +26.3% | |
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% | |
CWEN | Revenue | +14.8% | +10.8% | +13.4% |
| EPS | −133.6% | −152.5% | +132.7% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% | |
GEV | Revenue | +23.9% | +14.8% | +15.0% |
| EPS | +321.7% | −19.5% | +40.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ormat Technologies — a geothermal owner-operator that also manufactures the binary turbines other developers install in their plants — brings management to the New York Stock Exchange on Monday for an investor day, and it arrives with its own bear case already withdrawn. Bernstein SocGen's Sunaina Ocalan, who initiated coverage at Underperform on June 17 with a $115 target, upgraded the stock to Market Perform on Friday on an unchanged $112 target, describing the shares as trading in line with their 2026 average and naming the investor day as a catalyst.
What Monday has to sell is the year after next. Consensus carries Ormat revenue to $1.179bn in 2026, a 21.4% increase, and then marks it down 1.1% in 2027, with earnings per share slipping from $2.54 to $2.45. The market has already decided that this year's growth is a delivery schedule rather than a franchise.
The multiple did the falling
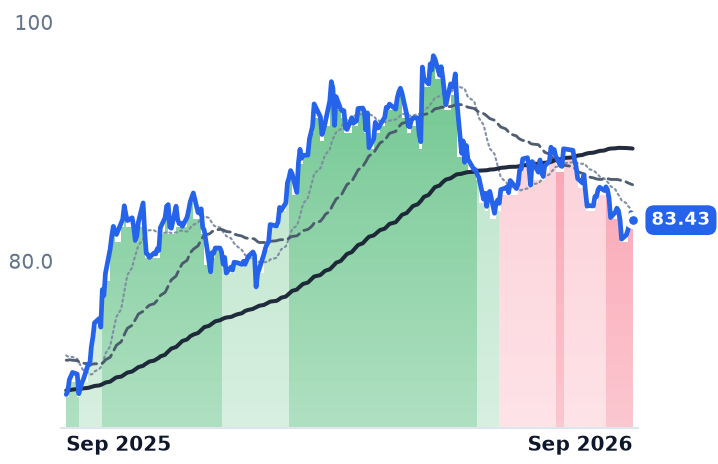
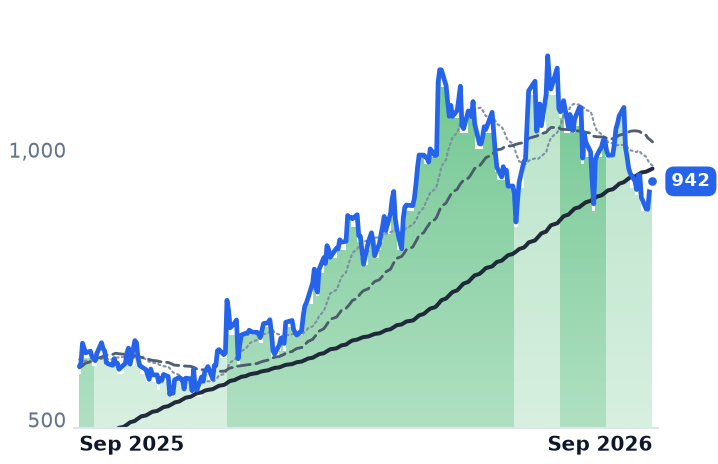
Ormat peaked at $145.10 on June 3 and bottomed at $94.33 on July 29, a 35% drawdown, and the price at $105.45 now sits below the lowest published target on the street; the twelve-analyst average is $132.83. Gross profit grew 20.8% over that stretch. The compression is visible against gross profit — 19.5x now, against 25.9x in May — and against cash earnings: trailing enterprise value to EBITDA of 21.6x versus roughly 14.3x on the guided 2026 adjusted EBITDA midpoint of $640m. For a company carrying $3.4bn of debt at 4.3 times EBITDA, the cash-earnings reading is the one that binds.
The composition explains most of the skepticism. June-quarter electricity revenue, the contracted baseload the whole story rests on, grew 5.8% to $169.3m, while energy storage revenue rose 195% to $42.8m on merchant PJM prices management expects to normalize toward a 40-50% segment gross margin. Operating income fell 3.2% and net income fell 3.4% to $27.1m — a quarter in which Ormat also booked a $9.5m investment-tax-credit benefit and $16.6m of income from selling tax benefits. Product backlog stands at $203m after a $105m turbine delivery was recognized in the first quarter.
What is actually under construction
Ormat has 202 megawatts under construction or development through 2028, all with signed offtake agreements, and roughly 190 megawatts of expiring contracts priced at a weighted-average $86 per megawatt-hour against a market above $100 — a repricing option that costs almost no capital. The enhanced-geothermal program that data-center buyers ask about is later: the Desert Peak pilot with SLB has permits filed and drilling on track for the fourth quarter, with connection to existing facilities at end-2027 or early 2028. "We will obviously give a lot more information on our Investor Day," chief executive Doron Blachar told analysts on the second-quarter call, deferring repeatedly.
Fervo Energy, the Houston developer applying shale drilling technique to hot rock, is the other meter. It sold $113,000 of power last quarter against a $28.7m operating loss, but has 1,054 megawatts under binding contract after Google's 396-megawatt agreement, and has cut drilling costs more than 70% to about $400 a foot. "The biggest expense in drilling is time it takes to drill," chief executive Tim Latimer said. Its enterprise value of roughly $3.3bn works out near $3.2m per contracted megawatt against a $5.5m build-cost target — cheap only if the megawatts get built, and second-half capital spending guided at $850-900m against $2.1bn of cash says more financing comes first. Consensus shows no positive EBITDA until 2029. The shares are 33% below the $27 May listing price.
The verdict
Ormat's fall is mostly earned, and it is mostly finished. A business whose incremental growth comes from merchant batteries, one-off turbine shipments and monetized tax credits does not deserve the multiple it held in May, and the sell-side bear stood down rather than pressing because the arithmetic no longer supported him. What the de-rating does not explain is 20.8% gross-profit growth and a widening margin. Monday decides which reading survives: a 2028 target built on contracted electricity and repricing, or another year of deferral on enhanced geothermal.
Fervo expects to spin a turbine for test power at Cape Station this quarter. Ormat expects to start drilling its first enhanced-geothermal well in the same one.