

Karman Booked $1.3bn of Backlog, Then Lost Its CFO and Drew a Short Report
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A category of space-propulsion suppliers looks like it is rolling over. One stock is doing all of it, and its reported business is accelerating.
Karman Holdings, which builds payload fairings, interstage structures and solid-propulsion units for missile-defense and launch programs, grew second-quarter revenue 58% to $182.1m, widened gross margin to 43%, lifted backlog 65% to $1.3bn and raised its full-year revenue forecast to $730m-745m. Since then its finance chief has resigned, a secondary offering was announced, and a short seller attacked its acquisition disclosure.
The reported numbers earn none of the decline; the multiple does. Even after the fall Karman trades at 68.1x forward earnings and does not yet generate free cash. BWX Technologies, the naval-reactor maker sitting in the same category, is down 3.8% over twelve months — this is one company's problem.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −7.2% | −3.5% |
| Compared against · context, not the story | |||||
KRMN | Karman | Missiles, Weapons & Fire Control | ⚠️ Emerging Bear | −31.3% | −35.9% |
HII | Huntington Ingalls Industries | Naval & Shipbuilding | ⚠️ Emerging Bear | −11.9% | +6.7% |
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +3.4% | +30.7% |
LMT | Lockheed Martin | Large Diversified Primes | ⚠️ Emerging Bear | −10.7% | +15.9% |
NOC | Northrop Grumman | Large Diversified Primes | ⚠️ Emerging Bear | −9.9% | −10.9% |
GD | General Dynamics | Large Diversified Primes | 🟢 Cont. Bull | −8.3% | +12.8% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −1.2% | −71.4% |
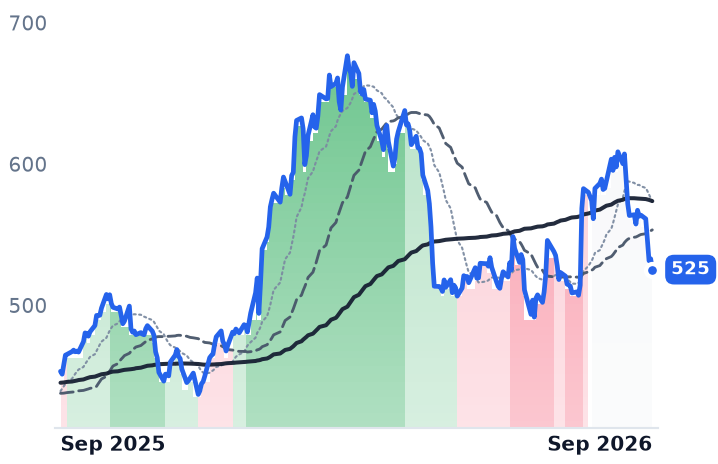
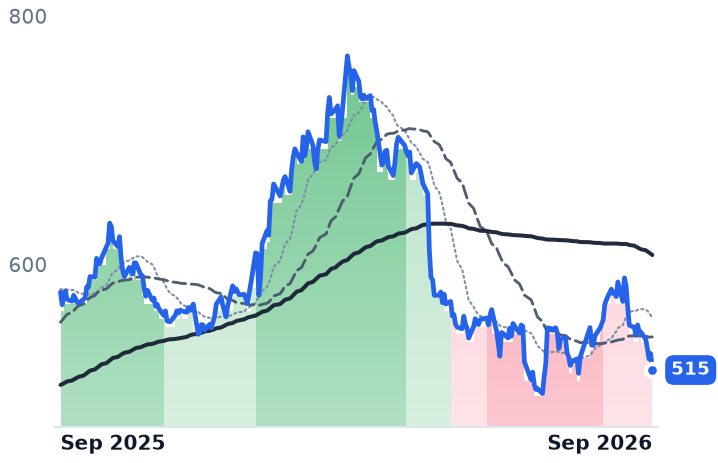
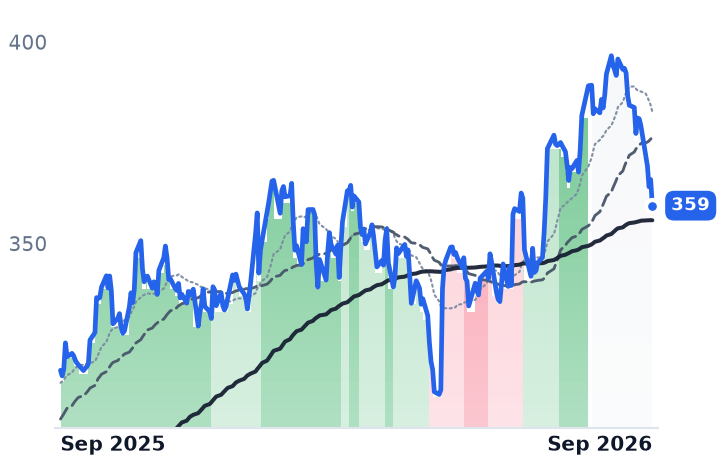
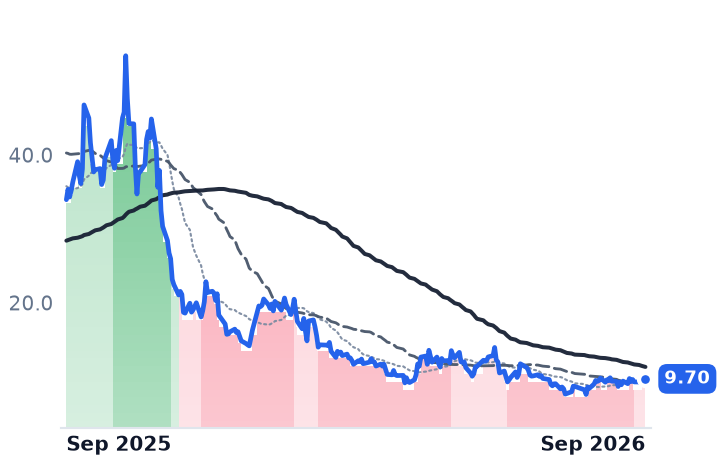
12-month price & trend
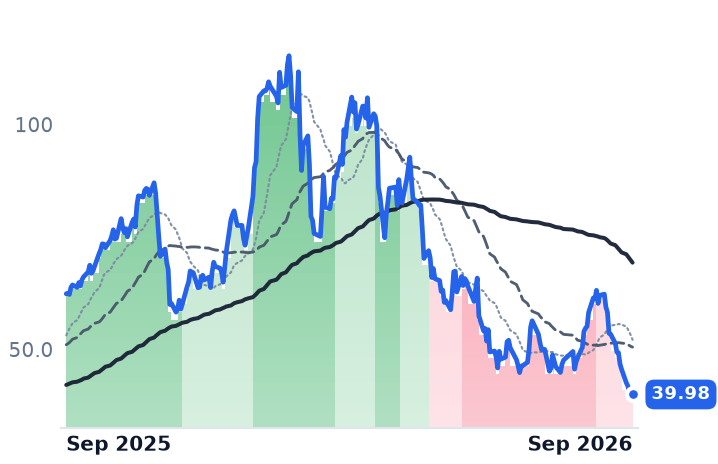
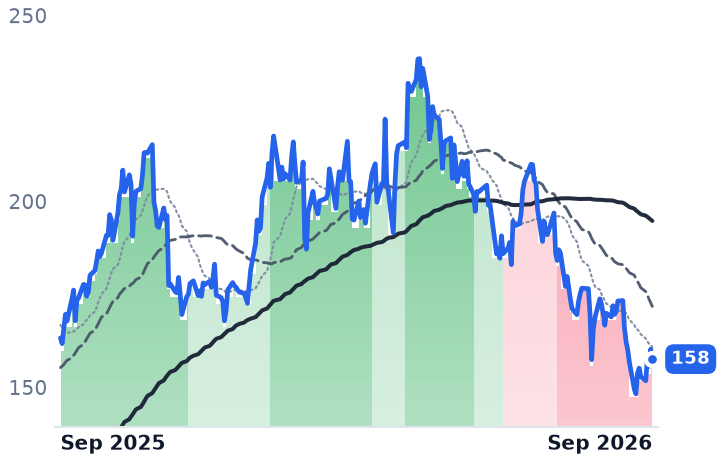
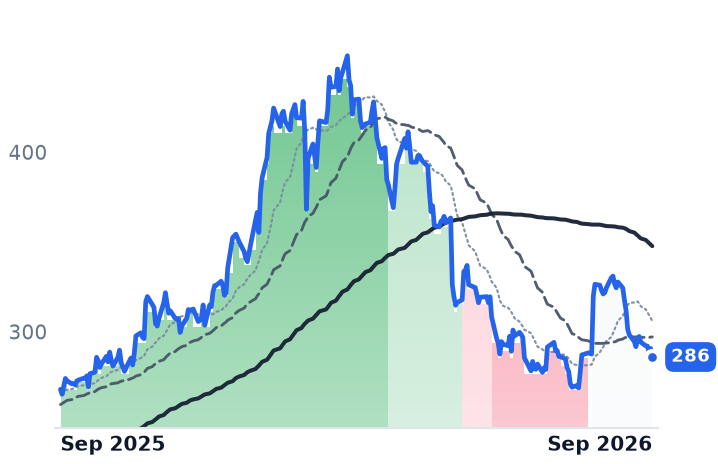
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KRMN | $5.3B | 140.3x | 68.1x | 9.0x | 7.2x | 21.6x | 17.2x | 42.9x | -0.5% |
BWXT | $14.4B | 40.6x | 33.2x | 4.1x | 3.8x | 18.6x | 17.2x | 28.6x | 2.2% |
HII | $11.3B | 17.0x | 15.3x | 0.9x | 0.8x | 6.8x | 6.7x | 12.7x | 3.3% |
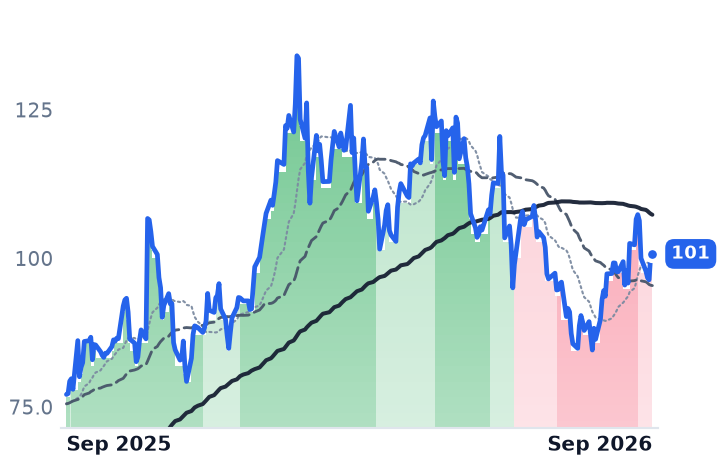
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCJ | $42.0B | 163.2x | 62.6x | 16.7x | 11.8x | 60.7x | 42.9x | 67.3x | 0.9% |
LMT | $119.0B | 24.8x | 17.2x | 1.6x | 1.5x | 16.1x | 15.3x | 17.0x | 4.8% |
NOC | $76.8B | 16.8x | 19.3x | 1.8x | 1.7x | 8.8x | 8.5x | 12.2x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GD | $90.5B | 20.8x | 20.1x | 1.7x | 1.6x | 11.0x | 10.7x | 15.2x | 6.9% |
SMR | $2.8B | n/m | — | 261.9x | 91.1x | — | 432.7x | n/m | -27.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KRMN | Revenue | +57.5% | +27.5% | +25.8% |
| EPS | +62.0% | +61.1% | +38.7% | |
BWXT | Revenue | +20.6% | +9.6% | +7.0% |
| EPS | +24.1% | +11.6% | +11.7% | |
HII | Revenue | +10.8% | +6.4% | +6.4% |
| EPS | +23.6% | +12.3% | +16.4% | |
CCJ | Revenue | +3.6% | +10.9% | +7.7% |
| EPS | +7.3% | +69.4% | +25.2% | |
LMT | Revenue | +6.1% | +5.4% | +5.5% |
| EPS | +38.4% | +7.1% | +6.2% | |
NOC | Revenue | +5.1% | +6.7% | +6.1% |
| EPS | +7.2% | +7.9% | +8.6% | |
GD | Revenue | +6.4% | +4.6% | +4.2% |
| EPS | +7.9% | +9.5% | +7.9% | |
SMR | Revenue | −26.7% | +434.9% | +101.2% |
| EPS | −74.7% | +33.4% | −18.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Karman Holdings makes the payload fairings, aerodynamic interstage structures and solid-propulsion units that sit inside missile-defense interceptors, hypersonic vehicles and launch vehicles. On its August 6 call it reported second-quarter revenue of $182.1m, up 58% from a year earlier. Every operating line moved with it: gross margin widened to 43% from 41%, operating income rose 73%, backlog reached $1.3bn, up 65%, and full-year revenue guidance went to $730m-745m.
Then the news stopped being about the business. Chief financial officer Mike Willis said he would step down, with Chris Boynton taking the seat on September 14; the company announced a secondary offering; and in early September the short seller J Capital published a report attacking Karman's disclosure of its serial acquisitions, a sequence AAII catalogued as the shares slid. Karman closed at $39.98 on September 4 against $54.71 a month earlier. That gap is the story — and it is also why a slice of the listed space-propulsion complex reads as though an industry is deteriorating when only one company is being repriced.
The neighbors did not move like this
The useful comparison is BWX Technologies, the sole qualified manufacturer of naval nuclear reactors and fuel for the U.S. Navy's submarines and carriers, which is grouped alongside Karman in propulsion. BWXT fell 7.2% over the same thirty days and is down 3.8% over twelve months. The defense primes were softer — Huntington Ingalls off 10.9%, Lockheed Martin 9.7% — in a month when the 30-year Treasury yield reached a 19-year high above 5.33%, which mechanically compresses what buyers pay for long-dated earnings across the whole group. Karman's 27% is several times any of that. Nothing sector-wide is doing this to it.
What the price was carrying
Even after the drop, Karman trades at 68.1x forward earnings and 140.3x trailing, at 21.6x trailing gross profit, and its trailing free-cash-flow yield is slightly negative. BWXT, growing far more slowly but converting cash, is at 33.2x forward and 18.6x trailing gross profit. A company that has been buying growth, does not yet self-fund it, and is changing finance chiefs is precisely the profile against which a disclosure attack does maximum damage — whether or not the attack is correct.
What the multiple was priced for is on the transcript. "Some customers are now citing demand to increase certain annual production buys by as much as a factor of 10x," chief executive Jonathan Rambeau told investors on August 6. "Which would dwarf earlier projections of 2, 3, or 4x multiples of current build rates."
The verdict
Split the decline in two. Karman traded at $97.14 in early March; the six-month slide from there is the unwind of a price that treated Rambeau's ten-fold scenario as booked rather than cited, and the reported business — accelerating revenue, widening margin, a raised forecast — argues that unwind was about the multiple rather than the operations. The August-September leg is different: a resignation, an equity sale and a short report inside five weeks are governance events, and they have hit a balance sheet that cannot yet fund its own growth.
What none of the available disclosure settles is the question the short report actually poses: how much of that 58% is acquired volume rather than organic demand, and how durable the accounting behind it is. Until that is answered in a filing, the growth rate and the multiple are arguing past each other.
Boynton signs his first quarterly numbers in his new job within weeks. That set of figures, more than any interceptor build rate, is what the stock is now trading on.