

Monolithic Power Samples 800-Volt Parts Now; Navitas Dates Its Rack Revenue to 2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Nvidia's biggest quarter yet did nothing for the chipmakers that supply power to its racks: the listed power and analog names sold off together in the week after the August 26 report, and the two most exposed to the coming high-voltage rack fell hardest.
Their businesses are not doing the same thing. Monolithic Power's enterprise data revenue reached $380.6m in the June quarter, up 164% from a year earlier, and it raised that segment's full-year growth outlook from 85% to 130%. Navitas earned no gross profit at all on $10.5m of revenue and puts its own 800-volt rack revenue in 2027.
One de-rating looks like the sector-wide valuation reset it sits inside; the other looks earned by the numbers.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | −12.7% | +42.4% |
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −15.0% | +110.3% |
| Compared against · context, not the story | |||||
VICR | Vicor | Other | 🟢 Cont. Bull | −14.8% | +272.9% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | −7.1% | +46.5% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | −9.7% | +42.0% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −12.4% | +15.3% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +2.9% | +36.9% |
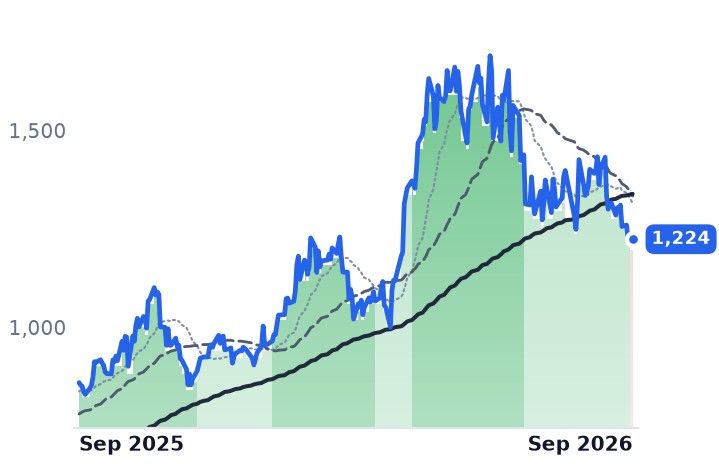
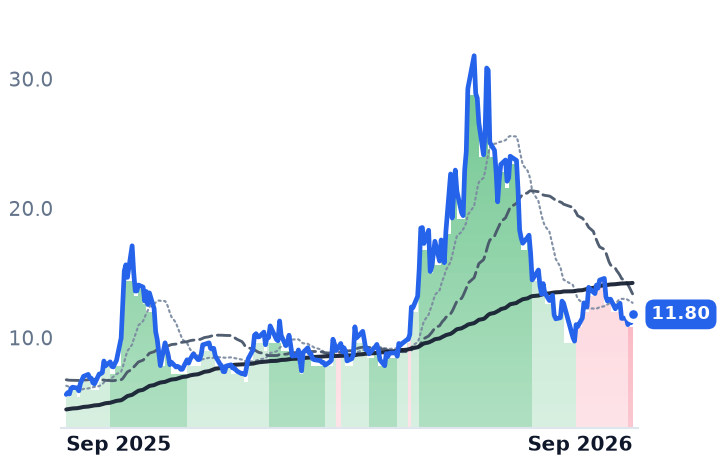
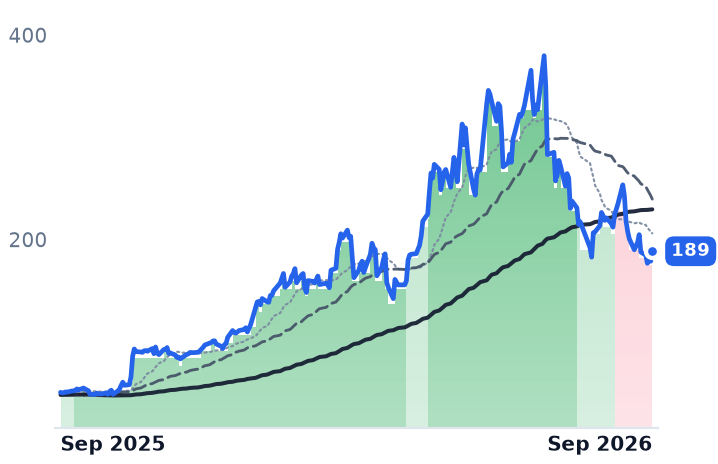
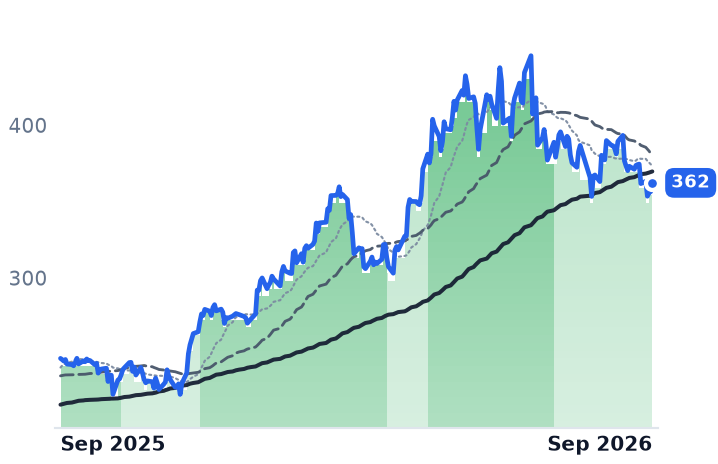
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $60.1B | 74.6x | 44.6x | 18.4x | 14.5x | 33.3x | 26.3x | 58.4x | 1.0% |
NVTS | $3.1B | n/m | — | 84.3x | 64.6x | — | — | n/m | -2.2% |
VICR | $8.9B | 61.8x | 57.4x | 18.9x | 14.8x | 33.3x | 26.2x | 66.6x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADI | $181.1B | 43.9x | 28.9x | 13.0x | 12.0x | 19.8x | 18.2x | 28.8x | 2.7% |
TXN | $258.4B | 42.8x | 33.4x | 13.3x | 11.8x | 22.8x | 20.2x | 29.5x | 2.1% |
MCHP | $40.2B | 102.6x | 20.3x | 7.8x | 6.3x | 13.0x | 10.4x | 26.9x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
ADI | Revenue | +37.7% | +21.9% | +11.1% |
| EPS | +65.6% | +29.0% | +17.0% | |
TXN | Revenue | +23.8% | +14.0% | +10.8% |
| EPS | +55.0% | +20.5% | +18.4% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
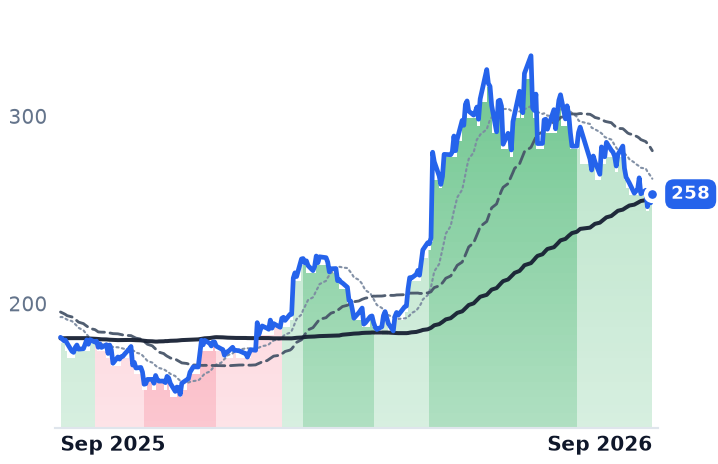
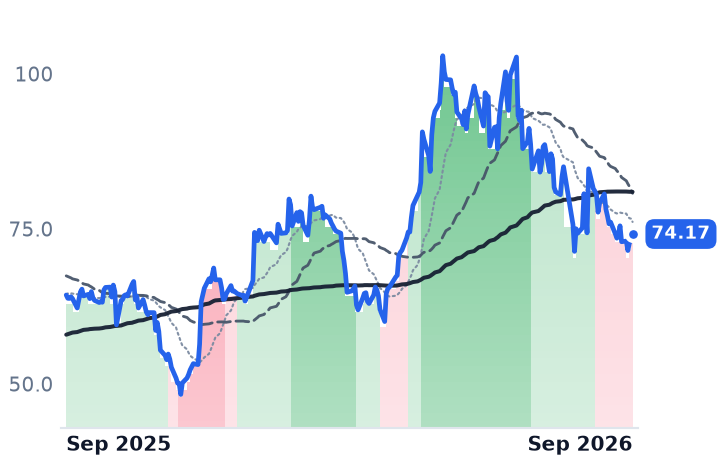
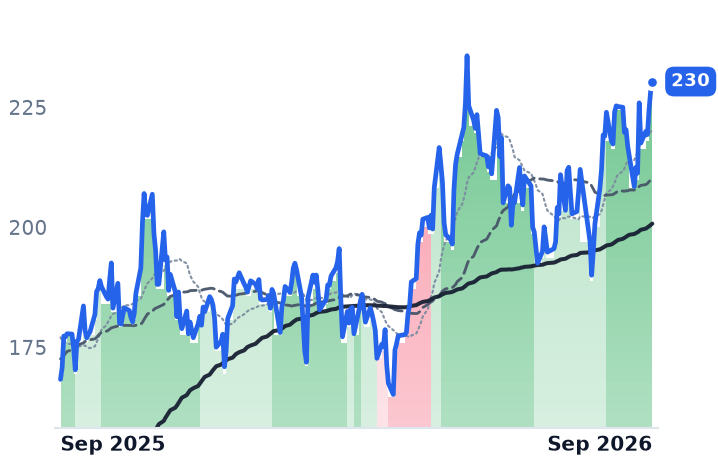
Nvidia reported data-center revenue of $89bn on August 26 and guided the October quarter to $108bn, including no China sales; its shares rose 8.7%, the biggest single-day gain since April 2025. Over the following week the semiconductor companies that convert wall current into the volts those accelerators actually run on broke down. Monolithic Power's shares fell out of the uptrend they had held since mid-July on September 2 and their trend readings turned sharply negative on September 4 — the same session Microchip's did. Navitas had gone first, on September 1; Vicor on August 12.
What is being repriced is dollars of power-conversion content per rack. No one buys "a power chip" — they buy watts delivered at a specified voltage, and that specification is changing. Nvidia's 800-volt direct-current architecture strips out conversion stages but makes every remaining stage more semiconductor-hungry, and it reaches full-scale production with the Kyber rack systems in 2027. Two listed companies sit on that socket from opposite ends of the income statement.
Paid now
Monolithic Power Systems, which sells direct-current voltage-regulation chips and modules into servers, cars and industrial gear, is the incumbent. June-quarter revenue was $980.6m, up 47.6% year on year — the fourth straight quarter of acceleration, from 18.9% a year ago. Enterprise data revenue was $380.6m, up 164.3% from a year earlier and 44.8% sequentially, and the company lifted its full-year growth outlook for that business from 85% to 130%. Gross margin held at 55.2% while operating margin widened 6.2 percentage points to 31.0%.
On the July 30 call, management described channel inventory as "very low," unlike the 2024 cycle, said book-to-bill was well above 1.0, and said enterprise data has "no concentrated customers." Founder-chief executive Michael Hsing called the company the "highest-power-density company in the world" in optical-transceiver power. Its answer to the architecture change is its own: 800-volt alternating-to-direct-current parts sampling on in-house silicon carbide rather than gallium nitride, and 48-volt vertical power modules ramping at more than a couple of customers. The board added $500m to the buyback, taking it to $1bn.
Paid in 2027
Navitas Semiconductor, a 190-employee designer of gallium-nitride and silicon-carbide power devices, is the option. June-quarter revenue was $10.5m, down 27.3% year on year though up 22.5% sequentially, and it has generated roughly minus $0.6m of cumulative gross profit across four quarters on $36.5m of sales. Management reports a 39.5% gross margin on a non-GAAP basis; the reported figure is negative, and the $228.2m net loss is dominated by a $203.1m non-cash earnout remeasurement against a $9.3m adjusted loss. Chief executive Chris Allexandre said the "Navitas 2.0" transformation is substantially complete, and chief financial officer Tonya Stevens said AI infrastructure would be a third or more of revenue by year-end.
The company's own timetable puts sidecar racks in mid-2027 and gallium nitride in accelerator-level conversion from late 2027. September-quarter guidance is $13.5m. It ended June with $557.4m of cash and no debt, having raised $373m at $21.89 a share — 46% above where the stock now trades — with diluted shares up 18.5% year on year. Its first US-made Gen 5 parts from GlobalFoundries' Vermont fab, announced September 1, are a qualification milestone rather than a sale.
The reset, not the socket
The obvious reading — that the customer is reassigning the power socket — does not survive the numbers. Over thirty days Navitas fell 15.0%, Vicor 14.8%, Monolithic Power 12.7%, Microchip 12.4%, Texas Instruments 9.7% and Analog Devices 7.1%, a spread far too narrow to isolate one company's loss, while Nvidia itself rose. The Philadelphia Semiconductor Index set a record on June 22 and then fell as much as 29% on light guidance elsewhere, yields and tariff threats. Every peak on this shelf landed inside five weeks from late May to end-June. And the socket was never single-sourced: Nvidia's published 800-volt list names ten silicon suppliers, both of these among them, plus five power-shelf vendors and Eaton, Schneider Electric and Vertiv.
So the two de-ratings are not the same event. Monolithic Power has given back a third of its price-to-trailing-gross-profit multiple, to 33.3x from 49.8x in May, while its fastest-growing segment more than doubled — the compression is the sector's, not the business's, though at 74.6x trailing and 44.6x forward earnings it still costs far more than Analog Devices at 19.9x gross profit. What it has not yet answered is Analog Devices' $1.5bn purchase of Empower Semiconductor, whose regulators sit under the accelerator and feed current vertically — the exact socket Monolithic Power is priced to own. Navitas at 84.3x trailing sales is a different case: nothing in the reported quarter refutes the de-rating, and consensus puts real growth in 2027-28.
Between here and the mid-2027 racks it is counting on, Navitas will report four more quarters. Monolithic Power will report the same four while shipping the parts.