

GoodRx Now Takes 31% of Revenue From Drugmakers as Discount-Card Sales Fall 26%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
GoodRx is being paid by a different party than it was a year ago. Fewer people use its discount card — monthly active consumers fell 12% to 5 million — and each one now generates roughly $21 of pharmacy-counter revenue, against about $25 a year earlier. Total revenue per user still rose to roughly $40, because drug manufacturers and subscribers fund the difference.
The consolidated line went backwards anyway: revenue slipped 1.3% and net income fell by a third, while the shares gained 22% over three months and trade at 11.4x forward earnings. Progyny, which administers fertility benefits for self-insured employers, is the mirror image — gross margin widened to 25.5% and operating income rose 64% — and its stock fell 17.6% in a month on a single soft quarterly guide.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
GDRX | GoodRx | Patient Engagement & Benefits | 🌱 Emerging Bull | −5.4% | −15.5% |
PGNY | Progyny | Patient Engagement & Benefits | 🌱 Emerging Bull | −7.7% | +13.5% |
| Compared against · context, not the story | |||||
HQY | HealthEquity | Patient Engagement & Benefits | 🌱 Emerging Bull | −8.2% | +3.2% |
HNGE | Hinge Health | Patient Engagement & Benefits | 🌱 Emerging Bull | +3.4% | +62.1% |
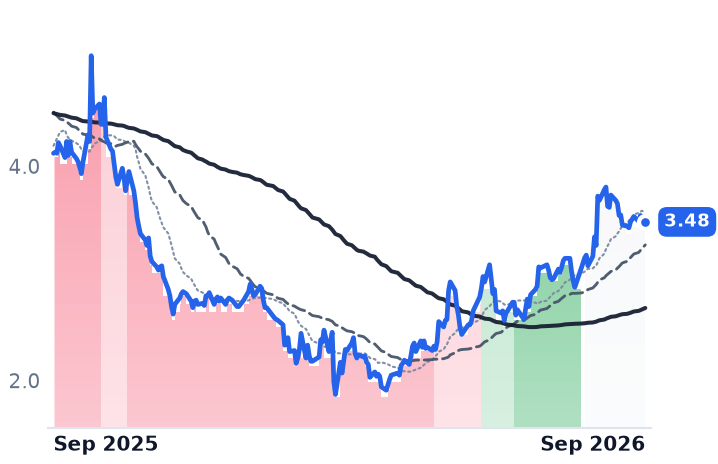
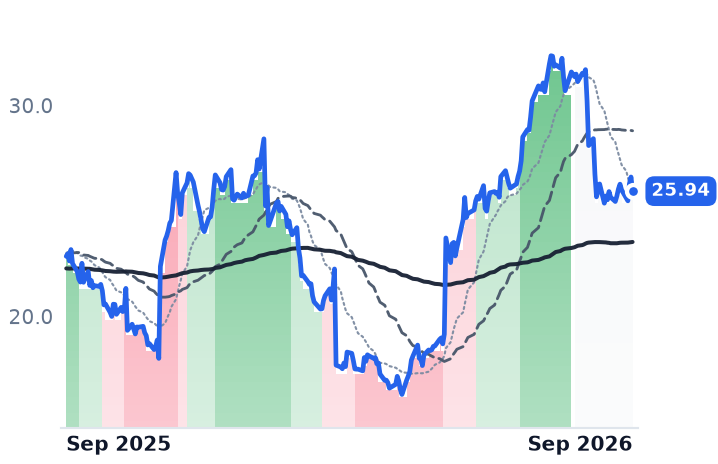
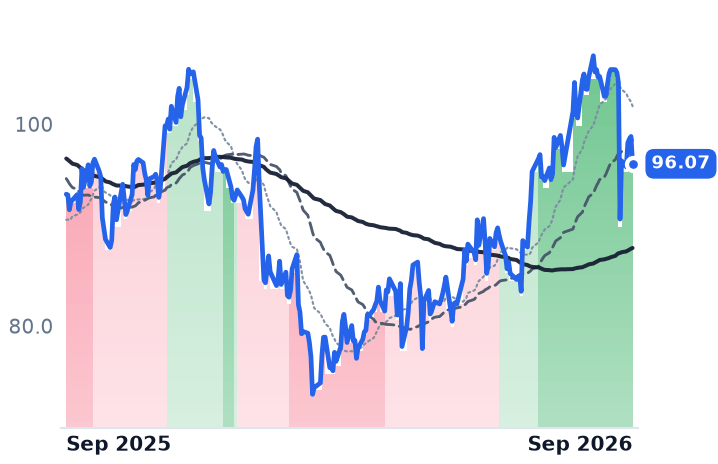
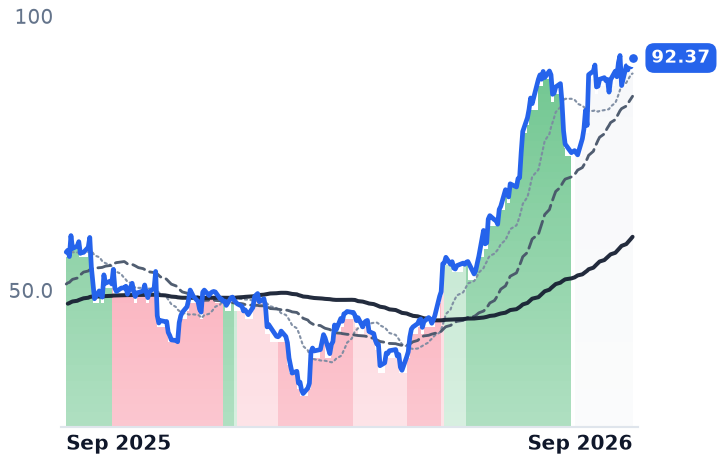
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GDRX | $1.2B | 66.2x | 11.4x | 1.5x | 1.5x | 1.7x | 1.7x | 9.8x | 12.1% |
PGNY | $2.0B | 26.7x | 20.2x | 1.6x | 1.5x | 6.3x | 6.0x | 15.0x | 10.7% |
HQY | $8.0B | 34.3x | 20.3x | 5.9x | 5.7x | 7.8x | 7.5x | 18.6x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HNGE | $7.1B | 68.6x | 39.3x | 9.9x | 8.3x | 11.7x | 9.8x | 66.7x | 4.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GDRX | Revenue | +0.6% | +5.0% | +6.7% |
| EPS | −15.6% | +17.1% | +15.5% | |
PGNY | Revenue | +7.6% | +10.0% | +6.4% |
| EPS | +95.2% | +18.2% | +11.4% | |
HQY | Revenue | +9.9% | +8.0% | +7.7% |
| EPS | +25.4% | +19.4% | +16.3% | |
HNGE | Revenue | +50.1% | +26.5% | +22.0% |
| EPS | +62.1% | +33.1% | +37.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
GoodRx does not sell drugs, insure anyone, or run a pharmacy. It drops a discount code into a cash-paying patient's transaction at the counter and is paid a share of the spread a pharmacy benefit manager captures on that fill. In the June quarter, that business shrank by roughly a quarter, to $106.4m.
What replaced it is money from the other end of the supply chain. Pharma Direct — manufacturer-funded pricing programs, 135 of them and counting, covering products including the Ozempic pill, Wegovy HD and the Zepbound KwikPen — grew 76% to $61.6m, or 31% of company revenue. Subscriptions rose 39% to $28.5m after the May launch of GoodRx Companion at $14.99 a month. Total revenue was $200.4m, down 1.3%, the fourth straight quarter of flat-to-negative growth; operating income fell 14.7% and net income 33.5%. The stake is which meter defines the company: the card toll, or the manufacturer's marketing budget.
The toll at the counter
The card business is being squeezed from three directions at once. Retail pharmacy is shrinking — Rite Aid closed every location by the end of September 2025 and Walgreens expects to close under 100 more stores in 2026. GoodRx's Integrated Savings Program, which embeds its pricing algorithm inside a PBM's own claims system so the pharmacy is reimbursed at the lowest rate in GoodRx's network, now reaches more than 60% of insured lives through CVS Caremark, Express Scripts and MedImpact — concentration that makes one partner's volume decision a company event. And the take per fill is coming down: the company attributed part of the decline to lower unit economics it expects to continue in the near term, the price of longer-dated contract certainty. Independent pharmacies have sued GoodRx and four PBMs, alleging a price-fixing agreement to suppress reimbursement.
The manufacturer channel routes around the card by design. On TrumpRx, the federal navigator site, a Zepbound offer sends the shopper to Eli Lilly's LillyDirect and Novo Nordisk buyers to NovoCare, at listed cash prices of $299 and $199 a month. GoodRx joined that site as a generics launch partner rather than fighting it. "Over $1 billion brand scripts are abandoned in any given year, which is just a drain on the health care system," chief executive Wendy Barnes told investors on August 6. Chief financial officer Justin Fengler said guidance implied the company "would return to year-over-year growth earlier than we had previously anticipated." Full-year revenue guidance is $790–805m with adjusted EBITDA of $240–250m.
The shares rose 14.1% on the print and are up 22% over three months, still 19% below a year ago. They fetch 11.4x forward earnings against 66x trailing, 9.75x trailing EV/EBITDA and a 12.1% free-cash-flow yield — but consensus has 2026 revenue up 0.6% and earnings per share down 15.6%, and sell-side targets moved by about a dollar apiece. The discount is paying for the disintermediation, not overlooking it.
The mirror meter
Progyny bills the opposite way: covered lives times utilization times the cost of a fertility cycle it administers at a spread, sold to self-insured employers. Revenue grew 5.3% to $350.5m — 11% excluding a large client whose transition agreement expired on June 30 after contributing $48.5m in 2025. Gross margin widened to 25.5% from 23.7%, and operating income rose 64%. "Retention across our existing book of business, led by our largest clients... has largely derisked client turnover for 2027," chief executive Peter Anevski said on August 6, adding that early new-sales commitments pace ahead of last year. The company expects over 600 clients and roughly 7.2 million covered lives once 2026 signings are live, and has repurchased 10.8 million shares since November.
The stock fell 17.6% in a month because third-quarter revenue was guided near $340m, about 3% under consensus, on summer engagement seasonality. It trades at 20.2x forward earnings against 26.7x trailing, and its enterprise value — $2.03bn of market capitalization less $237m of net cash — is about 7.6x the midpoint of full-year adjusted EBITDA guidance.
What the two prints settle
GoodRx's advance is earned by mix and nothing else: the consolidated statements got worse, and the case rests entirely on manufacturer and subscription revenue compounding faster than the counter shrinks. That is a real pivot with a live threat attached, because the same manufacturers funding Pharma Direct are building checkouts that skip the pharmacy. Progyny's decline has no operating fact behind it — spread, retention and margin all improved — which leaves one quarter's seasonality against a January 2027 selling season management says is already largely locked.
One detail complicates the scoreboard. GoodRx told investors that monthly active consumers "isn't necessarily an indicator of success" under a subscription model, and is designing a replacement metric for 2027. The number that shows the card being disintermediated is the number about to be retired.