

Black Rifle Locked 2026 Coffee at $2.95 a Pound; Westrock Passes Its Beans Through
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
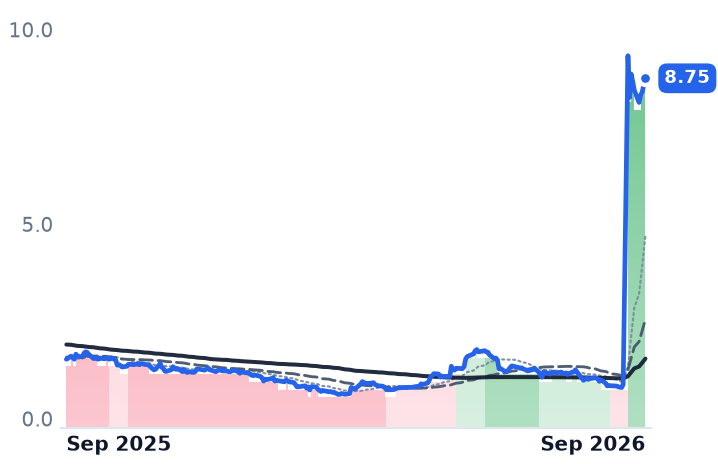
Black Rifle Coffee's shares look like they gained 718% in a month. They did not: a 1-for-10 reverse split took effect on August 21, and adjusted for it the stock is lower than a month ago and roughly 42% below a year ago, on a market value unchanged at $278m.
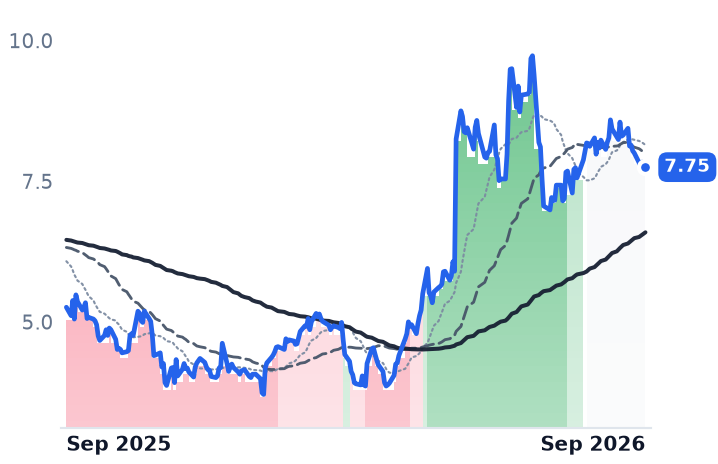
What actually changed is the bean. Arabica has fallen from a record $4.41 a pound to about $3.10 as Brazil finishes a record harvest, and the tariff on Brazilian coffee came off last November. The relief lands in opposite places. Black Rifle buys beans and sells bags, and its gross margin expanded to 34.1% last quarter. Westrock Coffee is a contract manufacturer that bills a conversion fee and passes the commodity through, so coffee moves its revenue but never its gross profit — and Westrock, up 91% in six months on a record quarter of cash earnings, is the pair's real winner.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BRCC | BRC | Coffee & Beverages | 🌱 Emerging Bull | +810.1% | +471.9% |
WEST | Westrock Coffee Company, LLC | Coffee & Beverages | 🌱 Emerging Bull | −4.2% | +47.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BRCC | $278.4M | n/m | 47.3x | 0.6x | 0.6x | 1.9x | 1.9x | 87.5x | 2.8% |
WEST | $756.1M | n/m | — | 0.6x | 0.6x | 4.6x | 4.9x | 23.8x | -2.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BRCC | Revenue | +9.3% | +8.0% | +16.6% |
| EPS | −118.5% | +337.8% | +9.9% | |
WEST | Revenue | +5.9% | +7.7% | — |
| EPS | −49.5% | −106.6% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cost shock is over
Brazil is finishing a record coffee harvest, and the input-cost shock that defined the industry for two years has broken with it. Arabica set a record at $4.41 a pound in February 2025, held above $4 again last October, and traded near $3.10 in early September, with more than 90% of a Brazilian crop of roughly 75 million bags already picked. The 40% U.S. tariff on Brazilian coffee was eliminated by executive order on November 20, retroactive to the 13th.
The two listed American coffee companies book that relief in different places. Westrock Coffee owns no consumer brand: it procures green coffee and roasts, extracts and cans it for retailers, restaurants, convenience chains and packaged-goods customers, on contracts that pass the commodity through with a conversion fee attached. The bean inflates and deflates its revenue without ever touching its gross profit. Black Rifle Coffee buys the bean and sells the bag — through grocery, mass and convenience retail, its own cafés and e-commerce — at shelf prices that move slowly. For Black Rifle, the coffee price is the margin.
The split that looks like a rally
Black Rifle's shares appear to have gained 718% in a month. They did not. The company executed a 1-for-10 reverse stock split effective August 21, with Class A stock trading on a split-adjusted basis from August 24 under the same ticker. The New York Stock Exchange had notified the company in February that it sat below the $1.00 minimum price; compliance was regained in late May, and the split went ahead regardless. Market value is unchanged at $278m. Split-adjusted, the stock is down about 15% over a month and 42% over a year.
The business went the other way. Second-quarter revenue rose 12.8% to $107.0m and gross margin expanded to 34.1% from 33.9% on pricing and lower shipping and fulfillment costs. Operating income was positive at $1.1m against a $12.6m loss a year earlier, and adjusted EBITDA more than doubled to $6.3m. The compression coffee was supposed to cause already happened — annual gross margin fell from 41.2% in fiscal 2024 to 34.6% in fiscal 2025 — and it is reversing, with all of 2026's green coffee secured at $2.95 a pound and more than half of 2027 at $2.65. Growth is coming from distribution rather than price: wholesale revenue grew 15.2% and retail presence reached 56.5% of all-commodity volume, while cafés shrank. "We believe in building a better business before we build an aggressively bigger business," president and chief executive Chris Mondzelewski said with the results.
The equity prices none of it. Black Rifle trades at 0.65 times trailing sales and 0.64 times forward — no spread between the business behind it and the one consensus models ahead. On cash earnings it is not cheap, at 87.5 times trailing EBITDA. And the reverse split sits on top of genuine dilution: the diluted share count has grown roughly 24% since fiscal 2025.
Westrock is the pair's actual winner
Westrock's pass-through mechanics show up in one line of its annual accounts: fiscal 2025 revenue rose 39.8% to $1.19bn while gross profit fell 20.2%, dragging gross margin from 18.1% to 10.3%. That optic is now unwinding with the coffee price — second-quarter revenue grew only 8.8%, to $305.7m. Gross margin fell to 12.3% from 14.7%, but $4.1m of the shortfall is incremental depreciation on newly commissioned assets running through cost of sales, plus a $2m mark-to-market loss in the green-coffee sourcing segment. First-half gross profit was $83.5m, up 19%.
Those assets are the $315m Conway, Arkansas roast-to-ready-to-drink plant, 570,000 square feet, whose five extract and canning lines were all commercialized by the first quarter. The quarter they produced was a record: adjusted EBITDA of $21.3m, up 39%; free cash flow of $20.2m, a quarter earlier than promised; leverage down to 3.36x, a fifth consecutive quarter of improvement. "We're on pace for estimated capital expenditures in 2026 of approximately $30 million, down from the $160 million in 2024 and $89 million in 2025, which again represents a structural shift in the capital profile of this company," chief financial officer Chris Pledger told investors on the August 6 call. Guidance of $90–100m of adjusted EBITDA for the year was reaffirmed.
The shares have followed, up 91% in six months. They carry 23.8 times trailing EBITDA, and price against gross profit rises from 4.62 times trailing to 4.89 times forward — investors are paying more for next year's gross profit than for last year's, which happens only when a ramp is already in the price. Consensus still models a $33.6m net loss for 2026, with the crossover to profit in 2027.
What the bean explains and what it doesn't
Cheaper coffee has sorted these two, and the quoted prices point the wrong way about which one it favored. Westrock has earned its six-month gain in cash: the plant is built, capital spending has collapsed to maintenance-plus, and every dollar of coffee inflation it ever booked belonged to a customer. What it has not yet earned is the forward multiple, which assumes the remaining Conway capacity fills. Black Rifle is the mirror image — revenue accelerating, margin expanding, operating income positive two quarters running, against a share price 42% below a year ago that no reported result explains. The likelier reading is that a nano-cap trading under a dollar, with an activist holding 12.2% of the class and a growing share count, was being priced as a financing question rather than a coffee one.
For two years, the answer to almost any question about either company was the price of the bean. Black Rifle has now bought its next two crops forward, and Westrock never owned the risk to begin with. Whatever decides these two from here, coffee will not.