

Vistra Sold Forward 94% of Its 2027 Power, Locking Out Higher Prices Until 2028
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Vistra's second quarter looked like the artificial-intelligence power trade working: adjusted EBITDA — earnings before interest, tax, depreciation and amortization — rose 30% to $1.77bn and full-year guidance was reaffirmed. The company's own hedge disclosure explains why that cannot repeat on the way up. Nearly all of 2026's expected output and most of 2027's is already sold at prices struck in earlier years, and roughly 72% of 2028 is too, so a higher forward curve reaches reported margin only on the unhedged tail.
Texas is why it matters now. Houston round-the-clock power averaged $33/MWh in the quarter, 8% below a year earlier, and NRG, which built its year on a $52 assumption, watched Texas earnings fall $131m. Vistra's business has not deteriorated; NRG's has. Both shares are lower than a year ago, at 17.3x and 13.4x forward earnings respectively.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +5.5% | −20.3% |
NRG | NRG Energy | Integrated Retail & Generation | ⚠️ Emerging Bear | −0.0% | −18.9% |
| Compared against · context, not the story | |||||
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | +9.2% | −5.2% |
TLN | Talen Energy | Wholesale Power Producers | 🔴 Cont. Bear | −9.7% | −21.5% |
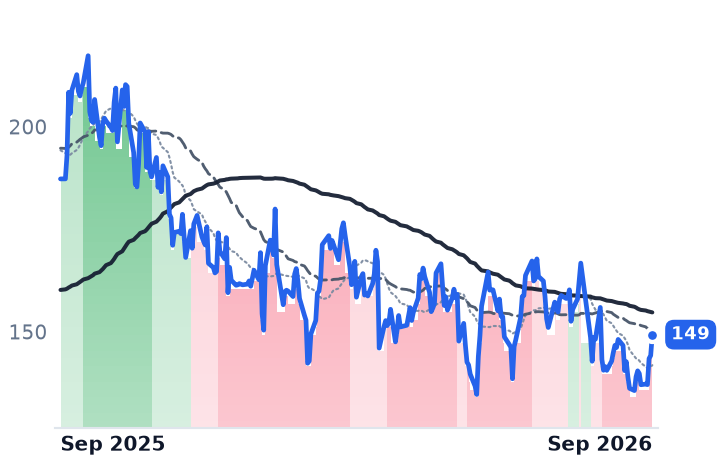
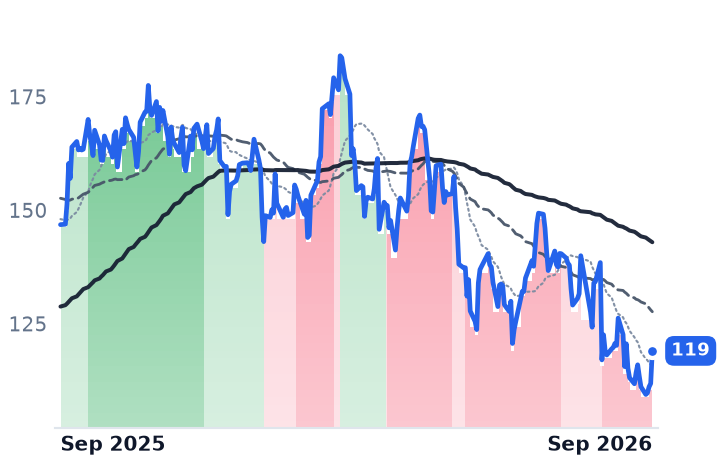
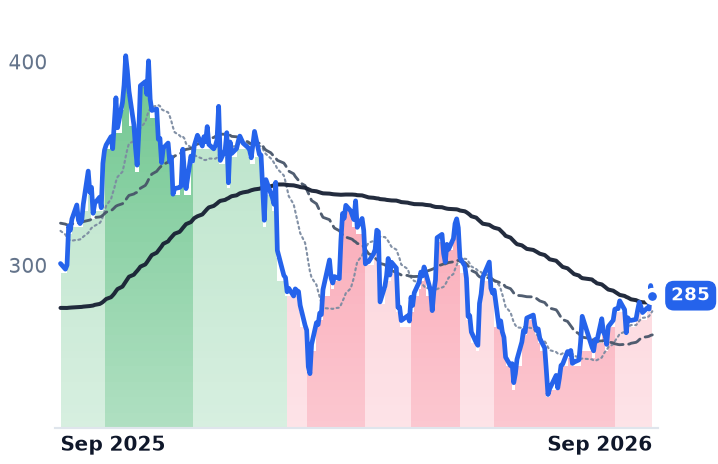
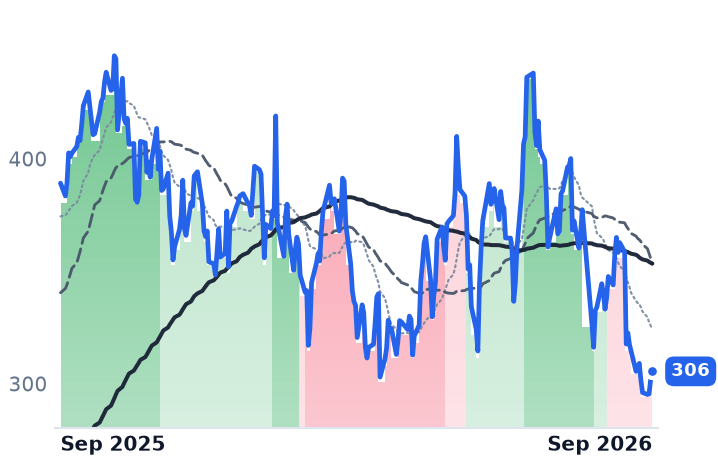
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VST | $50.3B | 24.9x | 17.3x | 3.2x | 2.2x | 24.3x | 17.3x | 10.8x | 2.7% |
NRG | $25.1B | 31.2x | 13.4x | 0.7x | 0.7x | 4.2x | 4.4x | 11.5x | 1.4% |
CEG | $107.4B | 29.1x | 24.8x | 3.4x | 3.2x | 3.6x | 3.4x | 15.4x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $14.4B | n/m | 15.4x | 4.1x | 3.2x | 9.1x | 7.2x | 29.9x | 3.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.6% | +15.4% | |
CEG | Revenue | +36.6% | +2.6% | +5.5% |
| EPS | +28.7% | +10.1% | +26.3% | |
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vistra had sold forward roughly 94% of the electricity it expects to generate in 2027, and about 72% of 2028, as of August 3, according to its second-quarter earnings release. Expected 2026 generation was essentially fully hedged. Those three percentages decide more about the next two years of reported profit than any data-center announcement will.
Vistra runs about 38,700 MW of nuclear, gas, coal, solar and battery capacity and sells power and gas retail to roughly 4.3 million customers in 20 states. It does not sell electricity at the forward curve the artificial-intelligence narrative trades on. It sells at prices struck one to three years earlier, and its retail arm is a deliberate counterweight whose margins widen when wholesale prices fall. The scarcity everyone is pricing therefore arrives on a delay — and when it arrives, it lands only on the open tail, which does not begin to widen until 2028.
The ladder cuts both ways
That is why the quarter held. Adjusted EBITDA rose about 30% to $1.77bn, generation EBITDA up 68% to $994m against $773m from retail, on realized prices roughly 5% higher per megawatt-hour — while spot power in Texas went the other way. Houston round-the-clock power averaged $33/MWh, 8% below a year earlier. Vistra reaffirmed 2026 guidance of $6.8bn-$7.6bn in adjusted EBITDA.
The softness is physical, not seasonal noise. Chief executive Jim Burke told analysts on the August 7 call that the market was showing a "recency bias" from weather plus a significant influx of batteries performing below expectations. Management pointed to July 22, when the market cleared at $57/MWh despite tight availability, and suggested it could have cleared $400-$500 absent battery competition. Vistra's 2027 range of $7.4bn-$7.8bn is now trending toward the lower end on a declining ERCOT forward curve, partly offset by stronger PJM prices and the nuclear production tax credit's price floor.
What is actually contracted, and when it pays
The merchant frame misses real signed business. Vistra holds 20-year agreements supplying Meta with more than 2,600 MW of PJM nuclear output and a separate 20-year, 1,200 MW arrangement at Comanche Peak in Texas, and in August won approval for Cogentrix, ten gas plants totaling 5,500 MW for a net $4.0bn. None of it sits in the 2027 range; management calls the Meta contract and Cogentrix together worth roughly $700m.
Capacity revenue offers no rescue either. PJM's auction announced July 14 cleared at $325 per megawatt-day, 2.5% below the prior $333.44, and did so at the approved administrative cap while falling 6,831 MW short of PJM's own reliability requirement. ERCOT, an energy-only market, holds no capacity auction at all. Meanwhile Texas ordered a verification audit of every data center in ERCOT's interconnection queue — about 474 GW of requests, some 90% of them data centers — which the grid operator aims to finish by December 10. Vistra's own realistic estimate is 12-15 GW of large-load additions in ERCOT by 2030.
The other engine is winding down. Vistra has repurchased about $6.5bn of stock since November 2021, cutting the diluted count from 482.2m in 2021 to 339.8m in 2025, with roughly $1.2bn of authorization left that it expects to exhaust no later than the end of 2027. Operating income fell 78.6% in 2025 to $1.34bn.
Where the group trades
The shares are down 21.3% over twelve months to $149.30, 31.5% below their 52-week high, at 17.3x forward earnings against 24.9x trailing and 10.8x trailing EV/EBITDA. Constellation Energy, which raised 2026 guidance to $11.50-$12.50 a share and signed roughly 920 MW of nuclear contracts at an 18.5-year average tenor, commands 24.8x forward and is down just 3.3% over the year. NRG, the more retail-weighted operator serving about six million customers, is the cheapest at 13.4x forward against 31.2x trailing — and has earned it: Texas EBITDA fell $131m, adjusted earnings per share slipped to $1.49 from $1.73, and its diluted share count rose from 190.4m to 210m as LS Power stock consideration swamped $932m of buybacks. Its headline 1.2 GW hyperscaler plant is still only aligned on principal commercial terms, pending a final investment decision, with operation targeted for late 2029.
The verdict
The division is not contracted versus merchant. Talen Energy is contracted — 1,920 MW to Amazon through 2042 — and fell 16.7% over the year, because its volume ramp is 840-1,200 MW in 2029 building to 1,920 MW by 2032. What is being discounted is anything dated 2029 and later, in favor of realized earnings now. On that test Vistra's de-rating is unexplained by its results and NRG's is not: one reaffirmed guidance with earnings up 30%, the other planned on $52 power and got $33.
The same hedge book that carried Vistra through a soft Texas summer is what will keep it out of a strong one. The first genuine choice management faces is what to do with the roughly quarter of 2028 still unsold — and that choice gets made long before any of the announced load actually plugs in.