

Palo Alto Guided Security Growth to 22% After CyberArk Lifted It to 63%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two platform security vendors reported five days apart, and their headline growth metrics are not measuring the same thing. Palo Alto Networks' next-generation security annual recurring revenue reached $9.10bn in the fiscal fourth quarter reported September 1, up 63% — but its own fiscal 2027 guidance of $11.075bn-$11.175bn implies 22-23% growth, the deceleration that arrives when CyberArk and Chronosphere sit on both sides of the comparison.
CrowdStrike's 25% recurring-revenue growth carries no acquisitions, accelerated for a fourth straight quarter on revenue, and came with free cash flow up 33% — cash growing faster than committed revenue. The market pays for the difference: CrowdStrike trades near 173x forward earnings against Palo Alto's 93x. One company bought consolidation; the other sold it. Only one is priced as though it never slows.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
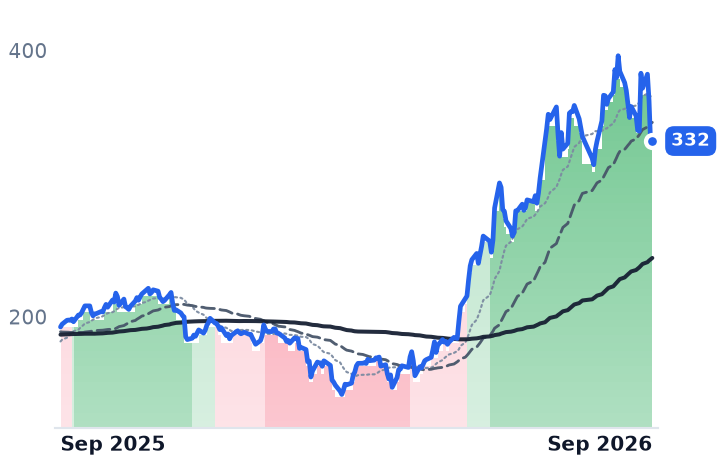
CRWD | CrowdStrike | Cybersecurity & Threat Protection | 🔴 Cont. Bear | +1.6% | −47.5% |
| Compared against · context, not the story | |||||
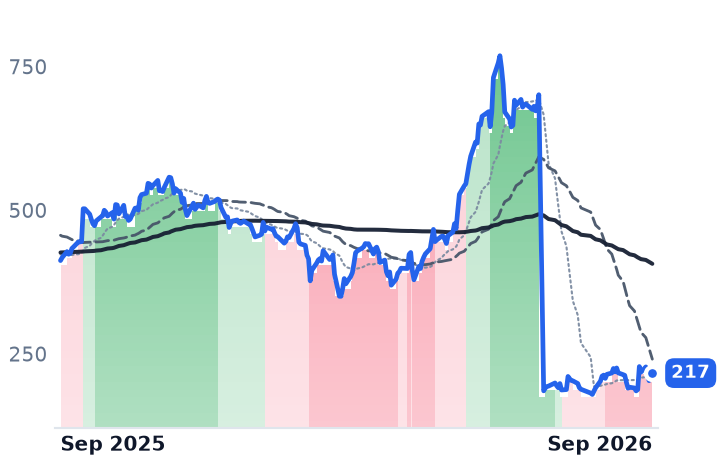
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −9.3% | +72.6% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | −3.7% | +35.5% |
ZS | Zscaler | AI & Data Intelligence | 🔴 Cont. Bear | +9.5% | −33.7% |
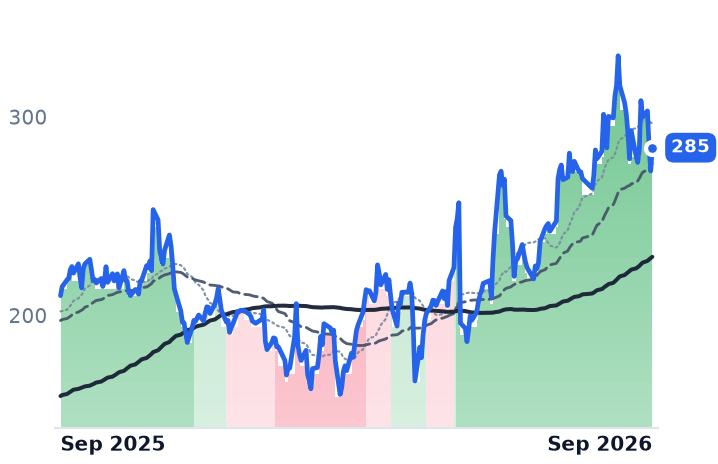
FTNT | Fortinet | Network Security Appliances | 🌱 Emerging Bull | −5.8% | +104.6% |
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +14.9% | +89.9% |
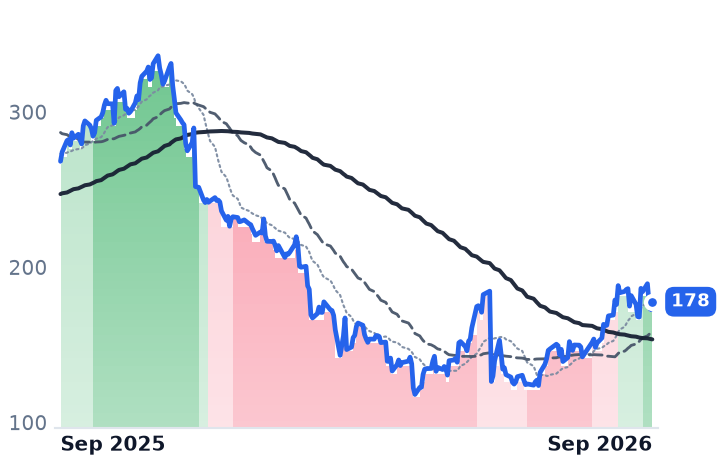
S | SentinelOne | Cybersecurity & Threat Protection | 🌱 Emerging Bull | −6.5% | +9.1% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +4.1% | +0.8% |
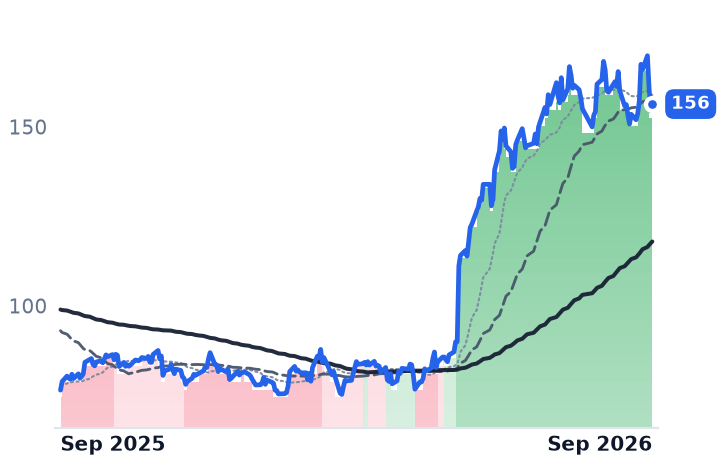
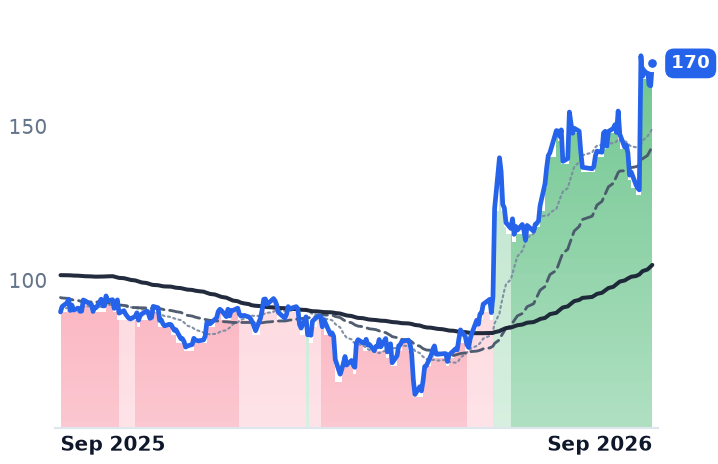
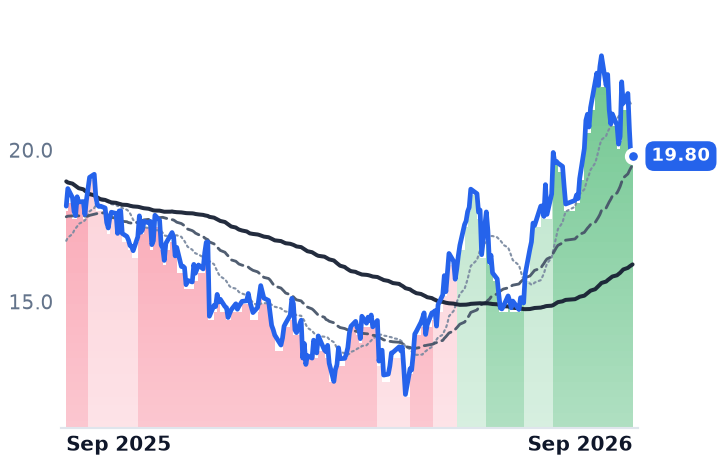
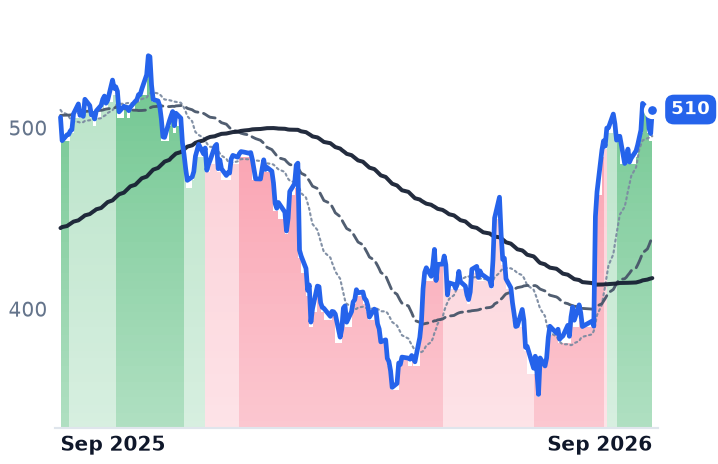
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PANW | $311.4B | 321.1x | 93.3x | 29.4x | 22.5x | 40.8x | 31.3x | 136.5x | 1.4% |
CRWD | $220.4B | — | 172.7x | 40.8x | 36.7x | 54.3x | 48.8x | 495.1x | 0.7% |
NET | $106.4B | n/m | 237.7x | 42.3x | 37.1x | 58.3x | 51.1x | — | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZS | $30.5B | n/m | 41.1x | 9.6x | 7.8x | 12.5x | 10.2x | 257.4x | 3.2% |
FTNT | $122.1B | 58.1x | 48.3x | 16.2x | 15.0x | 20.2x | 18.7x | 41.3x | 2.6% |
OKTA | $27.6B | 98.4x | 42.3x | 9.0x | 8.6x | 11.5x | 11.0x | 68.3x | 3.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
S | $7.2B | n/m | 61.3x | 6.9x | 6.0x | 9.3x | 8.1x | n/m | 0.6% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PANW | Revenue | +24.3% | +21.2% | +14.2% |
| EPS | +15.4% | +8.4% | +17.5% | |
CRWD | Revenue | +22.2% | +24.9% | +22.5% |
| EPS | −1.2% | +35.0% | +27.2% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.0% | +32.5% | +35.3% | |
ZS | Revenue | +25.2% | +16.9% | +16.6% |
| EPS | +29.2% | +11.1% | +17.3% | |
FTNT | Revenue | +20.1% | +11.4% | +11.1% |
| EPS | +27.8% | +9.4% | +13.3% | |
OKTA | Revenue | +12.0% | +10.8% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
S | Revenue | +22.4% | +19.9% | +17.6% |
| EPS | +723.4% | +83.7% | +43.0% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Palo Alto Networks reported its fiscal fourth quarter on September 1 with the best growth number in its recent history — next-generation security annual recurring revenue up 63% to $9.10bn, nearly $1bn of it added in the quarter, on revenue of $3.41bn and remaining performance obligations of $21.2bn. The guidance published alongside it says most of that lift does not repeat. The company set fiscal 2027 next-generation security recurring revenue at $11.075bn to $11.175bn, growth of 22% to 23%.
The gap between the two figures is the CyberArk and Chronosphere acquisitions rolling into the year-ago base. That matters beyond one guidance line, because both of the largest platform security vendors are selling the same idea to the same budgets — consolidate a dozen point products into one subscription — and the question a buyer of either stock is answering is whether the vendor consolidates by acquiring the products or by selling more of its own.
What the acquired route costs
Palo Alto, the $311bn Santa Clara maker of hardware and software firewalls and the subscription services layered on them, run by Nikesh Arora with 21,491 employees, shows the price of the first route in two places. In the April quarter, revenue grew 31.1%, but roughly 14% of that was organic once CyberArk and Chronosphere are stripped out. And gross margin fell to 67.6% from 74.2% two quarters earlier, as purchase-accounting amortization from the deals landed in cost of revenue.
What the organic route produced
CrowdStrike, the Austin cloud security vendor whose Falcon platform sells endpoint, identity, cloud-workload and log-management modules on subscription, reported its July quarter on August 26: revenue up 25.8% to $1.471bn, a fourth consecutive quarter of acceleration, with none of it bought. Gross margin widened to 74.6% from 73.5%. Recurring revenue reached $5.84bn, up 25%, and net new recurring revenue was a record $332.8m, up 51%.
The number that answers the standing bear case — that Falcon Flex, the pooled multi-year commitment customers reallocate across modules at will, books commitments faster than it collects cash — is the cash line. Free cash flow was $377m, up 33% and 26% of revenue, growing faster than the recurring revenue it supposedly outruns. Both gross and net dollar retention rose sequentially, and 51% of subscription customers now run six or more modules, 35% seven or more.
"We are in an arms race. AI is driving more cyber attacks. AI is driving more cyber spending," co-founder and chief executive George Kurtz told investors on the August 26 call. The company raised its full-year net new recurring revenue growth outlook by 630 basis points to 34% and lifted revenue guidance to $5.99bn-$6.01bn.
The premium
CrowdStrike shares, split four-for-one effective July 2, are up roughly 110% over twelve months on a comparable basis, rose 20.5% the day after results to a record close, and have since eased about 5% from that high. The stock trades at 172.7x forward earnings and 54.3x trailing gross profit, against roughly 32x gross profit in early May. Palo Alto trades at 93.3x forward earnings and 40.8x trailing gross profit.
So the market pays CrowdStrike an 85% premium on forward earnings for growth that is slower on the headline and cleaner underneath. That premium is earned on the composition — organic, accelerating, cash-converting — and nothing in the results explains its near-doubling in four months. Palo Alto's problem is the mirror image: its guidance concedes the underlying rate, and a 22% grower carrying purchase-accounting drag is a different security company from the one the 63% print described.
Palo Alto's next quarterly report is the first in which CyberArk appears on both sides of the year-over-year line. That is when the acquired growth stops flattering the comparison and starts having to be sold.