

Church & Dwight Grew 5.8% on Volume as Clorox Guided to $200m of New Inflation
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
For three years, growth in branded cleaning came from raising list prices while units leaked to private label. Two guidance statements three days apart show the halves have swapped hands — and only one company is on the right side of it.
Church & Dwight's June-quarter organic sales rose 5.8% on volume of 4.3%, after a March quarter in which price and mix actually subtracted 0.3 points; it has raised its 2026 organic outlook twice, to 4-5% from 3-4%. Clorox's fiscal 2027 organic guide of 3.5-4.5% contains more than 3.5 points of pure arithmetic from lapping the inventory drawdown that followed its software conversion, leaving underlying units near zero — and it is reopening the pricing lever against inflation it says will exceed $200m, more than double its normal range.
The name with the volume trades at 26.1x forward earnings and its shares are down over six months. The name without it trades at 16.2x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
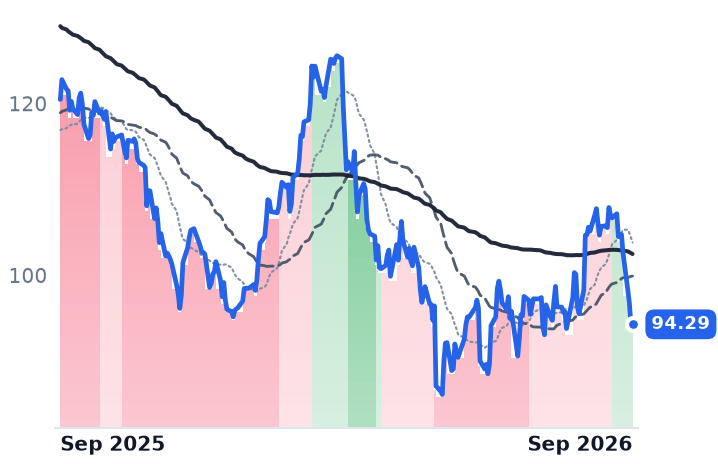
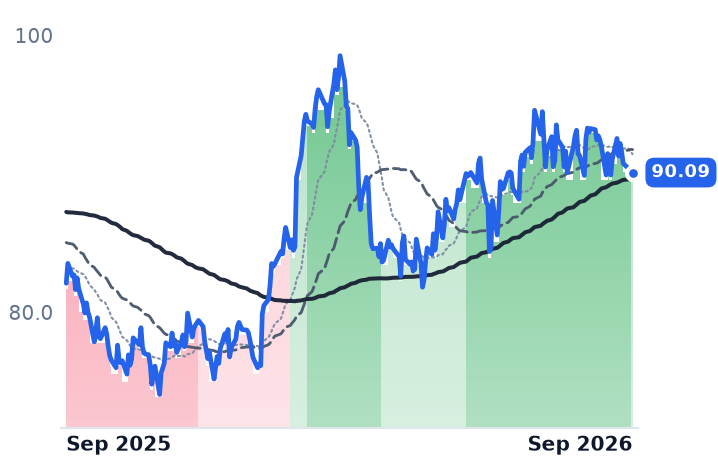
CLX | The Clorox | Home Care & Cleaning | 🔴 Cont. Bear | −10.0% | −21.7% |
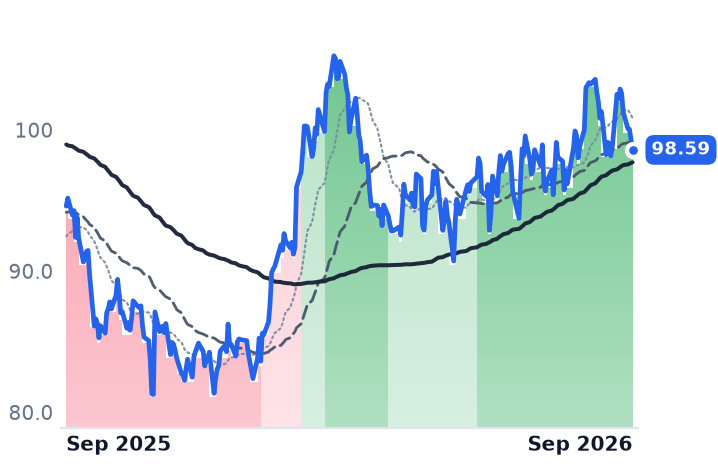
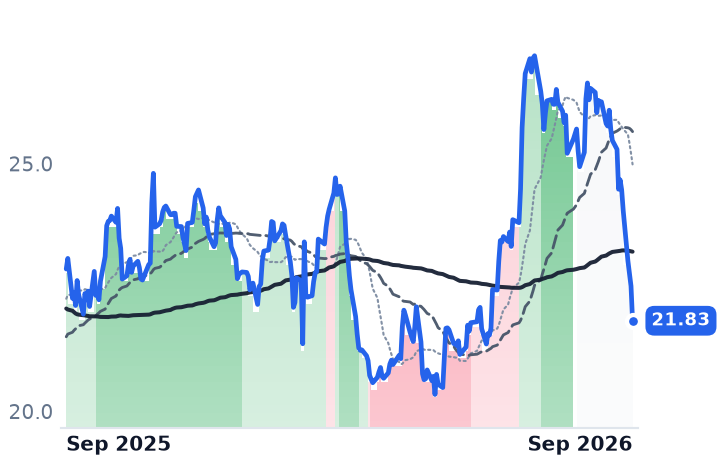
CHD | Church & Dwight | Home Care & Cleaning | 🌱 Emerging Bull | −4.4% | +4.2% |
| Compared against · context, not the story | |||||
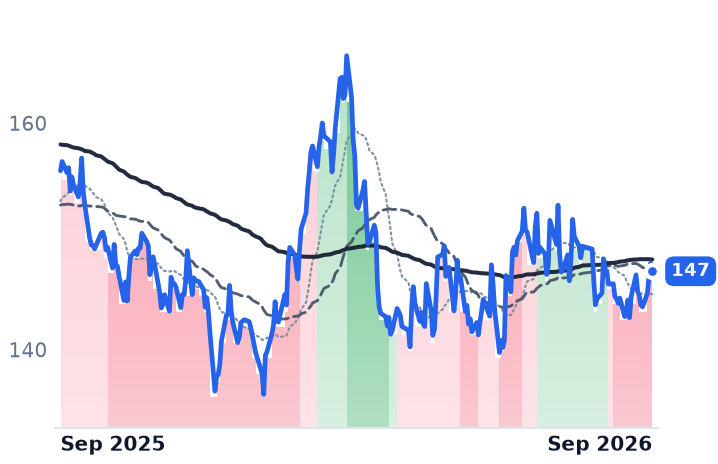
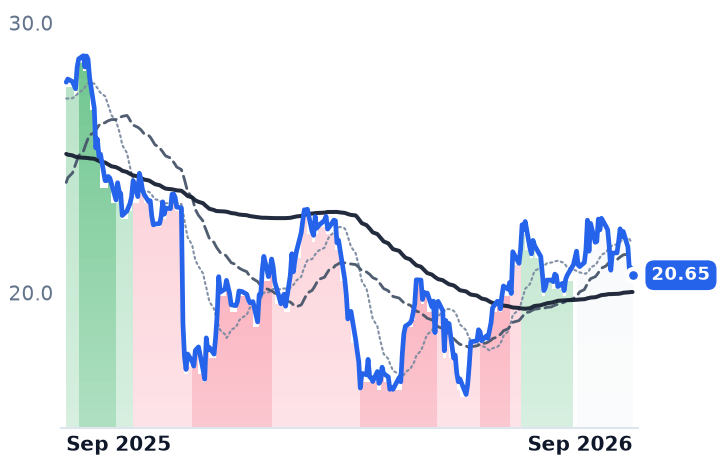
PG | The Procter & Gamble | Beauty & Personal Care | 🔴 Cont. Bear | +0.1% | −5.7% |
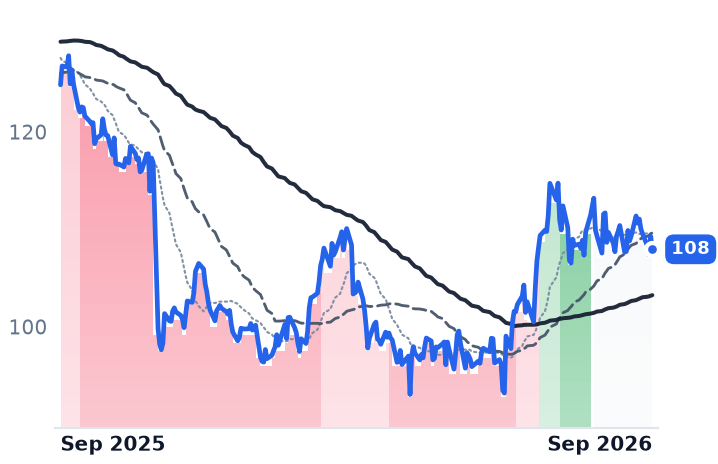
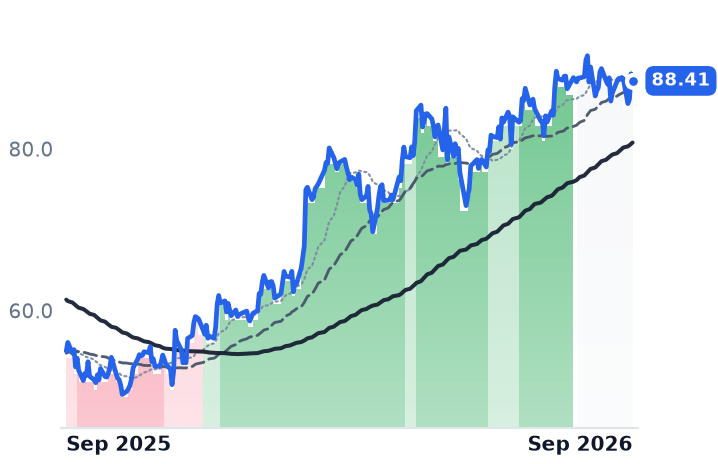
KMB | Kimberly-Clark | Tissue & Absorbent Products | 🔴 Cont. Bear | −3.3% | −13.5% |
CL | Colgate-Palmolive | Oral & Specialty Health | 🌱 Emerging Bull | −3.4% | +9.7% |
REYN | Reynolds Consumer Products | Consumer Packaging & Foodservice | 🟢 Cont. Bull | −18.0% | −4.6% |
ENR | Energizer | Specialty Power & Equipment | 🔴 Cont. Bear | −9.0% | −25.7% |
SPB | Spectrum Brands | Diversified Consumer | 🟢 Cont. Bull | −3.4% | +60.7% |
EPC | Edgewell Personal Care | Personal Care & Grooming | 🌱 Emerging Bull | −3.3% | +22.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLX | $11.4B | 19.6x | 16.2x | 1.7x | 1.5x | 4.0x | 3.5x | 18.2x | 3.6% |
CHD | $23.4B | 31.6x | 26.1x | 3.8x | 3.7x | 8.2x | 8.2x | 21.0x | 4.8% |
PG | $329.7B | 20.5x | 20.5x | 3.8x | 3.8x | 7.6x | 7.5x | 15.2x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KMB | $31.8B | 15.0x | 12.7x | 1.9x | 1.9x | 5.4x | 5.3x | 12.5x | 8.1% |
CL | $70.5B | 33.9x | 23.2x | 3.4x | 3.3x | 5.6x | 5.5x | 19.7x | 5.3% |
REYN | $4.5B | 13.5x | 13.2x | 1.2x | 1.2x | 4.8x | 4.8x | 9.3x | 7.3% |
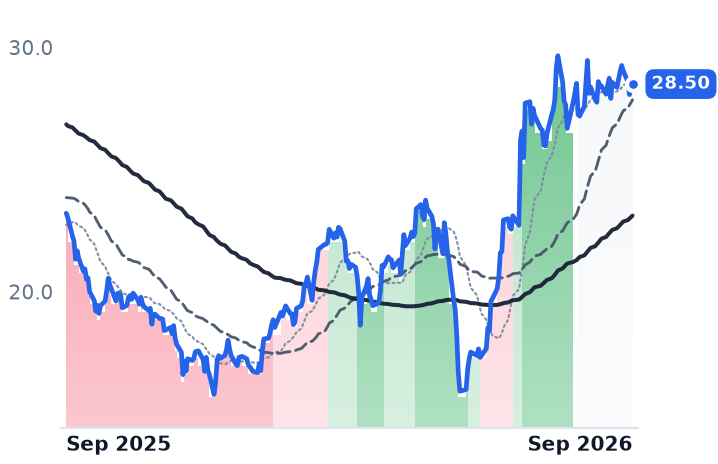
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENR | $1.2B | 5.9x | 4.8x | 0.4x | 0.4x | 0.9x | 0.9x | 7.3x | 13.8% |
SPB | $1.8B | 14.1x | 14.6x | 0.6x | 0.6x | 1.7x | 1.7x | 10.0x | 16.2% |
EPC | $734.1M | n/m | 8.4x | 0.3x | 0.4x | 0.8x | 0.9x | 12.9x | 6.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLX | Revenue | −5.1% | +14.2% | +2.4% |
| EPS | −21.6% | +5.2% | +8.0% | |
CHD | Revenue | +0.6% | +4.2% | +4.0% |
| EPS | +8.1% | +7.1% | +7.3% | |
PG | Revenue | +3.4% | +2.8% | +3.5% |
| EPS | +1.6% | +2.6% | +6.3% | |
KMB | Revenue | +2.6% | +2.5% | +5.7% |
| EPS | +0.8% | +0.6% | +7.3% | |
CL | Revenue | +5.9% | +3.3% | +3.6% |
| EPS | +4.1% | +5.4% | +7.5% | |
REYN | Revenue | +1.3% | +1.8% | +3.1% |
| EPS | −2.0% | +3.7% | +7.7% | |
ENR | Revenue | +2.1% | +1.1% | +1.2% |
| EPS | −2.3% | +4.2% | +7.0% | |
SPB | Revenue | +1.4% | +1.5% | +1.1% |
| EPS | +35.7% | +3.4% | +13.6% | |
EPC | Revenue | −9.9% | +1.6% | +1.1% |
| EPS | −28.6% | +8.4% | +4.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On July 31, Church & Dwight — which sells Arm & Hammer laundry detergent and cat litter, Xtra, Trojan and a mouthwash line that has become its fastest share gainer — raised its full-year organic sales outlook for the second time this year. Three days later, Clorox told investors that inflation in its new fiscal year would exceed $200m, more than double the $75m-to-$100m it normally absorbs, on an assumption that Brent crude averages $90 a barrel.
A branded cleaning company's sales line is only ever units times price. Since 2022 the industry has grown on the price half, surrendering volume to store brands in exactly the categories where the brand premium is thinnest. These two statements, days apart, say the halves have now separated by company: one of these firms is growing on units with pricing near zero, and the other is heading back to the list-price lever with a value-seeking shopper in front of it.
The units showed up at Church & Dwight
Organic sales rose 5.0% in the March quarter on volume of 5.3% — with price and mix subtracting 0.3 points — and 5.8% in the June quarter on volume of 4.3% and price/mix of 1.5%. Set that against full-year 2025, when organic growth was 0.7%.
The mechanism is distribution, not shelf inflation: management put total distribution point growth at roughly 11-12% against 5-6% for the industry. "THERABREATH achieved another quarter of record share gains, jumping 4.5 points to 25.3% share," chief executive Richard Dierker told investors on July 31 — a brand sitting at 14% household penetration in a category penetrated at 65%. Arm & Hammer laundry held share while cutting promotional spend by three-tenths of a point as Henkel's went up eleven.
The margin bridge is the tell. Adjusted gross margin rose 40 basis points to 45.4%, built from 180 points of volume and mix, 150 of productivity and 110 from higher-margin acquisitions, against 400 points of inflation, tariff and transport cost. "We are raising our full year organic sales outlook to approximately 4% to 5%, up from the prior outlook of 3% to 4%," finance chief Lee McChesney said on the same call. Reported sales barely move — consensus has 2026 revenue up 0.6% — because the gummy-vitamin brands were sold at the end of 2025 and the Flawless and Spinbrush lines exited.
Clorox's recovery is arithmetic
Fiscal 2026 revenue fell 5.4% to $6.72bn, gross margin contracted 290 basis points to 42.3%, and diluted earnings per share fell to $4.81 from $6.52. June-quarter organic sales fell 13%, of which about 13.5 points was lapping shipments pulled forward by the enterprise-software transition — roughly two weeks of retailer inventory that cost some 7.5 points of full-year sales and about $0.90 of earnings.
That distortion is genuinely ending, which is why fiscal 2027 organic sales are guided to 3.5-4.5%. But more than 3.5 points of that is the lap itself, and roughly 9.5 points of the 13-14% reported growth is the $2.25bn GOJO acquisition, maker of Purell, closed April 1. Underlying units are near zero. U.S. consumption returned to flat in the fourth quarter with full-year share off a tenth of a point, though Home Care logged an eighth straight quarter of share gains. Gross margin is guided flat at about 42%, and the response to the cost wave is productivity plus targeted pricing, starting with an announced increase on Glad trash bags. "We expect the operating environment to remain challenging, with continued cost volatility and a value-seeking consumer," chief executive Linda Rendle said of the year ahead.
What the market is paying
Clorox shares are down 22% over six months and change hands at 16.2 times forward earnings against 19.6 times trailing; the post-results rally to $107.90 on August 19 had fully unwound by early September, with a "Reduce" consensus and an average target near $102. Church & Dwight, on 26.1 times forward against 31.6 trailing, is also down over six months. The shelf is heavy generally — Reynolds Consumer Products fell 18% in a month, Kimberly-Clark 3% — but the dispersion inside it is a year old: Clorox is off 21% over twelve months, Church & Dwight up 6%.
So the cheap name has no units and the name with the units is not being paid for them. Clorox's fiscal 2027 line earns credit for the lap and the acquisition, and nothing yet for volume; going back to price with $200m of cost to recover is the same move that handed share to store brands the first time, and Circana puts private-label unit share at a record 23.8% even as its growth normalizes. Church & Dwight's cost headwind for the year is roughly $30m at the same oil price — an order of magnitude smaller — and its price/mix contribution is small enough that its growth does not depend on a shopper accepting a higher shelf tag.
The next test is narrow and dated: Glad's price increase goes onto a shelf where Clorox has just gotten consumption back to flat. If units hold through it, the pricing lever still works. If they do not, fiscal 2027's guided growth is the last of the arithmetic.