

BWXT Raised All Four 2026 Guidance Lines; Cameco Scrapped Its Westinghouse Growth Outlook
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two nuclear names that were re-rated as data-center power plays book almost none of that demand, and the past six months has been the market taking the premium back out. What it hit on the way is not the same at both.
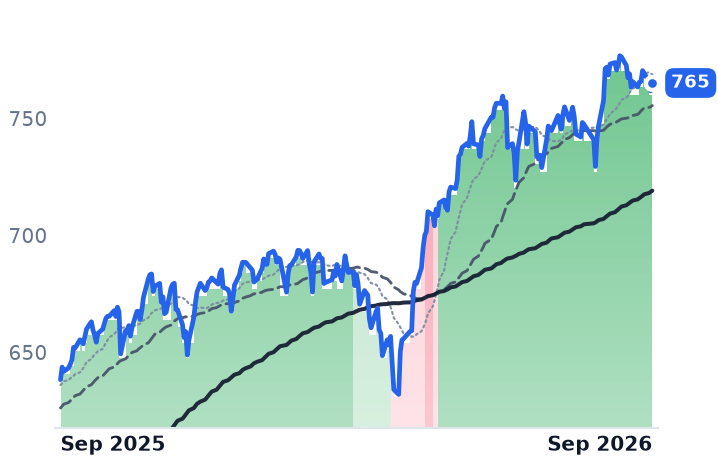
BWX Technologies grew June-quarter revenue 18% to $901.6m, carried backlog of $8.4bn on a trailing book-to-bill of 1.7x, and lifted revenue, earnings, cash flow and margin-adjusted profit guidance on August 3 — yet the shares are 24.4% below their March level and the forward earnings multiple has fallen to 32.8x from roughly 47x in May. The honest complaint against it is margin: gross margin fell to 22.4% from 25.1%.
Cameco is the opposite case. Reported net income fell 92% to $25.2m, but volumes were deliberately withheld and realized prices rose; earnings fell faster than the share price, so the stock is dearer after the drawdown than before it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −9.7% | −3.0% |
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +3.5% | +25.1% |
| Compared against · context, not the story | |||||
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | +4.3% | +12.3% |
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −9.4% | −14.9% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.8% | +19.9% |
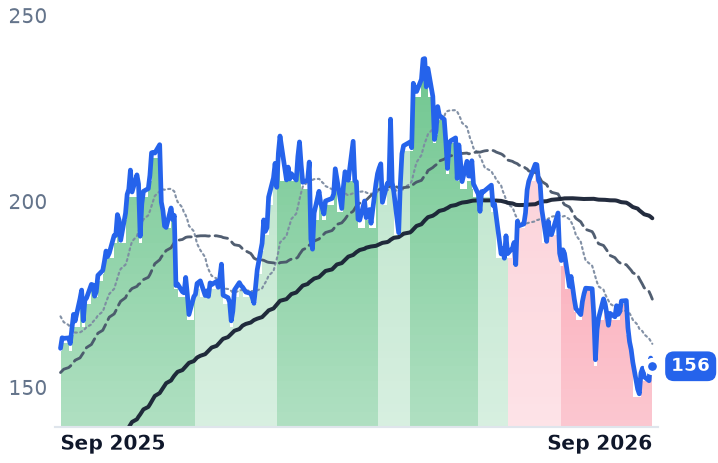
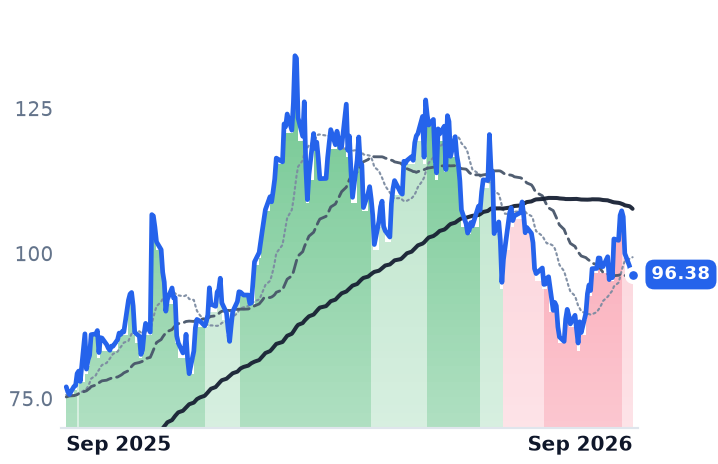
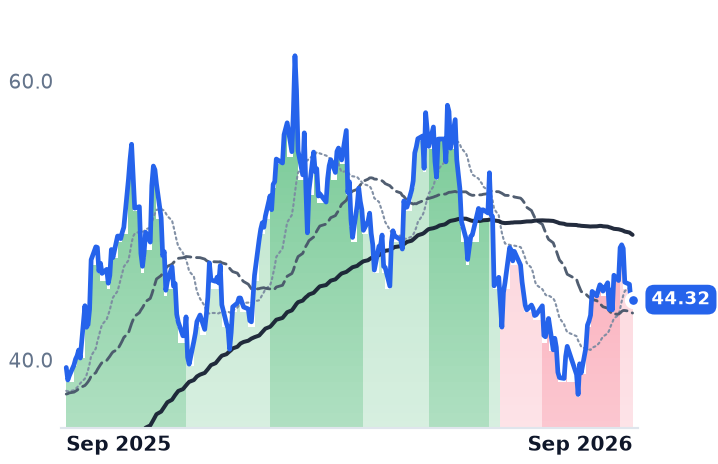
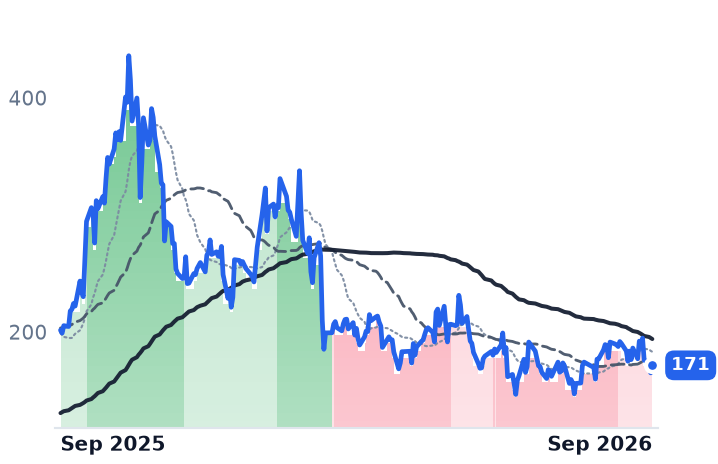
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $14.3B | 40.1x | 32.8x | 4.1x | 3.7x | 18.4x | 17.0x | 28.3x | 2.2% |
CCJ | $42.0B | 163.2x | 62.6x | 16.7x | 11.8x | 60.7x | 42.9x | 67.3x | 0.9% |
URA | $3.9B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $3.2B | 67.1x | 68.4x | 6.7x | 6.8x | 28.9x | 29.2x | 34.4x | -7.0% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.8% | +7.1% |
| EPS | +24.1% | +11.4% | +11.6% | |
CCJ | Revenue | +3.6% | +10.9% | +7.7% |
| EPS | +7.3% | +69.4% | +25.2% | |
LEU | Revenue | +4.8% | −0.2% | −9.4% |
| EPS | −45.1% | +17.7% | −15.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies, the sole-source supplier of nuclear reactors and fuel to the US Navy's propulsion program, ended June with backlog of $8.4bn, up 40% from a year earlier, its quarterly filing shows. On August 3 it raised its full-year revenue, adjusted profit, earnings and free cash flow guidance. The shares have fallen 24.4% since early March.
BWXT and Cameco, the Saskatchewan uranium miner that owns 49% of reactor builder Westinghouse, were both re-rated over the past two years as ways to own electricity demand from artificial-intelligence data centers. Neither books much of it. BWXT earns on multi-year Navy and Department of Energy contracts recognized as work is performed; Cameco sells uranium out of a long-term contract book with floors and ceilings struck years ago, and takes Westinghouse income on project milestones. What the market has removed since March is a demand premium that was never in either income statement. What it hit underneath differs by name.
At BWXT, the growth is real and the margin is not
June-quarter revenue rose 18% to $901.6m. Two-thirds of that — $601.3m — was Government Operations, which grew 2% at a 17.6% segment margin, while Commercial Operations grew 72% to $302.5m at 8.0%, the company reported. The commercial jump came from nuclear components, field services, fuel handling, medical isotopes and the Kinectrics acquisition; advanced nuclear volumes inside the government segment were lower. There is no small-modular-reactor revenue line doing the work.
The bears have one real number: GAAP operating income fell 12.2% to $89.9m on the 18% revenue gain, with gross margin down to 22.4% from 25.1% as BWXT builds capacity. On the August 3 call it cut its commercial margin guide to about 13% from about 14% and pushed meaningful recovery to 2027. Management also said it expects "at least one new build nuclear equipment order by year-end" — which means none had been booked. Its Army microreactor selection for Fort Campbell targets the early 2030s, and it agreed on July 31 to sell its medical business to Nordic Capital in a deal valued at up to $800m.
At Cameco, the drawdown made the stock dearer
Cameco's June-quarter revenue fell 7.2% to $814.1m and net income fell 92% to $25.2m. The cause is not price. Sales volumes fell 18% on "lower planned 2026 sales delivery volumes, reflecting contracting discipline," the company said, while the Canadian-dollar average realized uranium price rose 15% and Cameco raised its realized-price and consolidated revenue outlook. Delivery commitments still average about 28 million pounds a year through 2030, and production guidance of 19.5m to 21.5m pounds was left unchanged.
The damage sits at Westinghouse. Cameco's share of its adjusted profit fell to $163m from $352m, the prior year having carried roughly US$170m from the Czech Dukovany milestone, and the company eliminated its five-year Westinghouse growth outlook entirely, guiding 2026 to US$370-430m. Westinghouse has since confidentially filed for an initial public offering.
The split
The two did not fall together. BWXT is down 10.4% over thirty days and its 50-day average has been below its 200-day since early June; Cameco rose 7.4% over the same stretch, helped by an August 21 jump on the Westinghouse filing and a raised price outlook, and its own trend has begun to mend.
So the verdict divides. BWXT's de-rating carried past the premium and into the contracted business: 32.8x forward earnings against roughly 47x in May, with backlog and book-to-bill still rising and free cash flow guided to $345-360m. Cameco's did not de-rate at all — at 62.6x forward against about 56x in May, earnings fell faster than the shares, and consensus does not expect the step-change until 2027.
Both now depend on the same unbooked thing: a large-scale AP1000 order cycle. BWXT has told investors one equipment order should land before the year is out. Cameco has stopped forecasting Westinghouse five years out and is letting an IPO price it instead.