

Service and Finance Carry Lithia, Penske and AutoNation as New-Vehicle Gross Fell 13.5%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Selling vehicles is no longer what pays the biggest franchised car dealers, and their reported profits show it: gross profit and operating income fell year over year at all three of Lithia, Penske and AutoNation in the June quarter, while earnings per share rose.
At the average US dealership, fixed operations — parts, service, warranty and collision — produced 52.8% of all gross profit in the second quarter, up from 50.1% a year earlier, and finance-and-insurance income per vehicle hit a record $1,769. Lithia's after-sales margin reached 59.2%; AutoNation's after-sales gross was a record $607m; Penske's same-store service gross grew 5.7%.
The composition of dealer profit is genuinely improving. The total is not, and buybacks are doing the rest. Penske's share price answers to something else entirely — a $210 take-private proposal from its own controlling owners.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
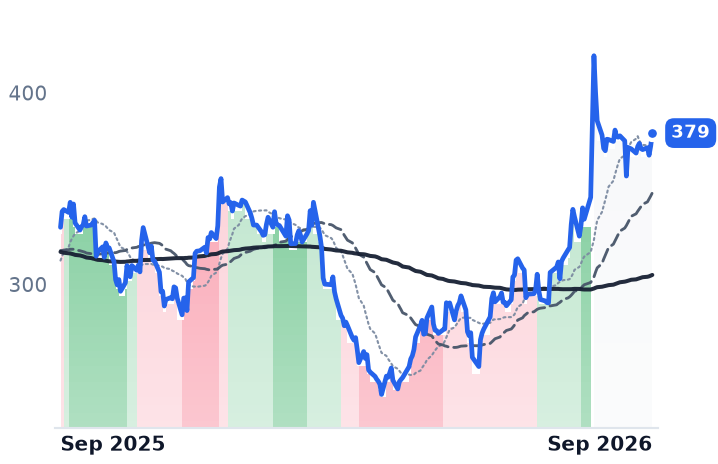
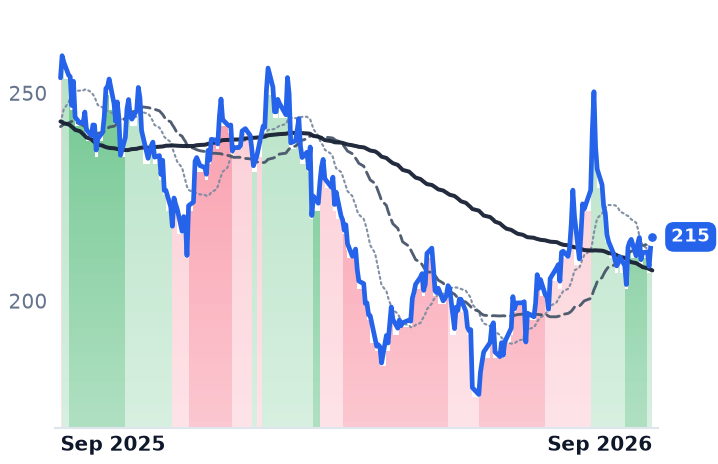
LAD | Lithia Motors | Traditional Dealership Groups | 🌱 Emerging Bull | +2.2% | +14.9% |
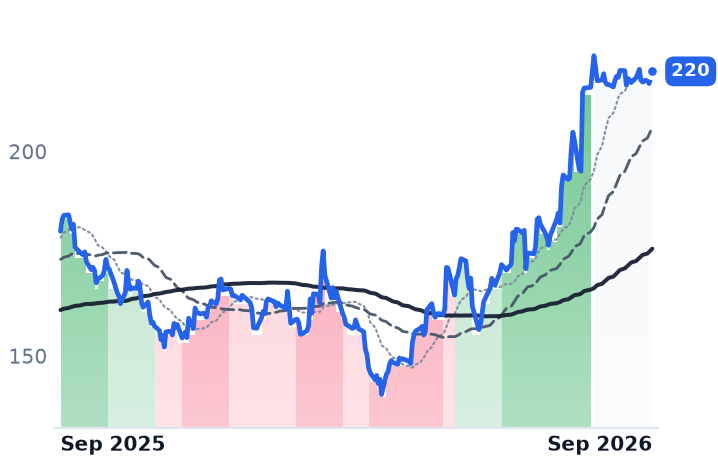
PAG | Penske Automotive | Traditional Dealership Groups | 🌱 Emerging Bull | +0.3% | +21.7% |
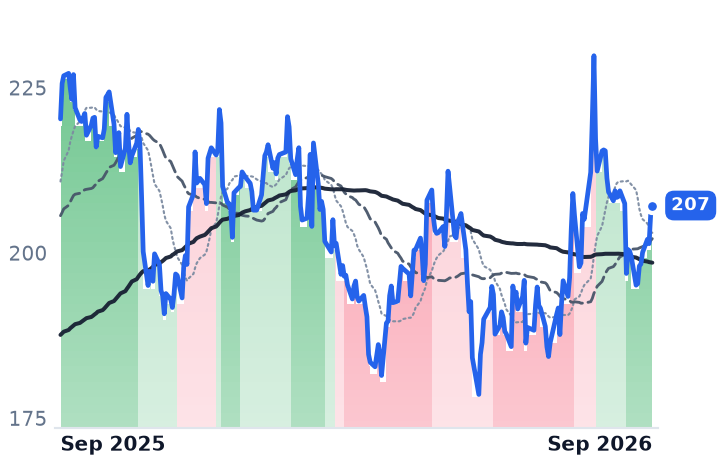
AN | AutoNation | Traditional Dealership Groups | 🟢 Cont. Bull | −3.9% | −6.0% |
| Compared against · context, not the story | |||||
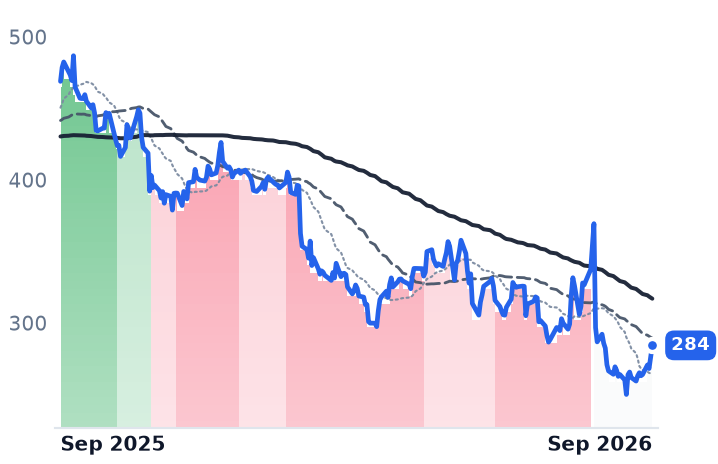
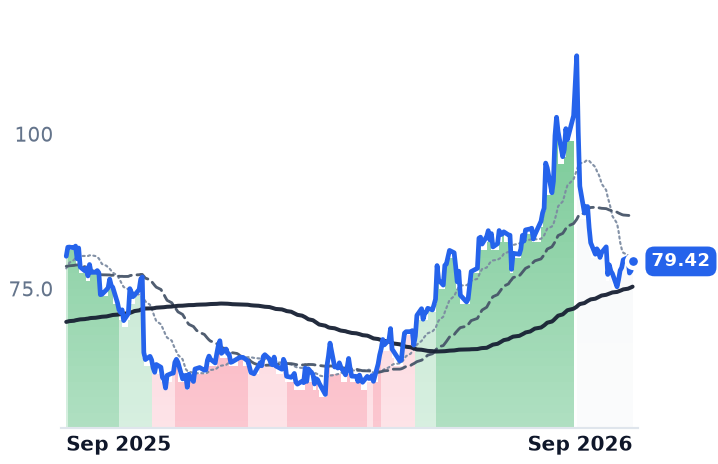
GPI | Group 1 Automotive | Traditional Dealership Groups | 🔴 Cont. Bear | −0.5% | −39.4% |
ABG | Asbury Automotive | Traditional Dealership Groups | 🌱 Emerging Bull | −3.3% | −15.1% |
SAH | Sonic Automotive | Traditional Dealership Groups | 🌱 Emerging Bull | −10.0% | −1.0% |
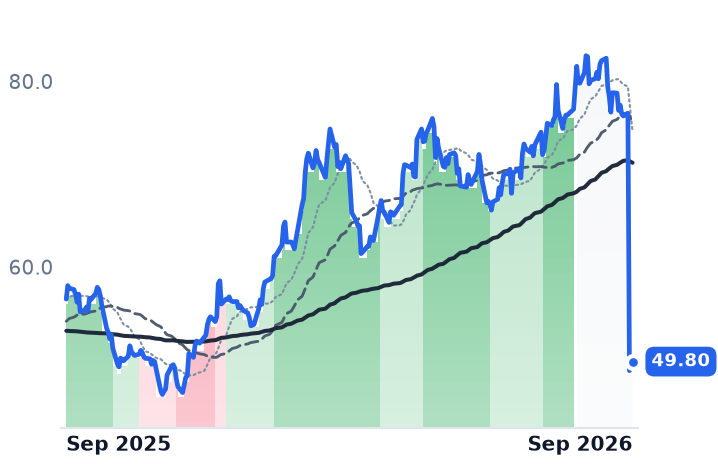
RUSHA | Rush Enterprises | Commercial Truck Dealerships | 🟢 Cont. Bull | −39.8% | −11.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LAD | $8.3B | 12.5x | 10.5x | 0.2x | 0.2x | 2.0x | 2.0x | 17.4x | -6.1% |
PAG | $14.4B | 16.2x | 16.1x | 0.4x | 0.4x | 2.7x | 2.7x | 13.7x | 4.1% |
AN | $6.9B | 9.4x | 9.5x | 0.3x | 0.2x | 1.4x | 1.4x | 11.1x | 0.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GPI | $3.7B | 11.5x | 7.4x | 0.2x | 0.2x | 1.1x | 1.1x | 8.6x | 7.5% |
ABG | $3.3B | 8.3x | 7.0x | 0.2x | 0.2x | 1.1x | 1.1x | 8.9x | 18.0% |
SAH | $2.5B | 22.8x | 10.9x | 0.2x | 0.2x | 1.1x | 1.1x | 13.4x | 10.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RUSHA | $5.7B | 14.5x | 19.9x | 0.8x | 0.7x | 4.2x | 3.9x | 13.0x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LAD | Revenue | +1.8% | +3.6% | +5.0% |
| EPS | +2.6% | +16.7% | +12.2% | |
PAG | Revenue | +6.7% | +2.5% | +2.2% |
| EPS | +1.0% | +6.6% | +7.0% | |
AN | Revenue | −0.4% | +3.2% | +2.1% |
| EPS | +9.1% | +13.5% | +13.9% | |
GPI | Revenue | +0.7% | +3.3% | +4.9% |
| EPS | +2.1% | +12.5% | +10.2% | |
ABG | Revenue | −0.6% | +4.5% | +7.4% |
| EPS | −8.2% | +14.8% | +8.7% | |
SAH | Revenue | +2.5% | +4.3% | +4.9% |
| EPS | +3.0% | +9.4% | +4.5% | |
RUSHA | Revenue | +5.2% | +10.5% | +5.5% |
| EPS | +18.2% | +23.5% | +21.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Franchised car dealers spent the June quarter making less money on every vehicle they sold, and their most profitable department did not sell one. Gross profit per new vehicle retailed at the average US franchised dealership fell 13.5% year over year to $1,840, and used-vehicle gross fell 10.0% to $1,409, according to the Presidio-NCM dealership benchmark. Over the same three months fixed operations — parts, service, warranty and collision work — grew gross profit 5.2% and passed half the store's total, at 52.8% of all dealership gross profit against 50.1% a year earlier.
That crossover is the business case at Lithia, Penske and AutoNation, and it is not yet enough: the average dealership's pretax profit still fell 11.8%. The annuity lines are cushioning vehicle-margin normalization rather than replacing it, and at the three largest listed groups the gap between shrinking gross profit and rising earnings per share is being closed by share count.
The service drive
Lithia Motors, which runs US and UK stores under the Lithia and Driveway brands plus its own lender, reported record second-quarter revenue of $9.79bn — but same-store revenue fell 1.6% and same-store gross profit 2.7%. After-sales gross rose 3.1% with margin up 120 basis points to 59.2%, helped by longer manufacturer warranties, and now accounts for 42% of company gross profit at lower cost to serve. "The quality of these earnings is what really stands out to me. New vehicle margins continue to be stable. Used vehicle profitability strengthened considerably," chief executive Bryan DeBoer told investors on July 29. Used gross per unit reached $2,019, up $339 sequentially on deliberately lower volume.
AutoNation, the Sunbelt-weighted retailer with 339 franchises across 247 stores, posted record after-sales gross of $607m, with customer-pay revenue up 7% and wholesale parts up 16% through a centralized supply chain management says is taking commercial parts share from the independent aftermarket. New-vehicle gross held at $2,381 a unit for a fourth consecutive quarter even as units fell 4%. Revenue, gross profit and operating income all fell — the last by 4.3%.
Penske Automotive, which pairs premium US and international franchises with 37 commercial-truck dealerships, grew same-store service and parts gross profit $27.1m, or 5.7%, with margin widening to 59.0% from 58.4% — the strongest fixed-operations growth of the three. Its revenue rose 6.0% to $8.51bn; operating income fell 7.6%, and selling costs ran 71.8% of gross profit against Lithia's 68.6% and AutoNation's 68.2%.
The finance book, and the floorplan surprise
The second annuity is lending. Lithia's Driveway Finance produced $37m of income, up more than 70%, on a book above $5bn with an average credit score of 748 and delinquencies improving. AutoNation Finance's portfolio grew 52% to $2.67bn and earned $11m against $2m a year earlier. Neither captive is deteriorating.
The assumed relief from falling short rates is more selective. AutoNation's floorplan interest eased to $43.7m from $45.3m and Penske's fell about $5m. Lithia's rose 26.7% to $69.7m after it moved used-vehicle borrowing onto floorplan facilities — a financing choice that swamps the rate cut.
What the shares are paying for
Demand is the constraint nobody has solved. The average new-vehicle transaction price was $49,855 in July, up 1.9%, with incentives down to 6.4% of price from 7.3%; Cox Automotive expects annual sales stuck in a 15-16 million range against more than 17 million before the pandemic.
AutoNation is the cheapest of the three at 9.4x trailing and 9.5x forward earnings, below the 12.1x it commanded at the end of 2025, and it repurchased $457m of stock in the first half, cutting diluted shares 12%. Lithia, at 12.5x trailing against 10.3x at the end of last year, has re-rated after a 30% three-month run on same-store revenue that fell; its 17% share-count reduction, not unit demand, produced 9% adjusted earnings growth. Penske's 16.2x, against 11.2x at end-2025, is a takeover price: Penske Corporation and Mitsui, already holders of 72.6%, proposed $210 a share on July 22, a special committee retained Moelis and Paul, Weiss on August 10, and the shares sit above the bid.
So the earned part of the move is real and narrow: service, parts and captive lending are compounding, and cost ratios improved sequentially at both Lithia and AutoNation. What nothing in the reported numbers yet explains is a multiple paid for re-acceleration — consensus has Lithia's earnings up 16.7% in 2027 — while same-store revenue is still negative. Penske's price is a corporate event wearing a dealer's clothes.
The binding constraint on the line that now carries these companies is not customers. AutoNation grew technician headcount 2% while customer-pay revenue grew 7%; the earnings engine is bays and the people standing in them.