

Google Bought 396 Megawatts From Fervo, Which Sold $113,000 of Power Last Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The largest enhanced-geothermal contract ever signed went to a company whose entire June-quarter revenue was $113,000. Fervo Energy's binding book jumped roughly 60% to 1,054 megawatts on September 1; none of it is generating yet, and second-half capital spending is guided at $850-900m.
Ormat Technologies, the incumbent that actually generates, is the mirror image: total revenue grew 10.6% in the second quarter, but the contracted geothermal line grew 5.8% while merchant battery storage nearly tripled, and only 15 of the 155 megawatts it added this year were geothermal. Ormat's Electricity guidance was cut $5m on Caribbean commissioning delays even as full-year revenue guidance rose to $1.15-1.2bn.
Contracting is not the constraint for either company. Commissioning is.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
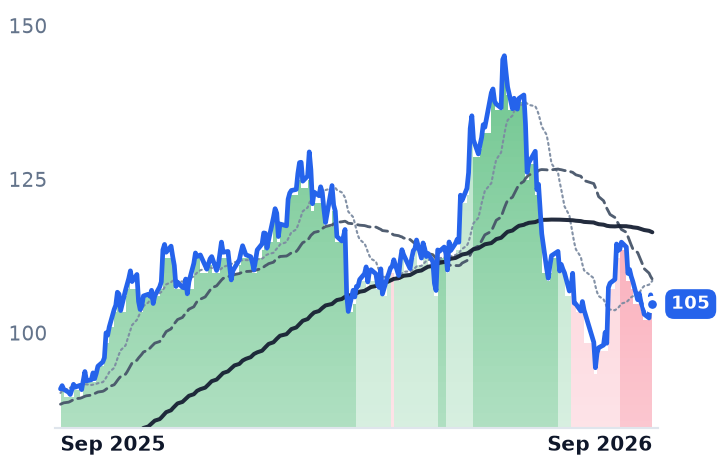
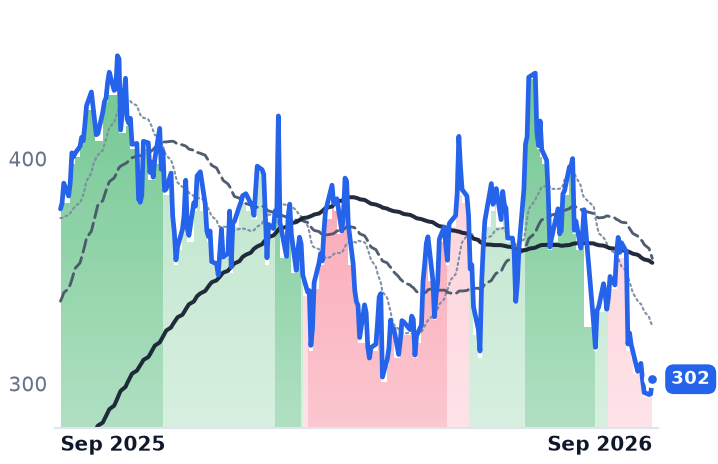
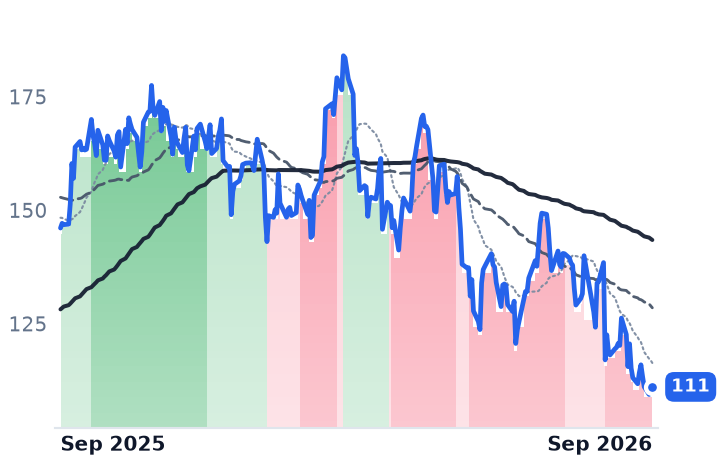
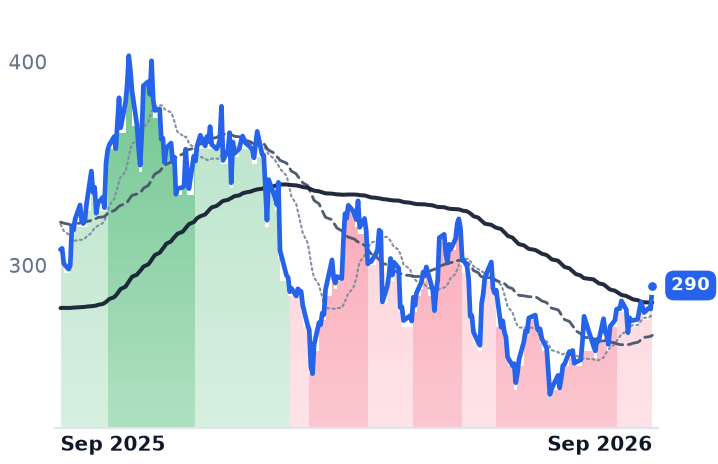
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | +4.6% | +15.2% |
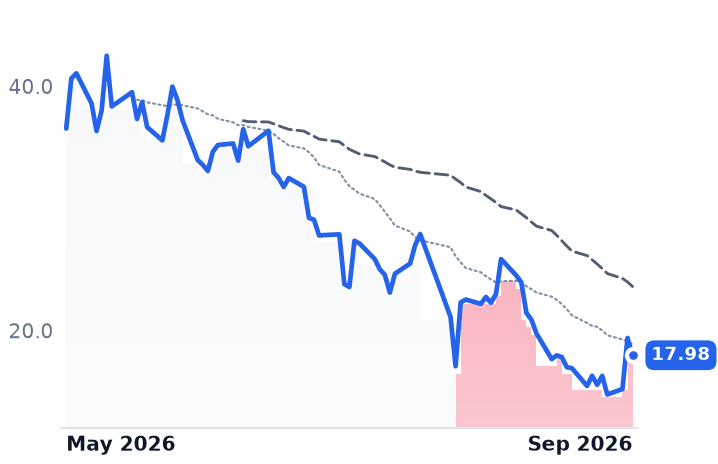
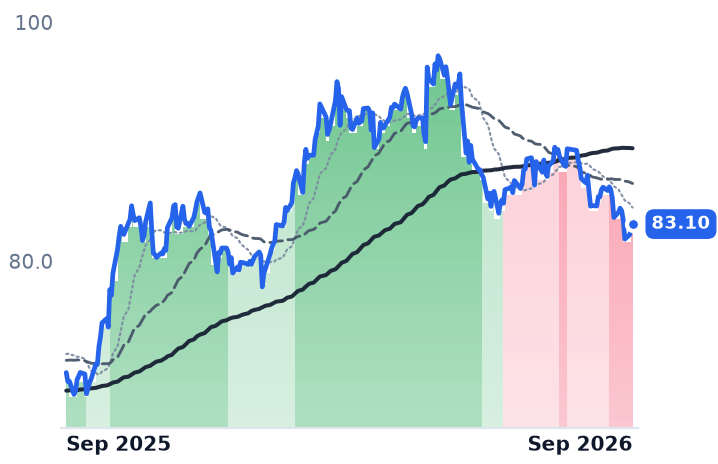
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −21.0% | −50.8% |
| Compared against · context, not the story | |||||
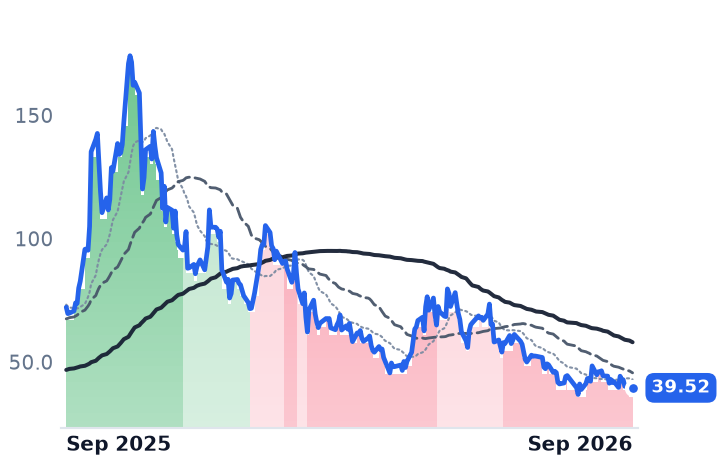
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −8.8% | −45.3% |
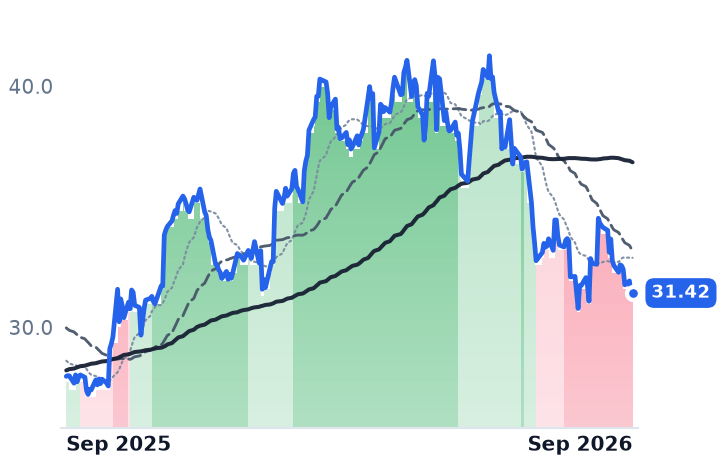
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −1.0% | +12.4% |
TLN | Talen Energy | Wholesale Power Producers | 🌱 Emerging Bull | −11.2% | −20.0% |
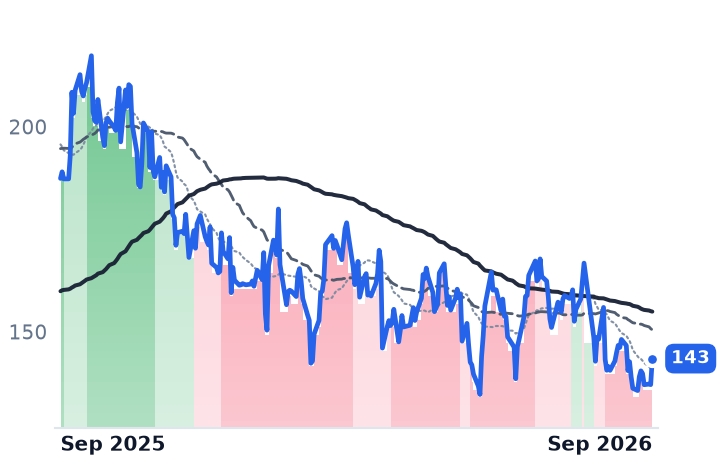
NRG | NRG Energy | Integrated Retail & Generation | ⚠️ Emerging Bear | −5.1% | −24.0% |
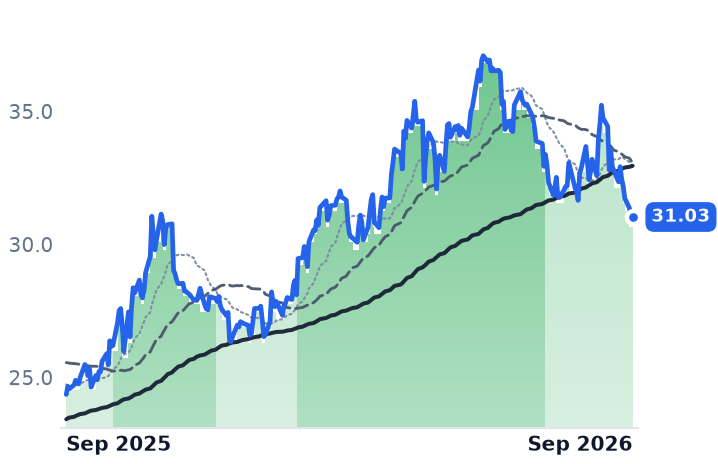
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | 🟢 Cont. Bull | −6.1% | +27.4% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +0.2% | −23.4% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | +8.5% | −5.7% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.7% | +17.6% |
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | +0.9% | +14.6% |
FRMI | Fermi | Emerging & Specialized Energy | 🔴 Cont. Bear | −24.4% | −85.3% |
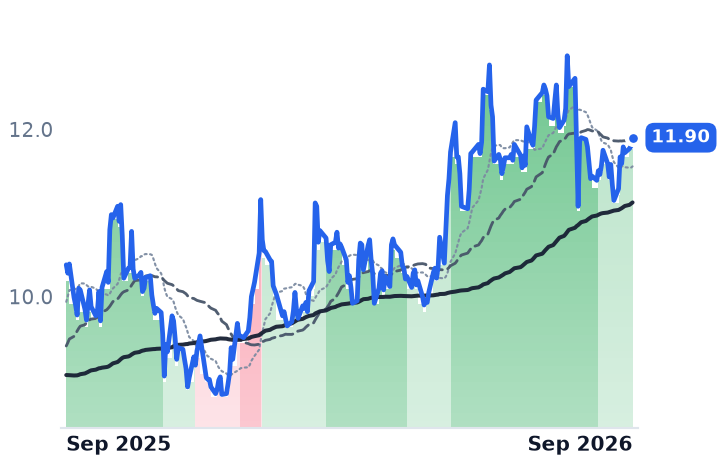
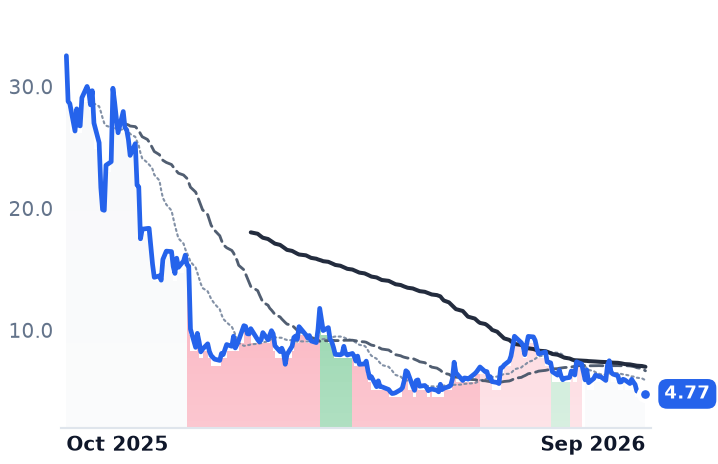
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORA | $6.4B | 50.3x | 40.8x | 5.4x | 5.5x | 19.4x | 19.5x | 21.5x | -4.1% |
FRVO | $5.2B | n/m | — | — | 890.6x | — | — | n/m | -8.6% |
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWEN | $6.7B | 42.6x | — | 4.2x | 4.0x | 8.0x | 7.6x | 14.6x | 10.1% |
TLN | $14.3B | n/m | 14.9x | 4.0x | 3.2x | 9.1x | 7.1x | 29.7x | 3.6% |
NRG | $23.9B | 29.6x | 12.7x | 0.6x | 0.7x | 4.0x | 4.0x | 11.2x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BEP | $10.0B | 71.2x | — | 1.6x | 1.5x | 6.5x | 6.1x | 9.9x | -47.1% |
VST | $47.2B | 23.4x | 16.3x | 3.0x | 2.1x | 22.8x | 16.2x | 10.3x | 2.9% |
CEG | $101.4B | 27.5x | 24.1x | 3.2x | 3.1x | 3.4x | 3.2x | 14.7x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $174.5B | 18.7x | 20.8x | 6.0x | 5.6x | 8.4x | 7.8x | 15.9x | -5.8% |
XIFR | $1.1B | 17.6x | 10.6x | 0.9x | 0.8x | 5.3x | 4.8x | 9.0x | -57.0% |
FRMI | $3.8B | n/m | — | n/m | 208.4x | — | — | n/m | -31.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORA | Revenue | +21.3% | +0.5% | +11.7% |
| EPS | +17.5% | −2.1% | +26.8% | |
FRVO | Revenue | +4096.8% | +1158.3% | +199.7% |
| EPS | −91.9% | −19.6% | −30.1% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% | |
CWEN | Revenue | +14.8% | +10.8% | +13.4% |
| EPS | −133.6% | −152.5% | +132.7% | |
TLN | Revenue | +85.7% | +15.6% | +5.1% |
| EPS | +256.0% | +51.3% | +20.9% | |
NRG | Revenue | +20.5% | +1.8% | +4.9% |
| EPS | +14.6% | +24.0% | +16.0% | |
BEP | Revenue | +3.8% | +9.0% | −3.4% |
| EPS | +14.0% | −11.7% | +9.4% | |
VST | Revenue | +16.7% | +9.3% | +4.7% |
| EPS | +80.0% | +18.7% | +18.0% | |
CEG | Revenue | +35.3% | +4.1% | +5.2% |
| EPS | +25.2% | +13.1% | +28.6% | |
NEE | Revenue | +10.4% | +9.9% | +8.6% |
| EPS | +9.0% | +9.1% | +8.3% | |
XIFR | Revenue | +0.1% | +6.2% | +2.2% |
| EPS | −830.7% | −10.8% | −79.3% | |
FRMI | Revenue | +14.5% | +2797.8% | +327.6% |
| EPS | +326.2% | −116.4% | +1983.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A contract signed years before the plant exists
Fervo Energy signed a 396-megawatt power purchase agreement with Google on September 1 for Cape Station, its enhanced-geothermal project in southwestern Utah. It is the largest such agreement on record, with power expected online in 2028 and an option that would take Google to nearly 1 gigawatt by June 2030. Fervo's binding contracted capacity rose about 60%, to 1,054 megawatts. It is the second deal between the two; Fervo's Project Red pilot in Nevada has fed Google's local data centers since 2023.
That pilot is also, at present, the whole revenue line. Fervo booked $113,000 in the June quarter against an operating loss of $28.7m. Geothermal is the only zero-carbon resource that runs around the clock regardless of weather, and there are exactly two US-listed pure-plays selling it — Fervo, a Houston driller applying shale horizontal-well technique to hot rock, and Ormat Technologies, which owns and operates 1,355 megawatts of commissioned geothermal, solar and recovered-energy plants and manufactures the binary turbines inside them. Both signed data-center offtake with Google inside seven months. Neither has a contracting problem. Both have a commissioning problem, and that is the entire distinction between a backlog and a business.
Fervo: the cost curve is real, the calendar is the risk
"This agreement reinforces that EGS is ready to power the next generation of computing infrastructure," chief executive Tim Latimer said on September 1. "This new PPA is part of our repeatable commercial model." The engineering supports him. Fervo's Sawtooth 7 well reached 19,500 feet and 460°F in 21 days, matching wells that were on average 35% shallower, and the company has cut per-foot drilling costs roughly 70% since 2022. Phase I of Cape Station costs about $7,000 per kilowatt; Phase II targets $5,500 on the wider, hotter Fervo 3.0 well design.
The calendar is where it bit. On its August 12 call Fervo gave first hard revenue guidance of $60-80m for 2027 — against a $7.2bn contracted backlog — blaming transmission curtailment caused by a grid operator adding a separate asset. Consensus has already marked 2027 to $72.9m, inside management's own range. Cape Station Phase I, 100 megawatts in three blocks, still targets first power in the fourth quarter of 2026. Liquidity is not the issue: $2.1bn of cash against $228.4m of debt, with first-half operating burn of only $43.8m. The spending is capital, guided at $850-900m for the second half.
Ormat: the growth came from batteries
Ormat's second quarter grew 10.6% to $258.8m with gross margin up 220 basis points to 26.5%, and full-year guidance rose to $1.15-1.2bn. Underneath, contracted geothermal Electricity revenue grew 5.8% to $169.3m, while merchant Energy Storage rose 195% on strong PJM pricing at a margin management expects to normalize toward 40-50%. Operating income fell 3.2% to $34.2m. Electricity guidance was cut about $5m to $710-725m on one-to-two-month commissioning delays at two Caribbean projects. Of 155 megawatts added year to date, 15 were geothermal — a 5-megawatt Cove Fort upgrade and the 10-megawatt Dominica plant. All 202 megawatts under construction are contract-backed, and roughly 190 megawatts of legacy contracts expiring 2031-2034 at a weighted-average $86 per megawatt-hour reprice into a market above $100.
Ormat carries $3.4bn of debt at a 3.9% average rate, 4.3 times adjusted earnings before interest, taxes, depreciation and amortization, with $449m of 2026 capital spending still to come. "We are speaking with different hyperscalers, data centers, and utilities about EGS projects," chief executive Doron Blachar told investors on August 5. Its own enhanced-geothermal answer — the Ormega100 turbine and a Desert Peak pilot with SLB — begins drilling in the fourth quarter.
What the prices have and have not settled
Ormat is 27.5% below its June 2 close of $144.48, a break dated to Bernstein's June 16 Underperform initiation, which argued it would lose the enhanced-geothermal race to Fervo by name. It is nonetheless up 15.1% over twelve months and 6.8% over the past thirty days. Fervo, which raised $1.89bn at $27 a share in May, trades a third below its offer price despite gaining 27.5% in the single September 1 session on 22.3m shares, six times normal volume; press accounts put that close at $19.75, up 28.41%. The wider listed power complex fell together over the summer against a 30-year Treasury yield at a 19-year high, but that backdrop does not explain a company rising while its band signals turned negative.
On valuation the two are barely comparable. Ormat fell from about 56 times forward earnings at its June peak to 40.8 times now, on an unchanged $2.57 consensus for 2026 — a de-rating that did rational work without making the shares cheap, since consensus has 2027 revenue growing 0.5% and earnings per share falling 2.1%. Fervo has no usable earnings or sales anchor; it trades at 1.90 times book with $2.1bn of net cash inside a $5.16bn market value, leaving roughly $2.9m of enterprise value per contracted megawatt. Policy sits on both sides of the ledger favorably: geothermal qualifies for the full federal investment or production credit if construction starts by 2033, a decade longer than solar and wind.
The verdict is symmetrical and uncomfortable. The demand premium in the geothermal story is real and is being written into contracts by the same buyer for both companies — but it has reached neither revenue line. Ormat's earned growth this year came from merchant batteries and an equipment delivery, not from the contracted megawatt-hours the thesis rests on; Fervo's contracted book is genuine and its drilling costs are genuinely falling, yet nothing in it converts to cash before a grid interconnection that a third party controls. The de-rating priced delay, and delay is exactly what both disclosed.
Ormat lays out a roadmap to 2.6-2.8 gigawatts at an investor day on September 8. Fervo's first commercial block is due to energize before the year ends. Until it does, the cleanest firm-power story on the market is still one where the megawatts exist on paper and the electricity does not.