

New Switchgear Plants Don't Open Until 2027; Powell's Backlog Hit a Record $2.4bn
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The bear case on switchgear makers is that the post-2021 shortage is ending and the pricing that came with it is about to normalize. Every dated fact says the relief arrives in 2027 at the earliest — and the shares have already been marked down as though it arrived this summer.
Powell Industries booked $934m of orders in the June quarter against $362m a year earlier, three times what it shipped, taking backlog to an all-time $2.4bn while gross margin widened to 30.6%. Hubbell doubled its 2026 sales-growth guidance to 16-18%. Medium-voltage switchgear still runs 52 to 80 weeks and power transformers about 128 weeks.
Powell's business explains none of its fall; Hubbell's does explain part of it, because the $3.0bn NSI deal added roughly $170m of annual interest and reported profit slipped 1.6% on a 15.3% revenue gain. The rest looks like a discount-rate problem, with the 30-year Treasury at 5.33%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
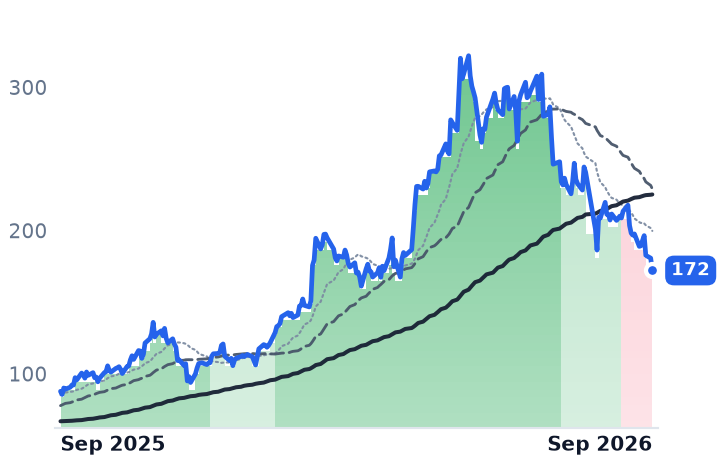
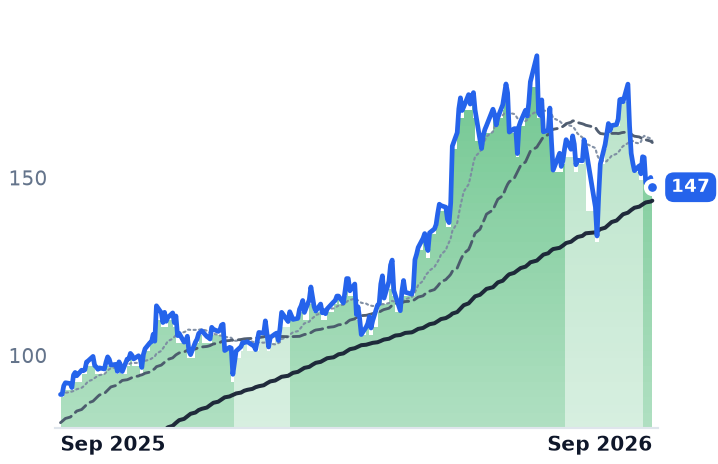
POWL | Powell Industries | Electrical Distribution & Switchgear | 🟢 Cont. Bull | −21.7% | +96.0% |
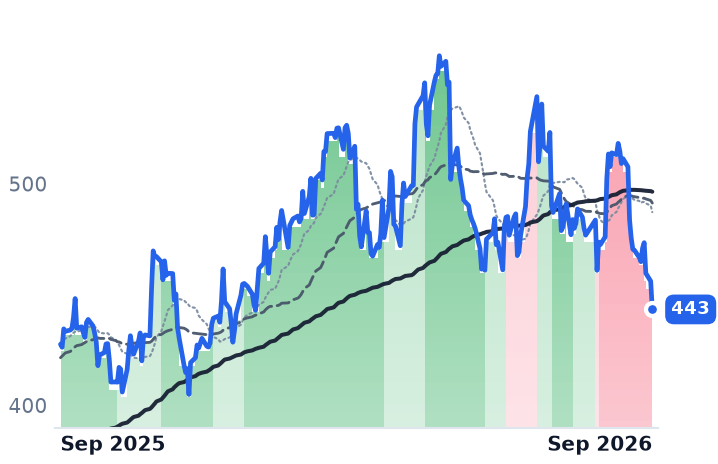
HUBB | Hubbell Incorporated | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | −6.9% | +3.7% |
| Compared against · context, not the story | |||||
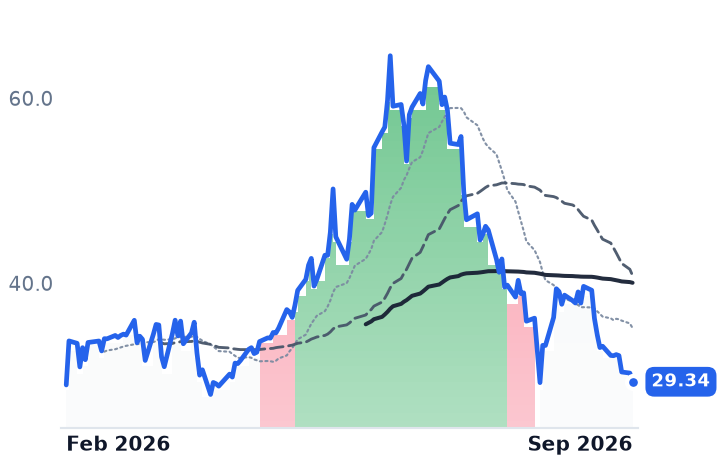
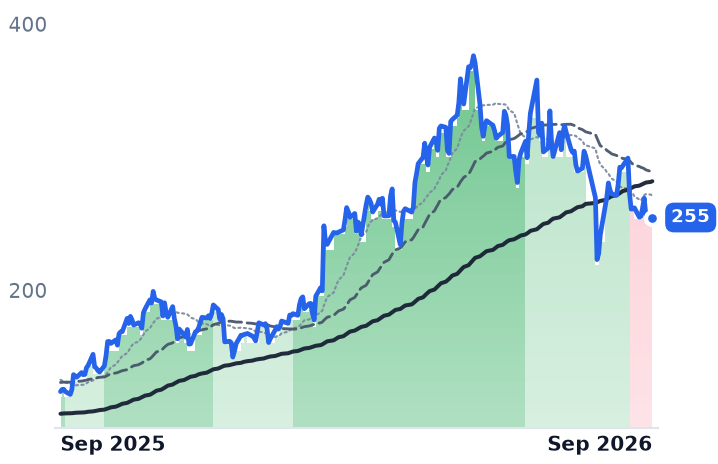
FPS | Forgent Power Solutions | Electrical Distribution & Switchgear | 🟢 Cont. Bull | −19.1% | +1.2% |
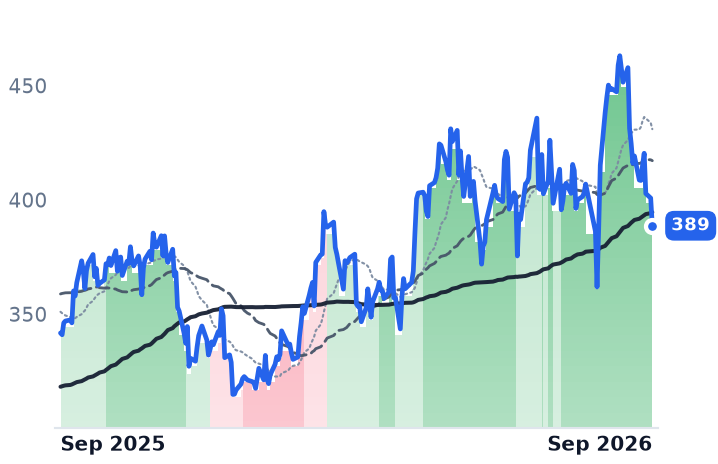
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | −11.3% | +13.7% |
NVT | nVent Electric | Data Center Power & Thermal | 🟢 Cont. Bull | −7.6% | +65.5% |
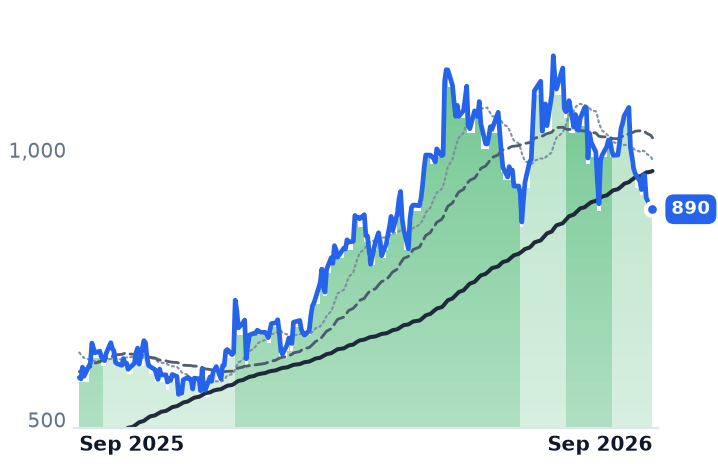
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | −3.2% | +105.6% |
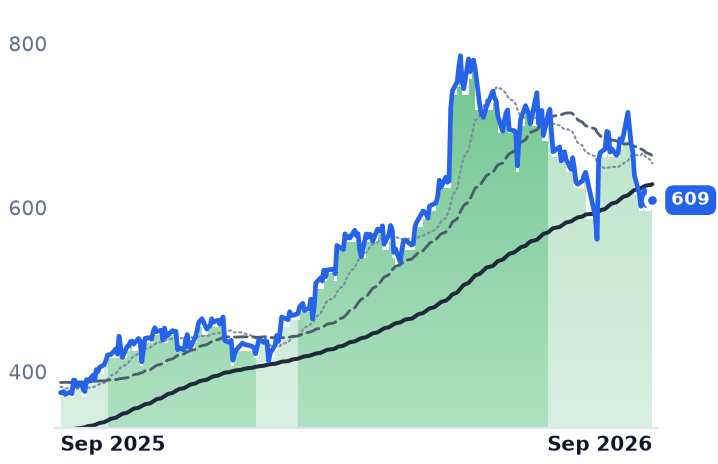
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | −11.6% | +53.9% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | −9.3% | +62.7% |
AZZ | AZZ | Metal Coatings & Finishing | 🟢 Cont. Bull | −9.5% | +20.8% |
MYRG | MYR | Electrical & Power Infrastructure | 🟢 Cont. Bull | −14.3% | +56.9% |
ABBNY | ABB | Electrical Equipment & Parts | 🟢 Cont. Bull | −3.1% | +47.7% |
ATKR | Atkore | Electrical Infrastructure Products | 🌱 Emerging Bull | +0.1% | +64.6% |
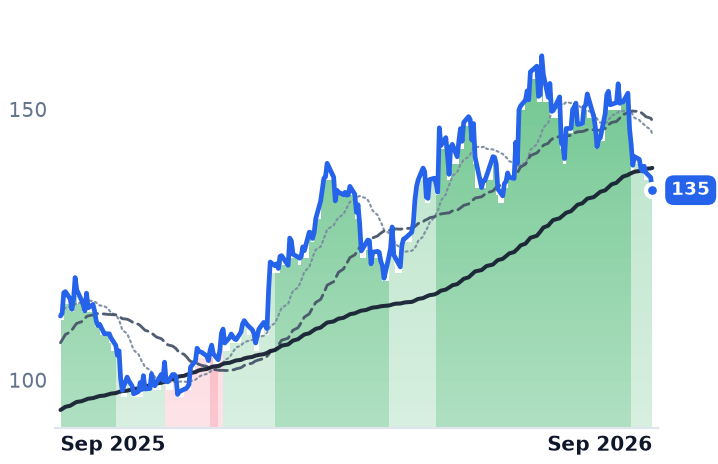
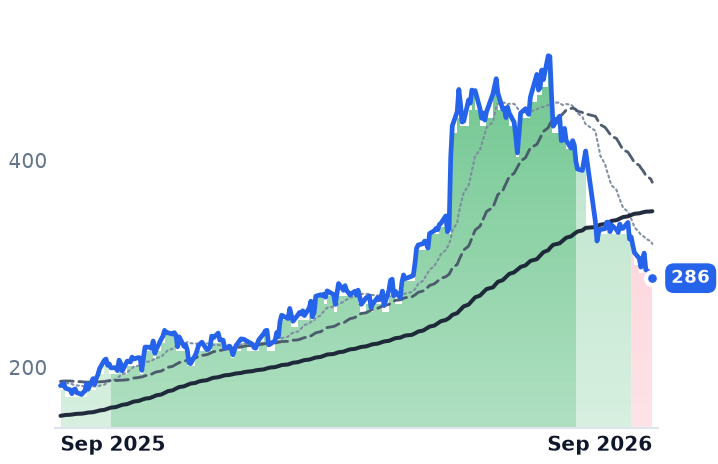
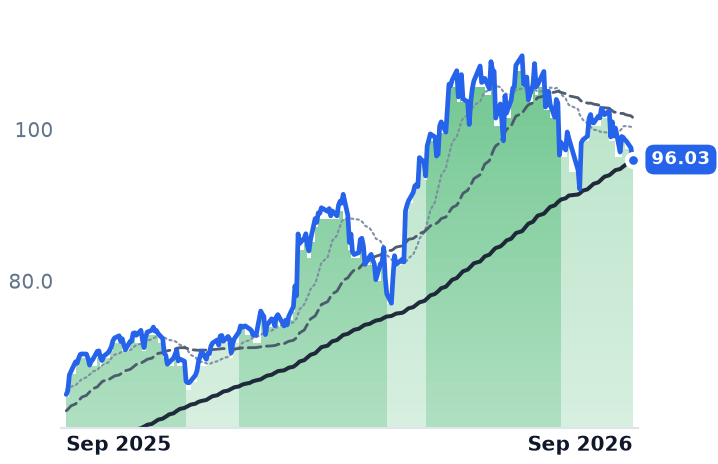
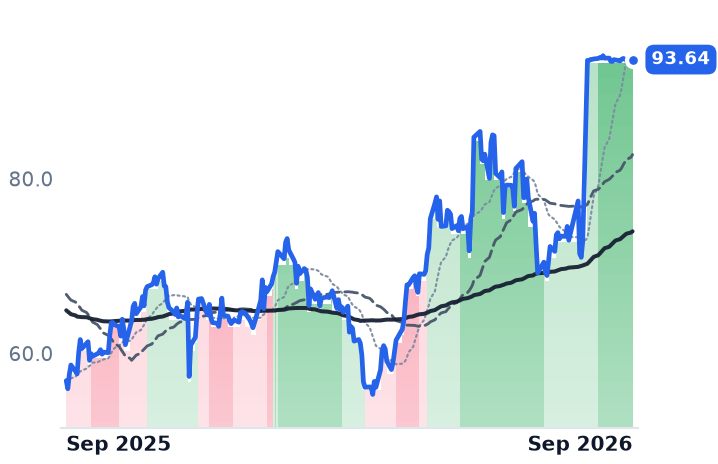
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $6.3B | 32.8x | 32.0x | 5.4x | 5.2x | 18.0x | 17.5x | 22.7x | 3.9% |
HUBB | $23.4B | 26.2x | 21.7x | 3.8x | 3.4x | 10.7x | 9.7x | 19.4x | 3.8% |
FPS | $7.6B | — | 26.9x | 6.4x | 3.7x | 20.5x | 12.0x | 62.3x | -1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $162.8B | 42.5x | 31.0x | 5.4x | 5.0x | 15.1x | 13.8x | 28.4x | 2.8% |
NVT | $24.6B | 41.2x | 29.9x | 5.1x | 4.5x | 13.8x | 12.3x | 25.8x | 2.4% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $242.9B | 25.9x | 29.7x | 5.9x | 5.2x | 29.0x | 26.0x | 27.0x | 5.1% |
PWR | $96.1B | 72.3x | 38.2x | 2.9x | 2.4x | 20.3x | 16.9x | 33.7x | 2.5% |
AZZ | $4.2B | 13.3x | 20.6x | 2.6x | 2.4x | 10.7x | 10.1x | 8.4x | 10.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MYRG | $4.8B | 29.2x | 25.5x | 1.2x | 1.1x | 9.7x | 8.9x | 16.2x | 4.0% |
ABBNY | $184.3B | 36.8x | 30.3x | 5.1x | 4.8x | 12.7x | 12.1x | 24.7x | 2.6% |
ATKR | $3.2B | n/m | 16.5x | 1.1x | 1.1x | 5.5x | 5.4x | n/m | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
HUBB | Revenue | +17.1% | +9.7% | +5.7% |
| EPS | +12.2% | +11.7% | +10.7% | |
FPS | Revenue | +57.5% | +46.8% | +39.7% |
| EPS | — | +60.3% | +84.0% | |
ETN | Revenue | +19.6% | +10.6% | +9.4% |
| EPS | +12.2% | +18.2% | +16.4% | |
NVT | Revenue | +41.5% | +19.4% | +14.7% |
| EPS | +52.7% | +27.3% | +19.8% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
GEV | Revenue | +23.9% | +14.8% | +15.0% |
| EPS | +321.7% | −19.5% | +40.7% | |
PWR | Revenue | +40.6% | +16.7% | +12.5% |
| EPS | +57.5% | +17.8% | +16.7% | |
AZZ | Revenue | +3.3% | +6.3% | +4.8% |
| EPS | +15.3% | +12.7% | +11.5% | |
MYRG | Revenue | +22.9% | +15.5% | +11.4% |
| EPS | +72.5% | +18.4% | +22.2% | |
ABBNY | Revenue | +13.1% | +11.7% | +10.2% |
| EPS | +31.6% | +9.2% | +14.6% | |
ATKR | Revenue | +5.0% | +4.7% | +6.6% |
| EPS | −13.4% | +11.5% | +13.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The shortage that made electrical switchgear a franchise business has not eased. Medium-voltage 15,000-volt gear still takes 52 to 80 weeks to deliver, stretching toward two and three years for data-center specifications, and standard power transformers average about 128 weeks, with substation units above 160. Copper, the largest bought-in input for switchgear and busbar, set an all-time high on COMEX at $6.77 a pound on August 7.
That matters because the supply response everyone points to is dated, and the dates are not 2026. Eaton is spending $340m to expand three-phase transformer output at Jonesville, South Carolina, with production and hiring beginning in 2027, and $30m on a 370,000-square-foot medium-voltage switchgear plant at Bellevue, Nebraska, starting in the first half of 2027. Schneider Electric has committed more than $700m through 2027. New factories take years to reach full output, so the wait times outlast the plans meant to fix them.
What the order books actually did
Powell Industries, the Houston maker of custom medium-voltage switchgear, circuit breakers and modular "E-House" substations for refineries, liquefied natural gas terminals, utilities and now data centers, booked record orders of $934m in the June quarter against $362m a year earlier — three times what it shipped. Backlog reached an all-time $2.4bn, roughly $967m higher than a year ago, with about $1.3bn convertible inside twelve months. Revenue grew 8.9% to $311.7m, the third consecutive quarter of acceleration, and gross margin widened to 30.6% from 28.4% two quarters earlier. The company holds $634m in cash and no debt.
The largest single award, a behind-the-meter data-center project worth more than $400m, will burn over "roughly two to two and a half years" across at least five North American sites, chief executive Brett Cope told investors on August 4, adding that future phases should be "copy jobs" of the first. On pricing, Cope said there is "some opportunity for price" in the market, with delivery speed carrying the value proposition in commercial work; finance chief Mike Metcalf credited mix, operating leverage and "pricing stability."
Hubbell, the Connecticut maker of utility distribution, transmission and substation hardware alongside wiring and lighting, raised 2026 sales-growth guidance to 16-18% from 8-11%. Utility Solutions ran a 1.2x book-to-bill; Electrical Solutions grew 18% organically with data-center revenue up about 65%. The company took roughly a point of price in April and half a point in July, targeting three to four points for the year. Chief executive Gerben Bakker said the quoting pipeline is running at about twice the volume of a couple of years ago.
Where the shares went instead
Over the thirty days to September 1, Powell fell 21.7% and Forgent Power Solutions — the Minnesota switchgear, transformer and power-distribution-unit maker that listed in February and grew March-quarter revenue 146% to $378.7m at a 31.1% gross margin — fell 19.2%. The diversified names fell about half as hard: Eaton 11.3%, GE Vernova 11.6%, Hubbell 6.9%. Powell is down 46.6% from its May 11 peak; Forgent has round-tripped to its listing price. The likelier reading is duration, with the 30-year Treasury yield reaching 5.33% in August, its highest in nearly two decades — a rate that bears hardest on companies whose value sits in backlog converting in 2028 and beyond. Cantor Fitzgerald cut its Powell target to $235 from $320 on August 14 while keeping a Neutral rating, reasoning that working through the existing backlog does not require the next plant.
The verdict
Powell's business explains none of its fall. Its trailing price/earnings ratio is 32.8x against 49.2x in early May, and 32.0x on this year's consensus of $5.38 — the same estimate that supported roughly 60x at the May high. What has not happened is an earnings cut. Cheapness here is relative to its own four-month-old anchor: Powell still trades at 18.0x gross profit against Hubbell's 10.7x, 68% higher.
Hubbell is the more honest half. Revenue accelerated to 15.3% growth, but gross margin fell 139 basis points year over year and reported net income slipped 1.6%, because the $3.0bn NSI acquisition carries about $170m of extra annual interest and takes leverage to 2.9x. That earns some of a 20.5% drawdown; a doubled sales guidance does not. The shares trade at 21.7x this year's consensus and 19.4x next year's $22.80, against 14.0x gross profit in early May.
The test the market has priced is scheduled, and it is not scheduled for this year. If Eaton's and Schneider's lines open on time, the 2027 order book is where pricing power gets audited — one reason Powell's own footprint expansion, more than 20% of capacity by the end of this fiscal year, is a bet placed against the same clock.