

Aon Is Borrowing All $17bn for USI and Has Suspended Buybacks to Cut Leverage
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Eight straight quarters of falling commercial insurance rates have not dented what the biggest brokers earn — and that is the surprise. Marsh's index shows global commercial rates down 6% in the June quarter, with property down 12%, yet Aon, Marsh and Willis Towers Watson each grew 5% organically and Gallagher 6%. Brown & Brown is the lone exception, at -0.7% excluding contingent commissions.
What repriced Aon was its own balance sheet. The USI purchase lifts pro-forma leverage to 4.3-4.5 times earnings before interest, tax, depreciation and amortization from 2.7 times today, on S&P's arithmetic, and repurchases are on hold until it comes back down. Gallagher, which paid 11.3 times for AssuredPartners against Aon's 14.5 times for USI, now trades at 20.0 times forward earnings, the richest of the five.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AON | Aon | Global Risk & Insurance Brokers | 🌱 Emerging Bull | −7.5% | −10.8% |
AJG | Arthur J. Gallagher | Global Risk & Insurance Brokers | 🌱 Emerging Bull | +6.7% | −11.9% |
| Compared against · context, not the story | |||||
WTW | Willis Towers Watson Public | Global Risk & Insurance Brokers | ⚠️ Emerging Bear | −1.1% | +4.7% |
BRO | Brown & Brown | Retail & Specialty Brokers | 🌱 Emerging Bull | +0.4% | −24.0% |
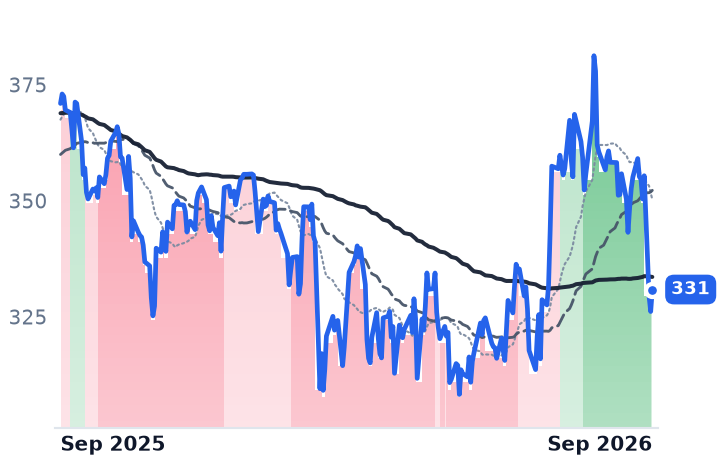
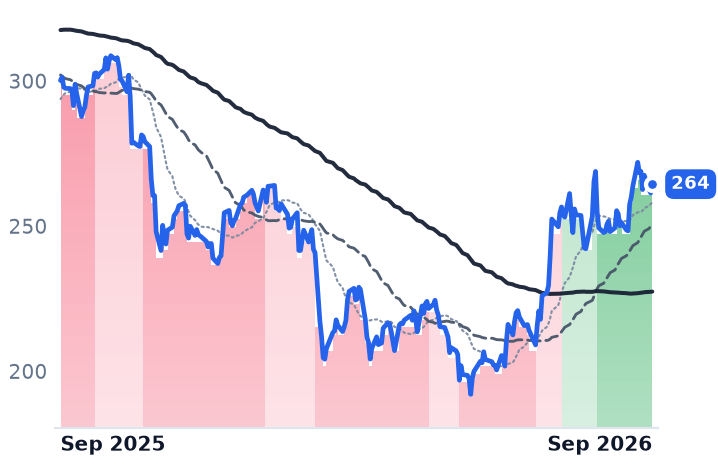
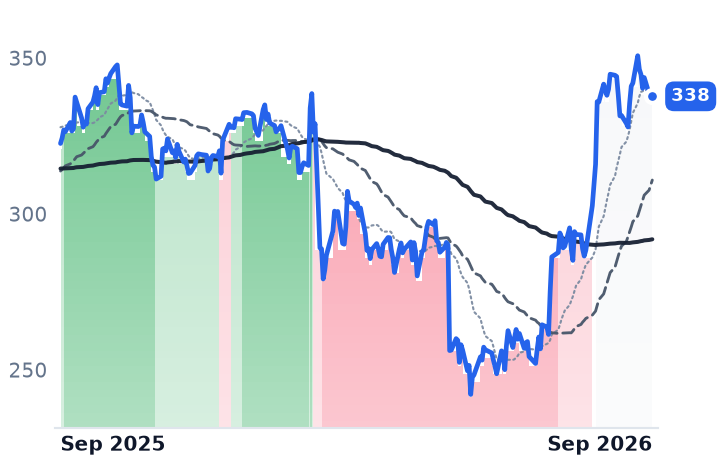
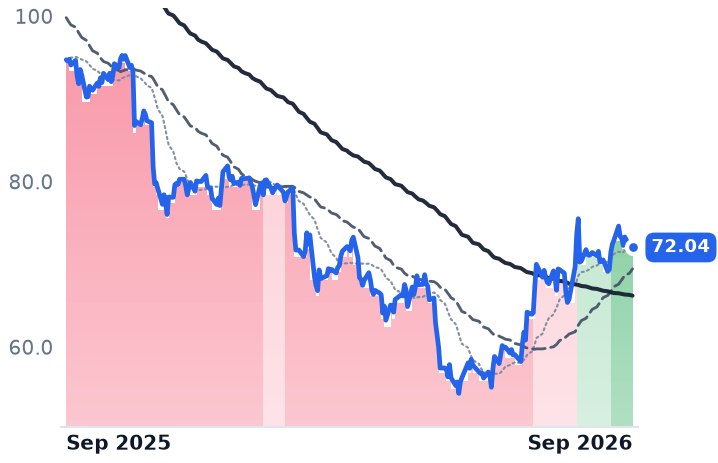
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AON | $70.2B | 18.1x | 17.5x | 4.0x | 3.9x | 4.8x | 4.7x | 13.5x | 4.6% |
AJG | $67.9B | 43.4x | 20.0x | 4.3x | 4.1x | 5.8x | 5.5x | 17.3x | 3.4% |
WTW | $31.4B | 20.7x | 17.0x | 3.1x | 3.0x | 5.8x | 5.6x | 13.7x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BRO | $24.1B | 19.9x | 16.0x | 3.5x | 3.4x | 6.0x | 5.8x | 12.9x | 6.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AON | Revenue | +3.7% | +13.4% | +6.5% |
| EPS | +11.2% | +10.1% | +14.6% | |
AJG | Revenue | +20.4% | +8.8% | +8.9% |
| EPS | +23.9% | +12.7% | +12.8% | |
WTW | Revenue | +8.7% | +5.3% | +5.6% |
| EPS | +16.9% | +15.5% | +18.6% | |
BRO | Revenue | +17.6% | +4.3% | +5.9% |
| EPS | +5.7% | +7.8% | +9.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Aon agreed on 30 August to buy USI Insurance Services from KKR and other shareholders for $17.0bn in cash, funded entirely with new debt, and told shareholders it would stop repurchasing stock until leverage falls back toward its 2.8-3.0x target. USI is the tenth-largest U.S. broker, roughly $3bn of annual revenue across close to 200 offices. Aon's shares fell 7.3% the next session, to $329.45; Gallagher, Willis Towers Watson and Brown & Brown each moved less than 2% that day.
The deal lands in the middle of the softest commercial insurance pricing in years, which matters because a broker is paid a percentage of somebody else's premium. Marsh's Global Insurance Market Index has now recorded eight consecutive quarterly declines, with global rates down 6% in the second quarter, property off 12% and casualty up 2%. Guy Carpenter's property-catastrophe rate-on-line index is down 16% for 2026 to date, its steepest annual fall since the late 1990s, though still about 32% above the 2017 trough.
The base shrank; the revenue did not
The striking thing is how little of that reached the income statements. Aon — the Dublin-based broker whose Risk Capital and Human Capital arms sell commercial and reinsurance placement, health and retirement advice — grew 5% organically in the June quarter, with Commercial Risk, Reinsurance, Health and Wealth each at 5%, adjusted operating margin up 70 basis points to 28.9% and adjusted earnings per share up 9%. Gallagher, the Illinois retail and wholesale broker that also runs the Gallagher Bassett claims business, grew 6%. Marsh & McLennan grew 5% underlying and Willis Towers Watson 5%. Only Brown & Brown broke: organic revenue of -0.7% excluding contingent commissions, with management guiding catastrophe property rates down a further 15-35% in the second half.
Both protagonists quantified the drag. Aon put the net market impact at zero to two points of organic growth, offset by new business contributing roughly ten points for nine straight quarters and retention in the mid-90s. Gallagher told investors only about one point of its organic growth is now tied to rate. "Every other past soft market, the market has dropped like a brick across every line all at once," chairman and chief executive J. Patrick Gallagher Jr. said on the 30 July call. "This is a property reset."
The second income line falls with rates rather than premiums. Aon's fiduciary investment income — the yield on client premium held between collection and remittance — was $58m, down 12% year on year; Marsh guided to roughly $95m for the third quarter. The drag is the tail of three 2025 rate cuts, with none since, and Aon credited part of its margin gain to easing fiduciary headwinds.
What Aon paid
Aon puts USI at 14.5 times EBITDA after $395m of identified synergies, and 16.8 times on unadjusted trailing EBITDA. Gallagher paid 11.3 times post-synergy for AssuredPartners. "By and large, we're paying around nine times for, let's say, U.S. retail and benefits businesses," chief financial officer Doug Howell said of tuck-ins on 30 July. Two buyers, the same middle-market assets, materially different prices.
S&P revised Aon's outlook to negative, expecting pro-forma leverage of 4.3x-4.5x against 2.7x at the end of June; Moody's sees debt to EBITDA above 4.5x. Aon guided the deal dilutive to 2027 adjusted earnings and accretive from 2028. Until 31 August, Aon was deleveraging out of NFP: interest expense fell $33m year on year and its share count has shrunk since 2024. Gallagher's went the other way, up roughly 15.5% since the third quarter of 2024 on AssuredPartners equity, and its June-quarter revenue rose 24.3% to $4.003bn while GAAP operating income fell 5.8%.
What the shares had already done
The group's de-rating was not a grind. On 9 February all four listed brokers gapped in one session — Willis Towers Watson -12.1%, Gallagher -9.9%, Aon -9.3%, Brown & Brown -6.9% — after two AI insurance apps went live inside ChatGPT. Over twelve months Aon is down 11.0% and Gallagher 12.6%, while Willis Towers Watson is up 3.8%. Gallagher has recovered 28.5% in three months, to 20.0 times forward earnings from 14.5 times at its June low.
So the pricing cycle is not the story the prices tell. Falling rates cost these brokers roughly a point or two of growth, and new business covered it; the February gap was a fear about distribution, and the August gap was arithmetic. Aon's compression to 17.5 times forward earnings, from 20.2 times on the same 2026 consensus at last September's high, was unexplained by the business through August — and is now partly explained by a suspended buyback and a dilutive 2027. Gallagher's advance rests on acquired revenue growing organically at about 4%, less than the company's own 6%, at the peer group's highest EV/EBITDA and lowest free-cash-flow yield, with consensus revenue growth halving to 8.8% in 2027 as AssuredPartners anniversaries.
Gregory Case says the prize is the 200,000 U.S. middle-market companies neither giant reaches today. Aon's shareholders will fund that bet out of the repurchases they are no longer receiving, and they will wait until 2028 to see it in earnings.