

Tariff Refunds Added 15.6 Points to Enphase's 60% Gross Margin in the June Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Enphase reported its fattest gross margin in years on a business that shrank for the third quarter running, and almost none of the improvement came from selling more hardware. A $45.4m refund of tariffs the company had paid supplied 15.6 percentage points of the 60% reported figure, which is why the September quarter is guided down to 42–45%. Underneath sit Section 45X manufacturing credits — $85.2m generated on $574.8m of first-half revenue — that Enphase converts to cash at a discount, costing 6.7 points of margin in one quarter alone.
The demand story is no longer about homeowners. With the 30% residential credit expired, roughly 69% of 2026 US installations are expected to be third-party owned, so the marginal buyer is a tax-equity fund waiting on Treasury rules. SolarEdge, growing revenue 20% year on year, is caught in the same gate.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
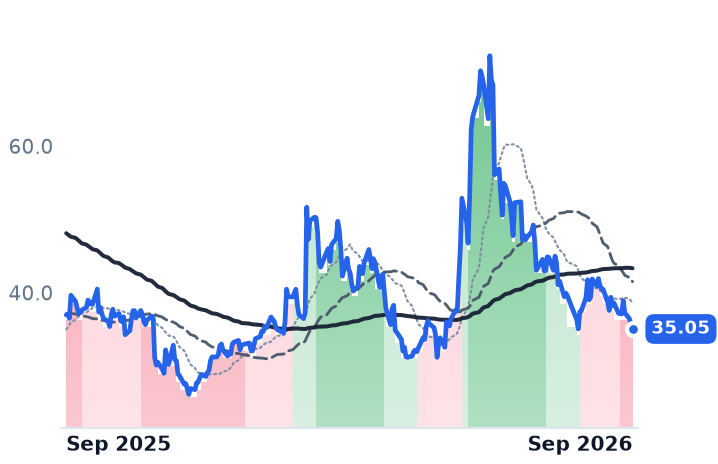
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −10.9% | −5.2% |
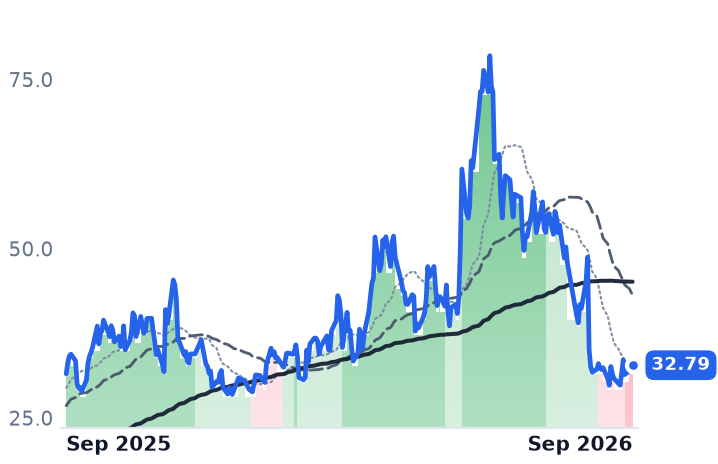
SEDG | SolarEdge Technologies | Inverters & Power Electronics | 🟢 Cont. Bull | −27.3% | +4.0% |
| Compared against · context, not the story | |||||
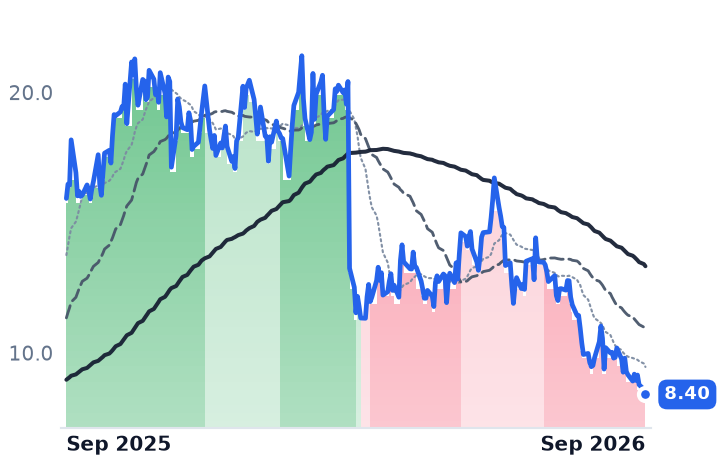
RUN | Sunrun | Residential Solar Installers | ⚠️ Emerging Bear | −19.4% | −47.2% |
FSLR | First Solar | Solar Module Manufacturers | 🟢 Cont. Bull | −13.6% | +2.7% |
NXT | Nextpower | Other | 🟢 Cont. Bull | −9.7% | +22.8% |
ARRY | Array Technologies | Solar Tracking Systems | ⚠️ Emerging Bear | −21.9% | −51.6% |
SHLS | Shoals Technologies | Solar System Components | 🟢 Cont. Bull | −27.5% | +1.1% |
CSIQ | Canadian Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −17.7% | +27.8% |
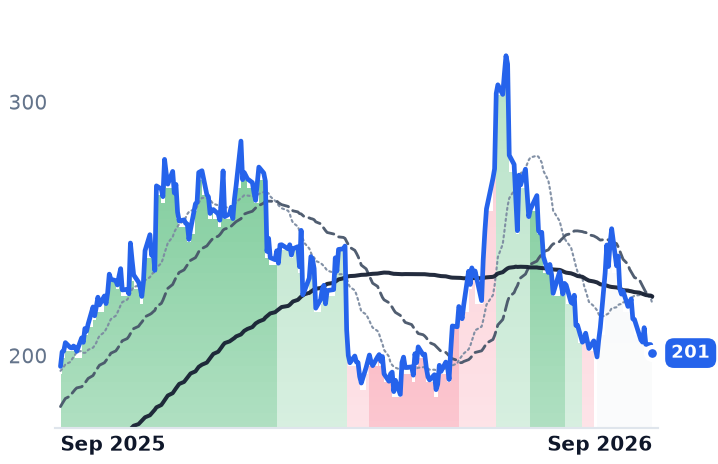
TSLA | Tesla | EV Startups & Luxury | ⚠️ Emerging Bear | +10.8% | +8.3% |
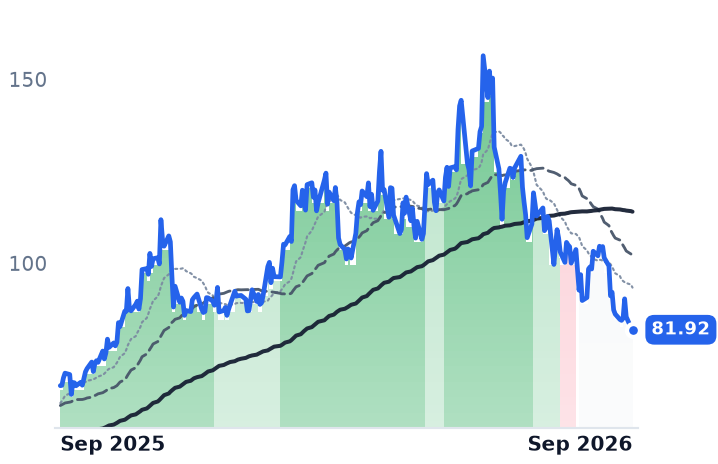
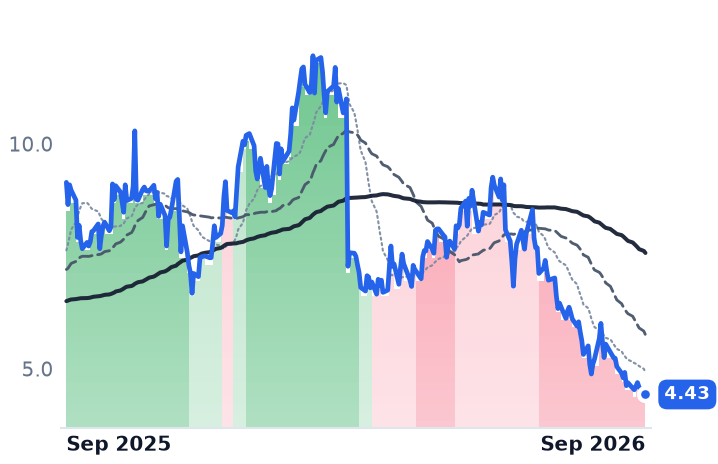
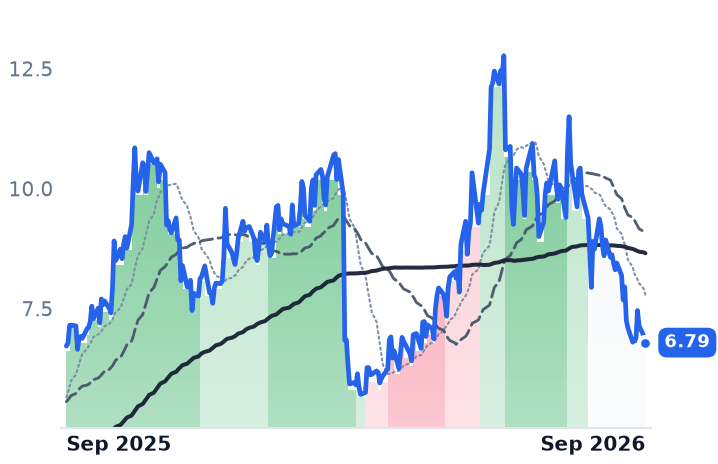
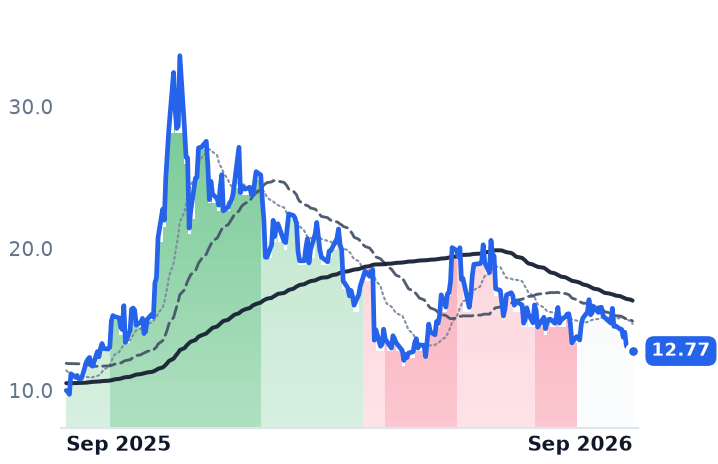
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENPH | $4.6B | 34.3x | 17.5x | 3.5x | 3.9x | 7.4x | 8.3x | 26.5x | 3.3% |
SEDG | $2.0B | n/m | — | 1.5x | 1.5x | 6.8x | 6.8x | n/m | 4.5% |
RUN | $2.3B | 4.0x | 8.1x | 0.7x | 0.8x | 2.4x | 2.5x | 22.0x | -32.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.7B | 13.0x | 11.9x | 4.2x | 4.5x | 9.6x | 10.2x | 8.6x | 5.1% |
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
ARRY | $807.6M | n/m | 7.2x | 0.7x | 0.6x | 2.8x | 2.3x | 301.0x | 12.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
CSIQ | $1.2B | n/m | — | 0.2x | 0.2x | 1.2x | 1.1x | 24.7x | -136.5% |
TSLA | $1.4T | 290.1x | 202.4x | 13.0x | 12.7x | 69.2x | 67.6x | 111.9x | 0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +11.5% | +16.5% | |
SEDG | Revenue | +12.0% | +11.1% | +11.4% |
| EPS | −86.2% | −370.0% | +91.7% | |
RUN | Revenue | +26.6% | +7.7% | +13.7% |
| EPS | −11.7% | −61.6% | +54.2% | |
FSLR | Revenue | −1.1% | +17.0% | +11.0% |
| EPS | +21.1% | +34.6% | +22.8% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
ARRY | Revenue | +14.9% | +9.8% | +5.6% |
| EPS | +9.8% | +23.8% | +13.9% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% | |
CSIQ | Revenue | +9.9% | +17.4% | +6.5% |
| EPS | −38.6% | −236.1% | +107.9% | |
TSLA | Revenue | +11.8% | +13.1% | +18.0% |
| EPS | +2.2% | +32.7% | +39.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Enphase Energy, which makes the semiconductor microinverters bolted under individual solar panels on American and European roofs, reported a gross margin of 60% for the June quarter — and revenue that fell for the third quarter running, to $291.9m, down about a fifth from a year earlier. The margin was the best in years. Almost none of it came from selling more hardware.
What it came from is two federal line items and a refund. That matters beyond one print, because it means the earnings line investors are marking is only loosely a signal about how many roofs got a system this quarter — and the thing that actually governs how many roofs do is now a tax-equity market waiting on rules Washington has not written.
The margin, taken apart
Enphase disclosed that $45.4m of refunded tariffs added 15.6 percentage points to the reported figure; non-GAAP gross margin was 46.8%, and the company guided the September quarter to 42–45% precisely because the refund does not repeat. Beneath that sits Section 45X, the domestic-manufacturing production credit, booked inside gross margin: $85.2m of it was generated on first-half shipments against $574.8m of first-half revenue, worth roughly fifteen further points by that arithmetic. Turning credits into cash costs money — Enphase sold $235.0m of them in the March quarter at 93% of face, and the discount and fees took 6.7 points off GAAP gross margin outright. It has since agreed to sell up to $150m more for no more than $139.5m. The credit itself pays full value only on components sold before 2030, stepping to 75% in 2030, with foreign-entity content restrictions layering on from 2026.
The demand, taken apart
US sell-through fell 34% year on year. Strip out safe-harbor shipments — $84.3m in June against $34.5m in March — and core revenue fell from roughly $248m to roughly $208m sequentially. Enphase guided September revenue to $290–320m while expecting global sell-through up 10%, deliberately under-shipping distributors by about $15m on distributor caution: units improving, sell-in held below them. Europe is the offset, sell-through up 30%, with Dutch battery activations more than doubling ahead of net metering's expiry. "We are not stopping and waiting. We are not waiting for things to improve. We are taking matters into our own hands," chief executive Badri Kothandaraman told investors on the July 28 call.
He has to. The 30% homeowner credit under Section 25D expired on 31 December 2025, while the commercial credit survives for company-owned systems — so roughly 69% of 2026 US residential installations are projected to be third-party owned, and the binding constraint moved from homeowner appetite to tax-equity supply. Those funds are waiting on Treasury's foreign-entity guidance, which Enphase does not expect before the first half of 2027. Freedom Forever, the second-largest US installer, filed for bankruptcy in April with $500m–$1bn of liabilities. And the old duopoly has cracked: Tesla took 29.6% of the US residential inverter market in 2025 against Enphase's 31.7%.
The other one is growing
SolarEdge, which sells string inverters paired with per-panel optimizers, is on the opposite side of the operating line: June-quarter revenue of $346.2m, up 19.6%, gross margin from 11.1% to 27.5%, European revenue more than doubled. "We returned to non-GAAP operating profitability for the first time since the second quarter of 2023, while continuing to generate positive free cash flow," chief executive Shuki Nir said on 5 August. Free cash flow was $3.1m — real, and under 1% of sales. The shares fell 28% that session on a September guide of $310–340m against consensus near $370m, blamed on the same tax-equity freeze.
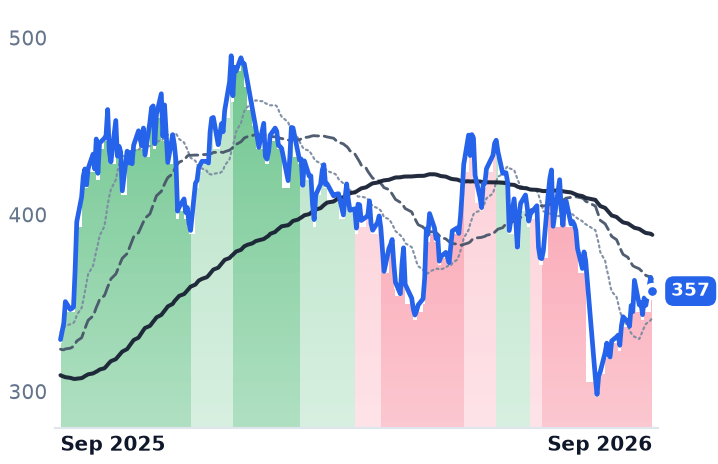
Both stocks peaked on 2 June and have roughly halved, alongside First Solar down 35% and Nextracker down 46% — an unwinding of the May melt-up on data-center solid-state transformers, a product both companies place in 2028 revenue. Since mid-August they have parted: SolarEdge up 10% off its low, Enphase down a further 9%.
The split is visible in the multiples. Enphase trades at 7.42x trailing gross profit and 8.32x forward — forward above trailing, which happens only when consensus models the denominator shrinking, and it does: revenue down 19.1% this year to $1.19bn. That de-rating from 14.55x in mid-May is earned. SolarEdge, at 6.75x trailing and 6.82x forward against 16.09x in May, is being priced as though it shares Enphase's contraction, which its own numbers contradict; the honest caveat is that its guide is a genuine cut and there is no forward earnings anchor, consensus putting 2026 at a loss of $0.35 a share.
What neither company can fix is the gate. Homeowners did not stop wanting solar; the credit that paid for a third of it moved to institutions, and those institutions cannot underwrite until Treasury defines whose parts they may buy. Until then the demand line is a legal question, not a commercial one.