

Edison Reaffirmed 2026 Guidance in July, Then Fell 26.7% When a Wildfire Bill Died
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
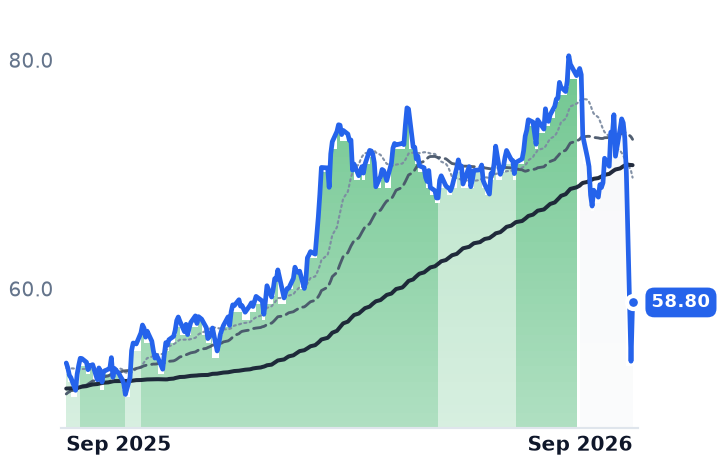
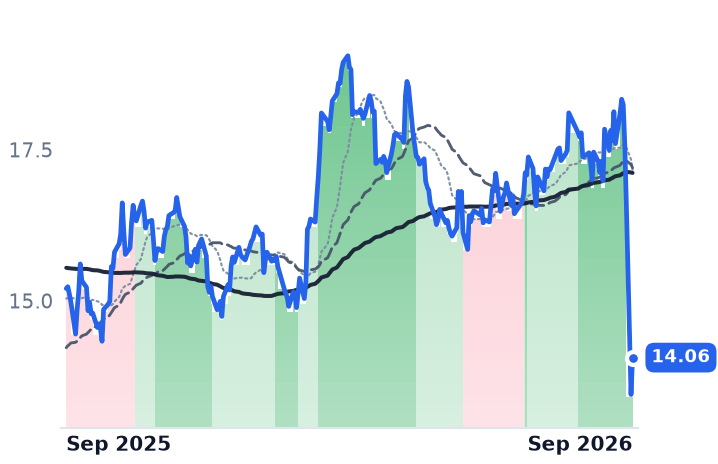
California's wildfire liability rule survived the legislative session untouched, and the two utilities that live under it were repriced on the liability side of their balance sheets rather than on earnings. Senate Bill 492, rewritten over the weekend of 29 August to carry a deal negotiated with Governor Gavin Newsom, arrived without a liability cap; Edison International and PG&E fell hard on the Monday, told lawmakers they had lost $20bn of market value since Thursday, and rebounded on Tuesday when the Assembly let the bill die without a vote.
Neither business is deteriorating. Edison's second-quarter operating income rose 41% and PG&E's 15%, both reaffirmed full-year guidance in July, and consensus earnings estimates for 2026 through 2028 have not been cut. What changed sits behind the equity: state administrators have told the Legislature that a single Eaton fire claim could fully exhaust the $21bn wildfire fund.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
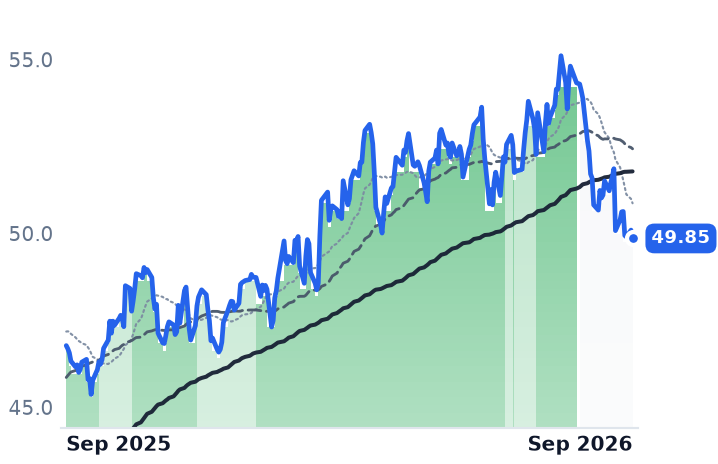
EIX | Edison International | Regional/International Utilities | 🟢 Cont. Bull | −17.7% | +9.9% |
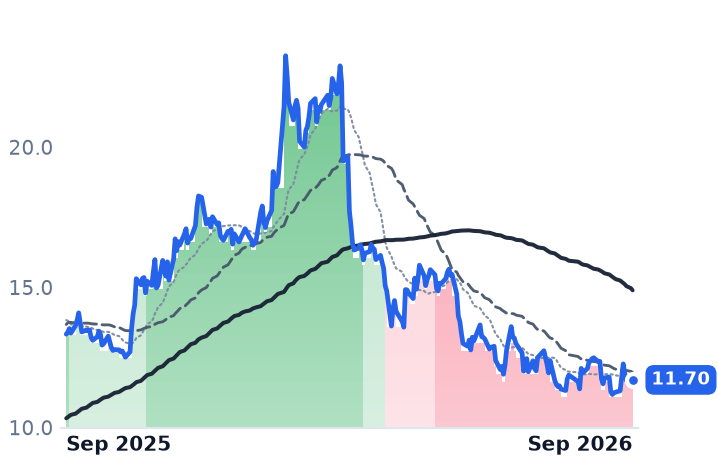
PCG | PG&E | Vertically Integrated Utilities | 🟢 Cont. Bull | −19.3% | −7.5% |
| Compared against · context, not the story | |||||
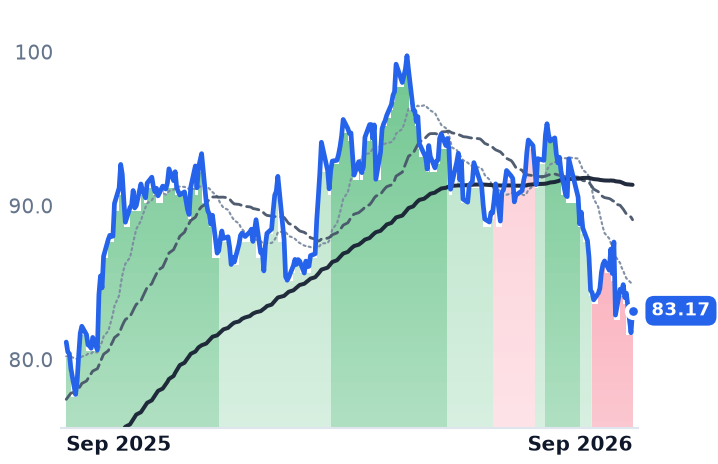
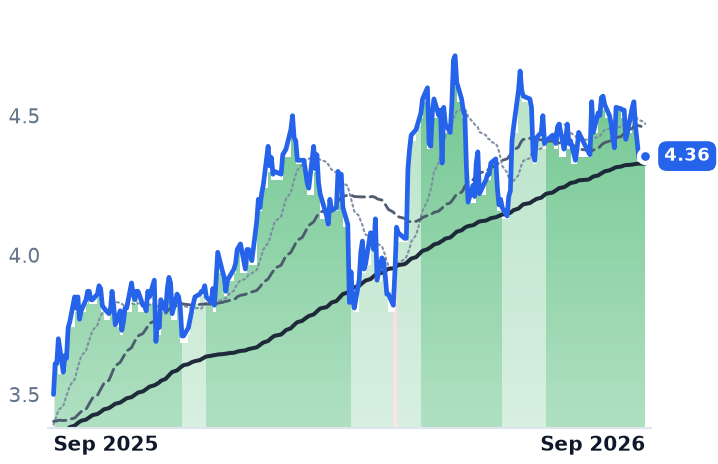
SRE | Sempra | US Electric & Gas Utilities | ⚠️ Emerging Bear | −5.2% | +2.5% |
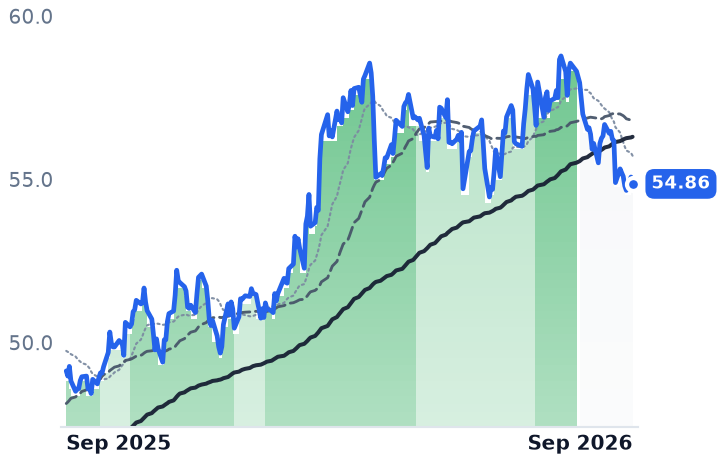
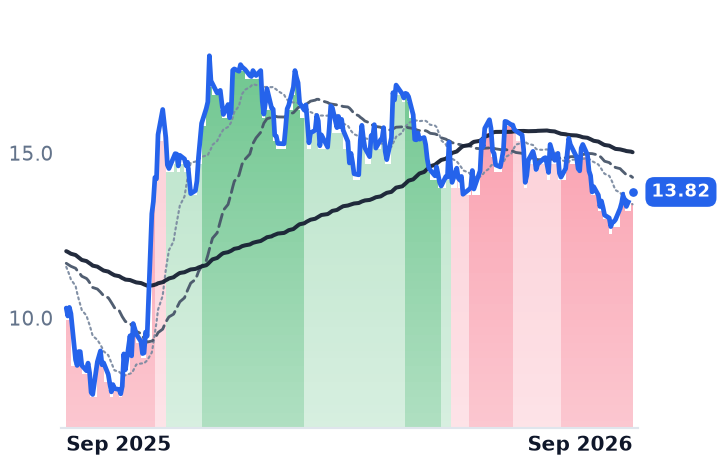
FTS | Fortis | Regional/International Utilities | 🟢 Cont. Bull | −3.0% | +11.7% |
EMA | Emera Incorporated | Regional/International Utilities | 🟢 Cont. Bull | −5.3% | +6.6% |
KEP | Korea Electric Power | Regional/International Utilities | ⚠️ Emerging Bear | −3.4% | −12.2% |
ENIC | Enel Chile | Regional/International Utilities | 🟢 Cont. Bull | −3.4% | +24.4% |
CEPU | Central Puerto | Regional/International Utilities | ⚠️ Emerging Bear | −7.6% | +34.2% |
EDN | Empresa Distribuidora y Comercializadora Norte Sociedad Anónima | Regional/International Utilities | 🔴 Cont. Bear | −10.1% | +13.3% |
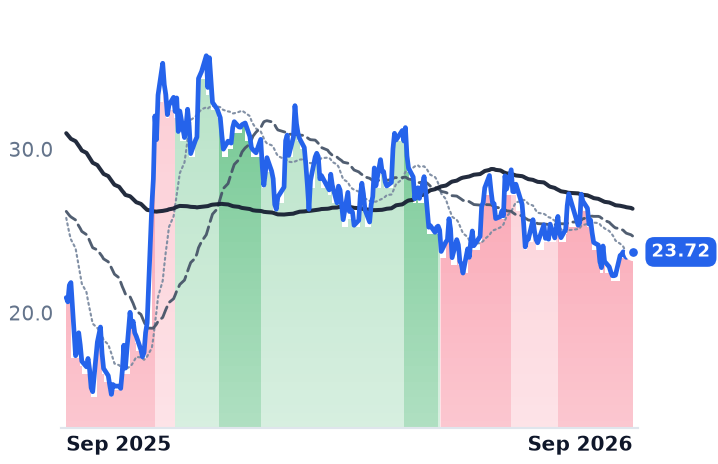
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EIX | $22.6B | 6.0x | 9.6x | 1.2x | 1.2x | 2.9x | 3.0x | 8.4x | -1.7% |
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
SRE | $55.1B | 24.3x | 16.5x | 4.0x | 4.0x | 9.7x | 9.7x | 14.1x | -10.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FTS | $27.8B | 21.2x | 14.9x | 3.1x | 2.1x | 9.6x | 6.4x | 12.5x | -5.6% |
EMA | $15.6B | 20.2x | 19.1x | 2.7x | 2.5x | 15.2x | 14.0x | 19.4x | -8.5% |
KEP | $16.7B | 2.9x | — | 0.3x | — | 0.5x | — | 9.0x | 20.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENIC | $5.8B | 11.1x | 11.0x | 1.3x | 1.3x | 4.2x | 4.2x | 7.1x | 5097.4% |
CEPU | $2.1B | 9.3x | — | 2.9x | — | 8.2x | — | 7.2x | 3.5% |
EDN | $981.3M | 6.3x | — | 0.5x | — | 2.2x | — | 4.6x | -2.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EIX | Revenue | +1.9% | +3.4% | +3.3% |
| EPS | +0.8% | +6.2% | +5.6% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
SRE | Revenue | −3.7% | −1.8% | +1.7% |
| EPS | +11.6% | +8.0% | +8.4% | |
FTS | Revenue | +5.6% | +6.1% | +4.1% |
| EPS | +5.3% | +7.0% | +5.9% | |
EMA | Revenue | +3.2% | +1.6% | +14.9% |
| EPS | +5.6% | −2.5% | +7.7% | |
KEP | Revenue | +5.6% | +1.8% | +1.6% |
| EPS | −11.9% | +20.4% | +5.0% | |
ENIC | Revenue | −2.5% | +2.7% | +2.1% |
| EPS | +1.7% | −0.7% | +6.2% | |
CEPU | Revenue | +30.3% | +4.1% | +2.7% |
| EPS | −21.9% | +4.9% | +17.0% | |
EDN | Revenue | +3.6% | +15.0% | — |
| EPS | −88.2% | +1036.0% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
California's Legislature went home on Tuesday without touching the doctrine that makes an investor-owned utility strictly liable for property damage caused by its equipment, negligent or not. In the four sessions it took lawmakers to get there, the two utilities most exposed to that doctrine lost roughly a fifth of their market value and got most of it back.
What is at stake is not an earnings line but the size of the claim that sits ahead of shareholders. Under inverse condemnation, utility equity is a residual after subrogation settlements and individual claims; the wildfire fund created by Assembly Bill 1054 in 2019 exists to blunt that, with about $21bn of claim-paying capacity and a requirement that a utility absorb the first $1bn itself. Officials administering the fund wrote in a draft annual report to the Legislature that if Edison is found responsible for the Eaton fire, "the resulting claims may be substantial enough to fully exhaust the Fund."
The bill that was written, then unwritten
On 29 August legislative leaders gutted-and-amended Senate Bill 492 — until that weekend a $1bn bond act for homeless youth programs — to carry a wildfire deal negotiated with Governor Newsom. The text that emerged contained no liability cap, no end to subrogation and no per-incident ceiling on fund withdrawals. The underlying framework it was meant to enact had asked shareholders and ratepayers to replenish the fund with up to $18bn and to keep $6bn of mitigation capital out of rate base. The costs survived the drafting; the offset did not.
Edison International, the Rosemead holding company whose Southern California Edison unit serves about 15 million people, closed Monday 31 August at $53.66, down 23.5% on 11.3m shares against a typical one to three million — its worst session since the 2001 energy crisis, Bloomberg reported. PG&E, the Oakland utility supplying electricity and gas across northern and central California, fell 19.0% to $13.45. Selling had started the Friday before. Measured from the 27 August close, the falls reached 26.7% and 23.5%. Bond spreads for both widened alongside the equity. That Monday the two chief executives wrote jointly to Senate leader Monique Limón and Speaker Robert Rivas saying the companies had lost $20bn in market value since Thursday — a figure that reconciles to about $18.5bn across Edison, PG&E and Sempra on closing prices — and warning of "constrained investment, higher utility bills, less spending, and fewer jobs." On Tuesday the Assembly simply declined to take the bill up and it died. Edison rose 9.6%, PG&E 4.5%.
The operating businesses never wobbled
Edison reaffirmed 2026 core earnings of $5.90 to $6.20 a share on 30 July, with second-quarter operating income up 40.9% and margin widening to 25.1%. PG&E reaffirmed $1.64 to $1.66 on 23 July, with operating income up 15.2%, a $73bn capital plan it says needs no equity, and a data-center interconnection pipeline raised to more than 12 gigawatts. Consensus still builds Edison to $6.88 by 2028 and PG&E to $1.97. Both chief executives had named this exact risk a month early. "If there is insufficient action in 2026, there is a strong likelihood that the day after or a few days after, you know, we could see credit rating downgrades for the investor-owned utilities in California," Pedro Pizarro told investors on 30 July; Edison carries an S&P rating one notch above junk. "If the framework remains unresolved or insufficient, then we would need to reevaluate our capital allocation priorities," PG&E's Patricia Poppe said on 23 July. Both companies run negative free cash flow because rate-base spending exceeds operating cash flow, so the debt market is a standing appointment.
What the doctrine, not the sector, did
This was California, not utilities. Over the same five sessions Fortis, Emera, Korea Electric Power, Enel Chile, Central Puerto and Empresa Distribuidora y Comercializadora Norte all finished within two points of unchanged. Sempra, whose San Diego unit is diluted by Texas transmission and gas, fell 3.05% and trades near 16.5 times forward earnings — roughly the long-run median for vertically integrated utilities — against 9.6 times for Edison and 8.5 times for PG&E, which is also priced at 0.91 times book, below the capital on which it earns its authorized return.
The discount is doing real work. Southern California Edison had recorded $1.3bn of Eaton settlement losses as of 31 March with $917m, $295m and $70m of expected recoveries from self-insurance, the fund and federal rates, plus a further $511m of claims in the first half — against a Jefferies estimate of $13.5bn of potential Eaton liability and a market capitalization of $22.6bn. Analysts responding to the bill's failure raised the liability drag on PG&E's value to $10 a share from $6, and downgrades followed within hours, Mizuho cutting Edison to neutral with a $70 target. So the verdict splits cleanly: the operating businesses earn none of the fall, and the entire move so far is multiple rather than estimate. What the market marked down is the statute that was not written — and with subrogation intact and per-incident draws uncapped, the ceiling on Edison's Eaton exposure is now whatever a jury decides it is.
That jury is scheduled. Nearly 1,000 suits allege a decommissioned tower re-energized and sparked the fire, and the first bellwether trial is set for 25 January 2027, a date the judge has refused to move; CAL FIRE's cause finding remains undetermined. Sacramento had eleven months to answer the question and handed it to a courtroom in Los Angeles.