

Digital Realty's Newest Hyperscale Data Centers Sit in a Fund It Owns a Fifth Of
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Digital Realty is building at the widest development spread in its recent history — a 1.4 gigawatt pipeline underwritten to an 11.5% stabilized yield against a 5.28% 30-year Treasury — yet the shares have slipped over three months while revenue grew 28.9% and backlog hit a record. The build economics are not thinning.
What is changing is ownership. The company keeps a 20% interest in the portfolio of its $3.25bn hyperscale fund while managing it for fees, and booked $188m of promote income last quarter that it excluded from guidance. Equinix is funding a doubled capital plan with debt and retained cash, diluting holders by only 1.1% against Digital Realty's 4.6%.
The twelve-month gains are earned by leasing; the recent slide looks like a discount-rate reset, not a demand one.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DLR | Digital Realty Trust | Data Center & Colocation | 🟢 Cont. Bull | −2.2% | +14.4% |
EQIX | Equinix | Data Center & Colocation | 🟢 Cont. Bull | +1.1% | +33.6% |
| Compared against · context, not the story | |||||
IRM | Iron Mountain Incorporated | Records & Information Management | 🟢 Cont. Bull | −5.5% | +31.0% |
NXT.AX | NEXTDC | Information Technology Services | 🌱 Emerging Bull | −1.9% | −20.1% |
AMT | American Tower | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | +0.9% | −9.9% |
CCI | Crown Castle | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | −1.6% | −20.0% |
VNET | VNET | Data Center & Cloud Infrastructure | ⚠️ Emerging Bear | −10.1% | −22.8% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +2.5% | −0.7% |
AMZN | Amazon.com | Online Marketplaces | 🟢 Cont. Bull | −10.3% | +13.0% |
GOOGL | Alphabet | Search & Advertising | 🟢 Cont. Bull | −10.2% | +58.7% |
META | Meta Platforms | Social Media & Messaging | 🔴 Cont. Bear | −1.7% | −20.9% |
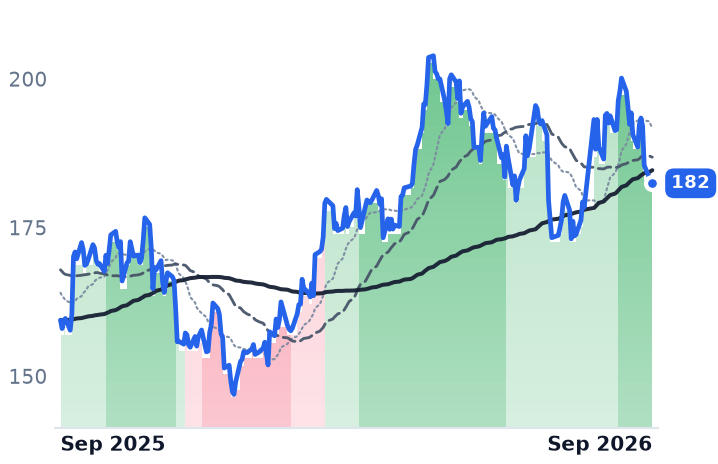
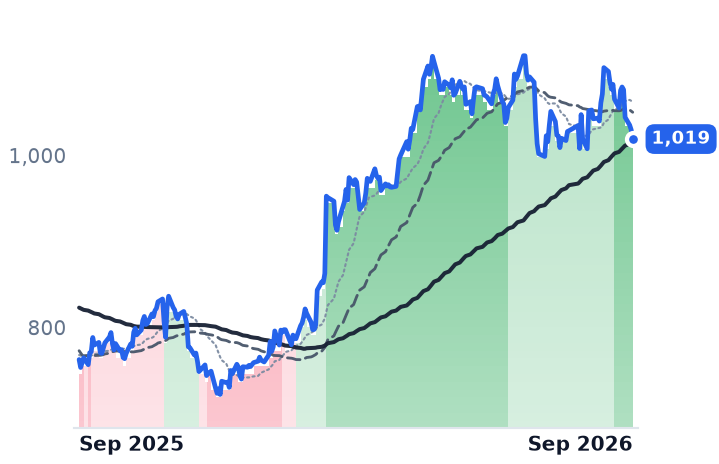
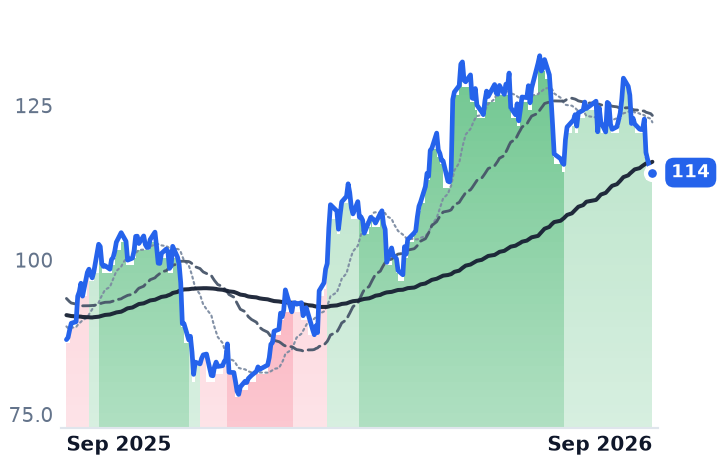
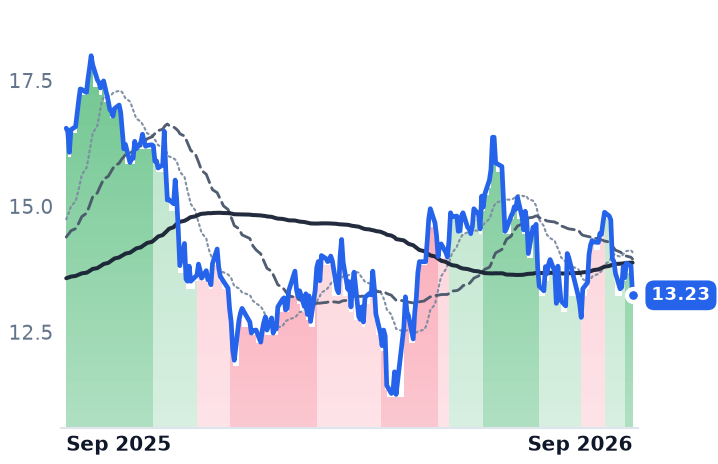
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DLR | $67.5B | 84.1x | 67.4x | 9.9x | 9.5x | 71.6x | 69.2x | 24.6x | 2.0% |
EQIX | $100.6B | 65.3x | 59.1x | 10.2x | 9.8x | 19.8x | 19.0x | 27.4x | 1.4% |
IRM | $33.4B | 80.3x | 45.3x | 4.4x | 4.2x | 8.2x | 7.7x | 21.1x | -1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXT.AX | $10.2B | n/m | — | 22.6x | 14.0x | 730.6x | 453.6x | 57.5x | -16.2% |
AMT | $80.4B | 23.7x | 25.1x | 7.3x | 7.3x | 10.0x | 10.0x | 17.6x | 4.9% |
CCI | $33.0B | 30.6x | 39.3x | 7.9x | 8.2x | 12.5x | 12.9x | 20.4x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VNET | $1.9B | n/m | — | 1.2x | — | 5.8x | — | 9.7x | -58.1% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
AMZN | $2.9T | 21.2x | 21.1x | 3.7x | 3.5x | 7.3x | 6.8x | 11.9x | -0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GOOGL | $4.2T | 17.3x | 17.0x | 9.5x | 8.5x | 15.6x | 13.9x | 13.1x | 1.3% |
META | $1.5T | 21.5x | 18.2x | 6.5x | 5.8x | 7.9x | 7.1x | 14.7x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DLR | Revenue | +17.0% | +11.1% | +14.1% |
| EPS | −26.0% | −4.6% | +23.9% | |
EQIX | Revenue | +11.0% | +10.6% | +11.4% |
| EPS | +16.8% | +9.3% | +10.4% | |
IRM | Revenue | +16.8% | +8.7% | +7.6% |
| EPS | +23.9% | +10.0% | +11.2% | |
NXT.AX | Revenue | +13.5% | +49.6% | +51.1% |
| EPS | +111.5% | +95.8% | +22.2% | |
AMT | Revenue | +4.0% | +3.3% | +5.9% |
| EPS | +34.5% | +1.4% | +10.5% | |
CCI | Revenue | −5.0% | +1.3% | +2.3% |
| EPS | +106.7% | +47.3% | +4.8% | |
VNET | Revenue | +20.5% | +22.0% | +20.8% |
| EPS | −32.3% | −239.3% | +74.3% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
AMZN | Revenue | +15.9% | +14.6% | +16.0% |
| EPS | +76.8% | −16.1% | +30.8% | |
GOOGL | Revenue | +24.3% | +22.9% | +19.1% |
| EPS | +93.4% | −26.6% | +18.2% | |
META | Revenue | +27.3% | +20.1% | +17.8% |
| EPS | +38.3% | +6.9% | +15.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Digital Realty doubled its construction pipeline in the first half of 2026, to 1.4 gigawatts under way at a cost of $20bn, and the returns underwritten on that concrete are wide. The pipeline was 63% pre-leased at an 11.5% average expected stabilized yield pro forma for July hyperscale leases. What has changed is not the yield. It is who ends up owning the buildings.
The wholesale landlord — 309 data centers, roughly 3.0 gigawatts of installed capacity, renting halls to cloud and enterprise tenants — retains only a 20% ownership interest in the portfolio of its $3.25bn U.S. Hyperscale Data Center Fund while serving as manager for leasing, development, asset management and financing. That fund supports more than $10bn of new hyperscale investment. The majority of the rent from that capacity will accrue to limited partners; Digital Realty keeps a fifth of it plus fees, which now run at roughly $45m a quarter and which management expects to convert to operating fees as the assets stabilize. The question for the next several years is whether the AI landlord's return arrives as rent or as fee income, because the two are not valued alike.
The spread is not the problem
An 11.5% expected stabilized yield sits about 620 basis points above the 30-year Treasury yield of 5.28% on September 1, which touched a 19-year high in August. Investment-grade data center debt costs far less than the long bond implies for these two: Equinix closed $700m of notes due 2031 at a 4.400% coupon and $800m due 2033 at 4.700% in March. Development spreads of that width are the opposite of a squeeze.
The leasing behind it is compounding. Second-quarter revenue rose 28.9% to $1.924bn. Signed-but-not-commenced backlog reached a record $1.9bn of annualized rent at full share, of which $635m begins flowing in the second half of this year. Renewals split hard by product: leases above one megawatt repriced 66.7% higher on cash rents, while the 0-1 megawatt colocation band managed 5.2% — the scarcity is in large blocks of powered capacity, not in cabinets. Same-capital cash net operating income grew 8.9%, and full-year core funds from operations guidance was raised to $8.15-$8.20 a share. "Digital Realty delivered record Core FFO per share in the quarter, reflecting robust customer demand and strong execution across our core pillars of growth," chief executive Andy Power said on July 23.
Fees, promotes and a buy-back-in
The quarter also carried $188m of net promote income — about $0.52 a share — from developing and leasing three data centers inside a development joint venture. Management excluded it from guidance, which is the correct signal about its durability. Meanwhile the capital flowed the other way too: at the end of June the company bought Blackstone's blended 64% interest in three fully leased Northern Virginia data centers totaling 288 megawatts, valued at $7.8bn gross, for $3.5bn in cash and stock. Diluted shares are up 4.6% year over year.
Equinix, which rents interconnection-rich cabinet space rather than wholesale halls, is running the same build on different money. Its stabilized estate — 194 of 282 sites — earned a 27% cash-on-cash yield last year, and management guides new capital to a mid-20s percent stabilized return three to four years after buildings open: two points of compression, not a collapse. Capital spending is doubling to $5-6bn this year, funded with debt and retained cash flow; diluted share count rose 1.1%. Adjusted funds from operations per share grew 18% and churn fell to 1.8%.
What the shares have done
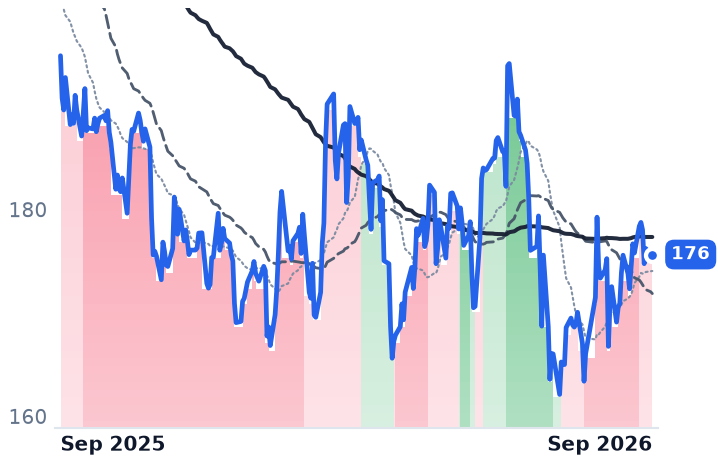
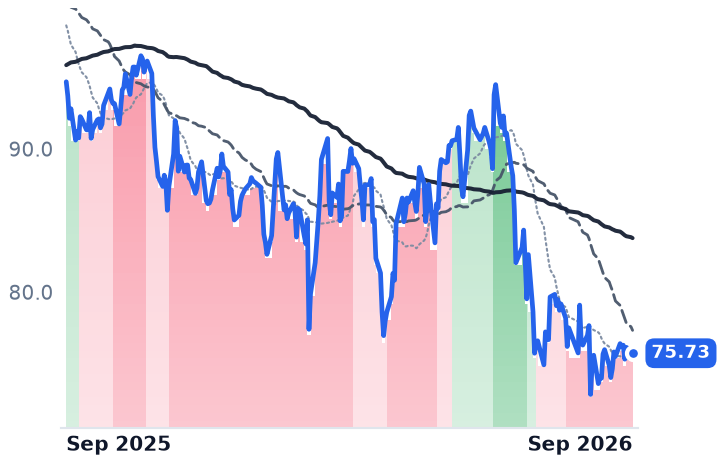
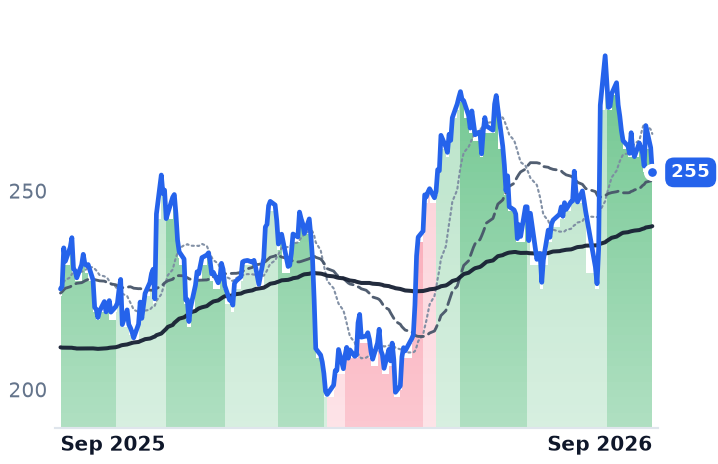
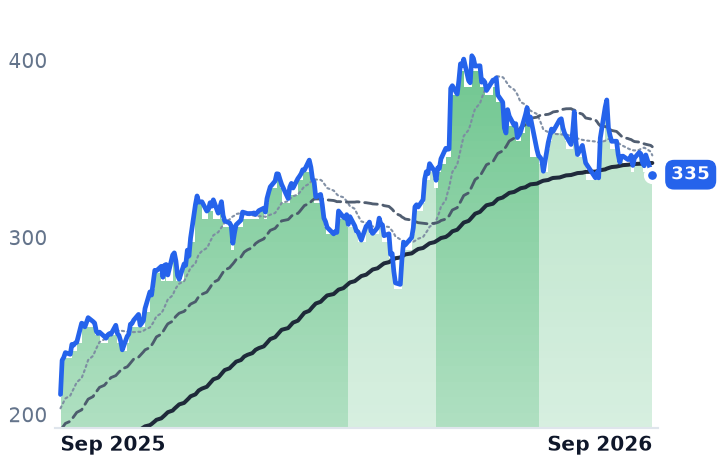
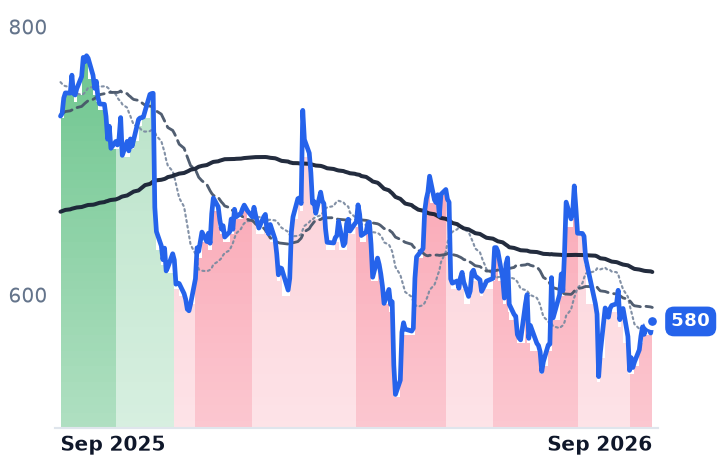
Over twelve months Equinix is up 32.1% and Digital Realty 12.0%, both holding uptrends with their 50-day averages above their 200-day. Over three months both have slipped — Equinix 4.9%, Digital Realty 2.6% — into accelerating numbers. Bank of America cut Digital Realty to neutral in January, trimming its target to $170 from $210 on a lower multiple while expecting listed data centers to stay out of favor despite positive leasing spreads.
The verdict the numbers support: the twelve-month gains are earned by leasing, and the recent softness is a discount rate being applied to very long-duration rent, not evidence of a demand problem. Equinix trades at roughly 23.7x guided 2026 cash earnings of $42.69-$43.29 a share, below the 25-30x forward multiple it historically commanded; Digital Realty at about 22.3x guided core FFO, the low end of its own 22-25x range, with enterprise value at 24.6 times trailing EBITDA. Its reported gross margin is distorted by a presentation change and should be ignored.
The durable risk is not the spread on new construction. It is that the best new gigawatts increasingly land in vehicles where the landlord collects a fifth of the rent and a management fee, and where the upside arrives as promote income that management itself refuses to put in guidance. The $635m of signed rent scheduled to commence this half will show which line it lands on.