

Dell Repriced Faster Than Memory Costs Rose; NetApp Conceded Two Points of Gross Margin
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Memory is the largest bought-in component in an AI server or a flash array, its contract prices have roughly doubled this year, and the three big enterprise hardware vendors are not handling the bill the same way. Dell's July quarter, out after Tuesday's close, shows group gross margin back to 20.93% from 17.75% in the April quarter, with Infrastructure Solutions operating margin at 15% and the full-year revenue guide raised $25bn to $192bn.
NetApp is on the other side: it has guided fiscal 2027 gross margin to 68.5-69.5% against 71.3%, roughly $149m of gross profit given away, and its finance chief has already called the July quarter the trough. HPE reports the same day as NetApp, with consensus modelling margin expansion straight through the shock. Dell's business earns its result; its shares, down over three months, do not yet reflect it.
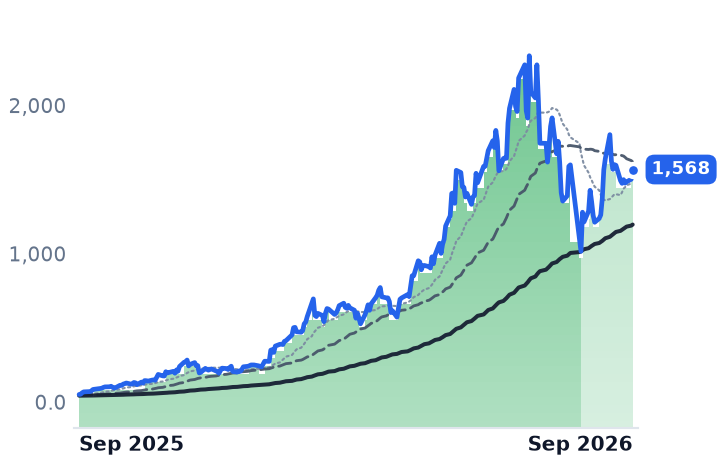
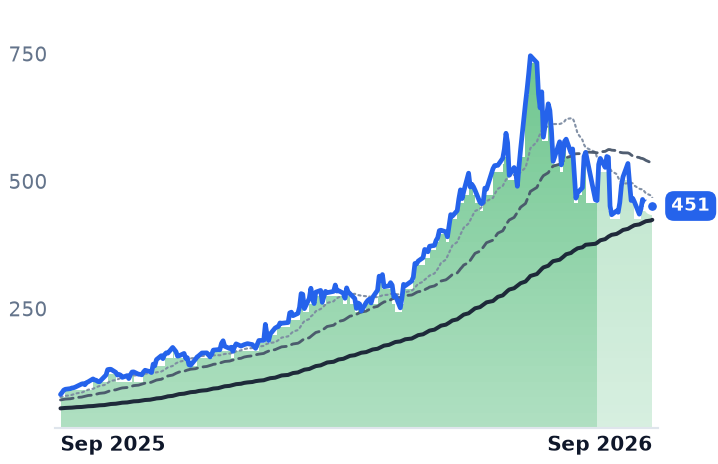
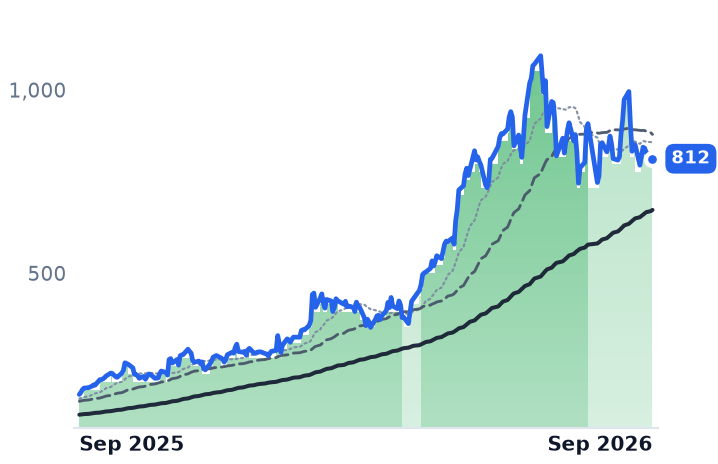
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +1.9% | +265.5% |
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +1.9% | +129.2% |
NTAP | NetApp | Enterprise Storage & Software | 🟢 Cont. Bull | −1.3% | +58.8% |
| Compared against · context, not the story | |||||
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +13.8% | +696.3% |
SNDK | Sandisk | Specialty Manufacturing & Components | 🟢 Cont. Bull | +21.7% | +2970.0% |
WDC | Western Digital | Data Storage Devices | 🟢 Cont. Bull | −14.4% | +452.5% |
STX | Seagate Technology | Data Storage Devices | 🟢 Cont. Bull | −2.3% | +380.0% |
12-month price & trend
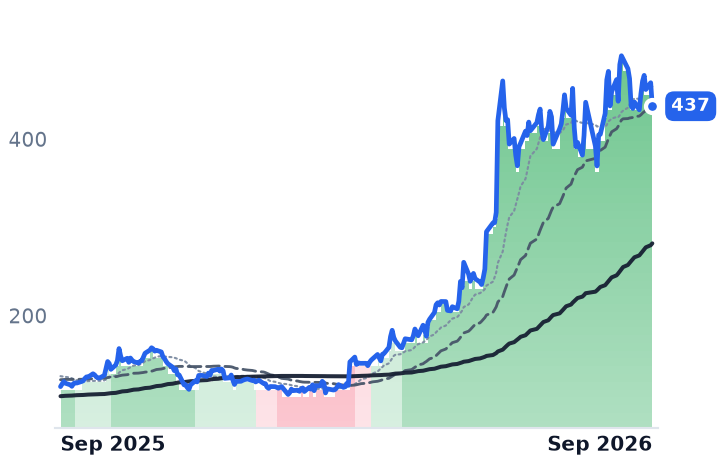
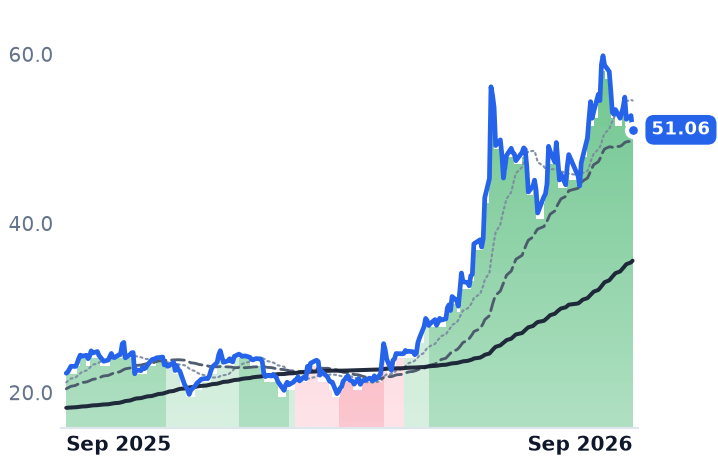
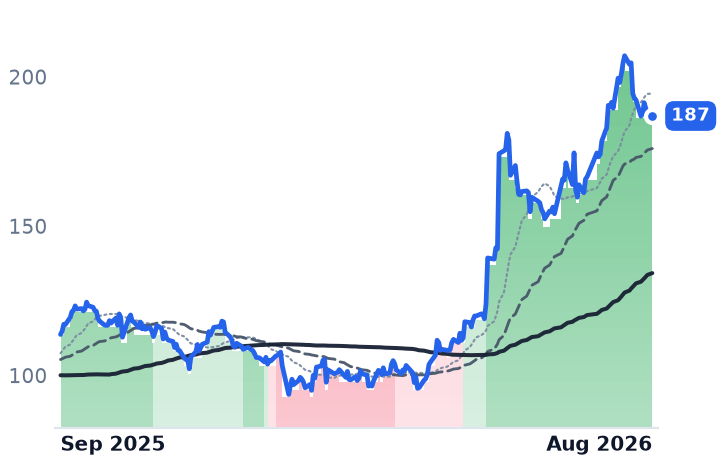
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $282.1B | 24.3x | 22.4x | 1.9x | 1.6x | 9.4x | 8.2x | 17.4x | 2.7% |
HPE | $67.3B | 46.6x | 14.8x | 1.7x | 1.5x | 5.3x | 4.5x | 20.7x | 5.9% |
NTAP | $35.9B | 28.5x | 20.3x | 5.2x | 4.8x | 7.3x | 6.7x | 18.7x | 5.2% |
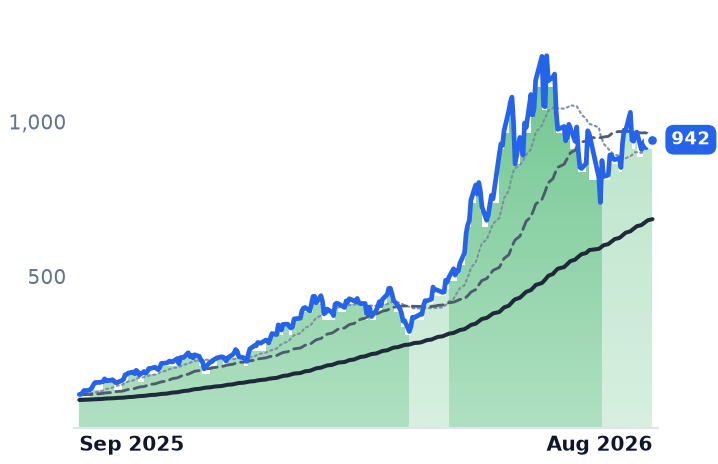
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
SNDK | $232.3B | 20.2x | 7.5x | 11.5x | 4.8x | 16.1x | 6.7x | 17.4x | 4.9% |
WDC | $166.1B | 25.6x | 48.3x | 14.1x | 12.9x | 31.1x | 28.4x | 31.1x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STX | $178.4B | 73.9x | 53.5x | 16.2x | 14.8x | 39.0x | 35.7x | 53.6x | 1.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DELL | Revenue | +16.2% | +55.6% | +15.2% |
| EPS | +27.3% | +90.4% | +22.5% | |
HPE | Revenue | +30.5% | +11.6% | +5.8% |
| EPS | +81.3% | +18.7% | +10.1% | |
NTAP | Revenue | +4.3% | +10.1% | +5.7% |
| EPS | +10.4% | +13.1% | +11.5% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
SNDK | Revenue | +174.4% | +143.0% | +18.2% |
| EPS | +2369.0% | +214.5% | +22.1% | |
WDC | Revenue | +36.9% | +37.2% | +26.5% |
| EPS | +106.2% | +72.8% | +48.0% | |
STX | Revenue | +32.7% | +35.9% | +24.9% |
| EPS | +86.9% | +77.9% | +48.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dell began raising list prices in the middle of December 2025, as memory contract prices were doubling. The quarter it reported after Tuesday's close is the first clean accounting of whether the increases stuck, and they did: group gross margin recovered to 20.93% from 17.75% in the April quarter, against 18.29% a year earlier.
That matters beyond one print because dynamic random-access memory (DRAM) and NAND flash are the largest bought-in components in both an artificial-intelligence server and an enterprise storage array, and the industry has already decided who is protected from the increase. Several US cloud providers hold multi-year supply agreements that restrict their suppliers from raising prices, TrendForce reports, so the increases fall on volumes sold outside those contracts — the position occupied by hardware makers quoting into enterprise and channel deals. NetApp and Hewlett Packard Enterprise both report on 2 September, and the question each answers is whether it repriced or absorbed.
The cost side is not subtle
Enterprise solid-state drive contract prices rose about 80% quarter on quarter in the first quarter of 2026 and a further 70-75% in the second, outpacing DRAM for the first time in the cycle before moderating toward a forecast 10-15% in the third. Server DRAM is guided up 13-18% quarter on quarter in the current quarter. The supply arithmetic behind it: registered memory module bit supply grows only 15-20% a year, well short of server processor shipment growth.
Dell repriced; the numbers followed
Dell, the largest AI server maker by volume and a seller of servers, storage and PCs from Round Rock, Texas, moved early and publicly. It raised PC prices 15-20% from mid-December, then repriced tens of thousands of open quotes on 6 January by compressing discounts. "We're repricing, it feels like, every day," chief operating officer Jeff Clarke said of the pace.
July-quarter revenue of $46.971bn rose 57.7%, while operating income rose 204% — more than three times the revenue rate. Infrastructure Solutions, which ships the servers and storage, posted a 15% operating margin, up 620 basis points from a year earlier, on record segment revenue of $31.8bn. Storage revenue grew 26% and traditional servers 122%, so this is not an AI-mix illusion. Dell lifted full-year guidance by $25bn to $192bn of revenue, with adjusted earnings of $25.50 a share, and reported gross profit dollars up 78%.
Two things sit underneath. Inventory roughly doubled to $21.29bn from $10.44bn at the January year-end, faster than first-half sales grew, according to coverage of the release — component buying ahead of price rises. And the backlog is the exposure: "We exited the quarter with a record $95 billion of AI backlog," Clarke told investors on 1 September. Backlog is struck at quoted prices and ships into later component costs.
NetApp is eating it
NetApp, which sells all-flash arrays built on its ONTAP software plus native storage services inside all three big clouds, is the most flash-levered of the three and has guided fiscal 2027 gross margin to 68.5-69.5% from 71.3%, roughly $149m of foregone gross profit on its own revenue guide of 6-9% growth. Chief financial officer Wissam Jabre told the April-quarter call the "July quarter is more or less the trough" for product margin, with relief only as its own price increases take effect later. That trough quarter is what it reports on 2 September. It trades at 20.3x forward earnings and $7.34 of market value per dollar of trailing gross profit, down from $8.17 on 22 August on price alone.
HPE, whose server and storage business now carries an acquired Juniper networking portfolio, guided its July quarter to $11.5-12.1bn of revenue and adjusted earnings of $0.88-0.93 a share. Consensus has its margins expanding through the shock, with earnings before interest, taxes, depreciation and amortization at 20.5% of revenue this year and higher next. It is the cheapest of the three on forward earnings at 14.79x, though on enterprise value, which charges the Juniper debt, 20.75x trailing EBITDA puts it above Dell.
The verdict
Dell's shares fell 6.1% over the three months to Tuesday, including 5.74% in the session before the release, while HPE gained 12.7% and NetApp 3.0%. On 22 August, Dell cost $12.04 for each dollar of trailing gross profit; after the July quarter entered the window it costs $9.42, a de-rating of roughly a fifth done by profit rather than by price. The operating result is earned — repricing machinery, an AI customer base past 6,500, operating expense at 8% of revenue. What the accounts do not explain is the share price, and the honest caution is the $95bn of backlog quoted before the next round of increases.
The split now has a test date. NetApp has pre-announced its own trough and HPE's consensus assumes it never had one; both print on Wednesday, and only one of those can be right about a bill that has to land somewhere.
The suppliers already know where. Micron's shares are up roughly 695% over the twelve months its customers have spent arguing about who pays.