

HPE Guided GreenLake to $3.5bn While Guiding Total Revenue Up as Much as 33%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
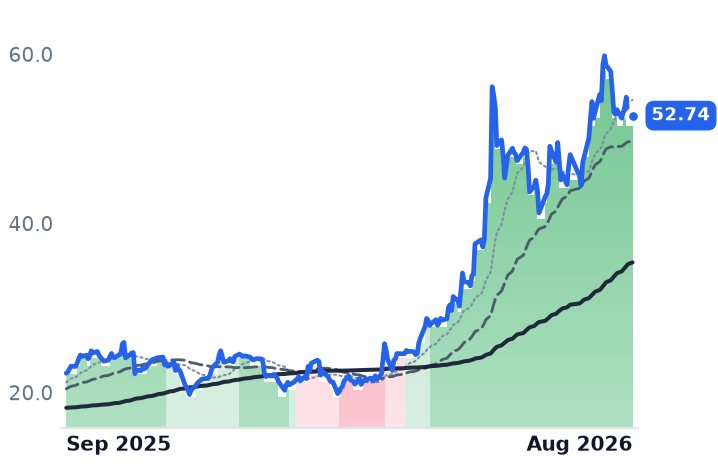
Hewlett Packard Enterprise reports Wednesday carrying the cheapest forward earnings multiple in enterprise hardware and the slowest-growing subscription business in it. The consumption meter management points investors to, GreenLake's annualized revenue run rate, exited fiscal 2025 at $3.2bn against a $3.5bn target for this year — single-digit growth at a company guided to grow revenue 29% to 33%.
What is working is the hardware. The merged Cloud & AI segment earned a 12.4% operating margin in the April quarter against 6.6% a year earlier, which falsifies the fear that AI servers ship as pass-through boxes. Networking's revenue more than doubled, but almost all of that is acquired Juniper volume; organic growth was about 10% and the segment's own margin fell to 21.6% from 25.0%.
The equity looks cheap only until the Juniper debt is charged: on enterprise value to EBITDA, HPE sits at 21.2x against Dell's 22.2x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +5.3% | +136.7% |
| Compared against · context, not the story | |||||
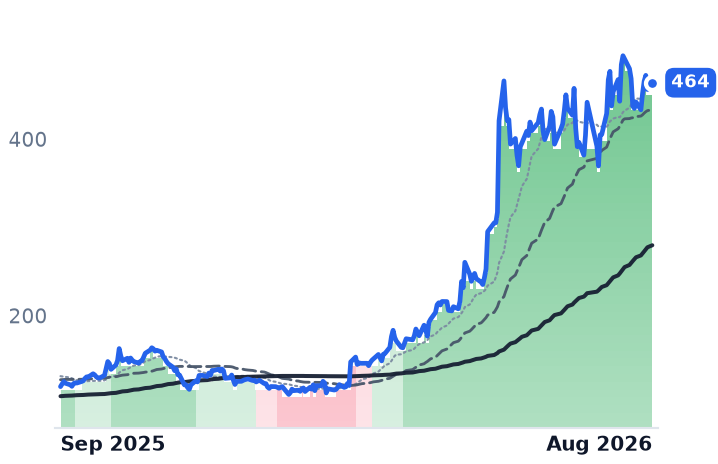
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +8.1% | +287.8% |
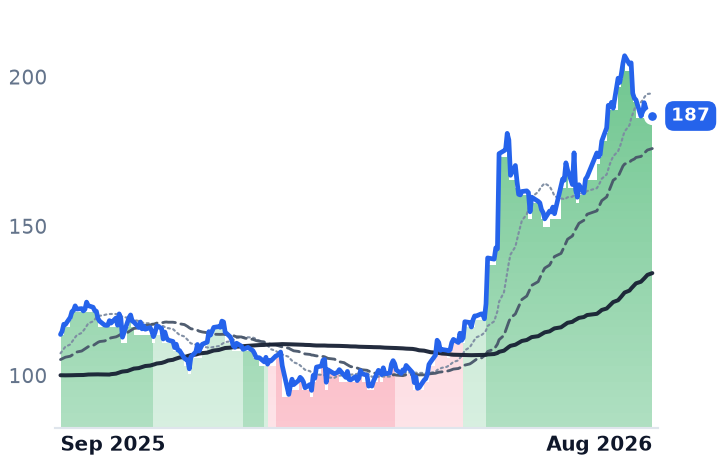
NTAP | NetApp | Enterprise Storage & Software | 🟢 Cont. Bull | +2.2% | +64.3% |
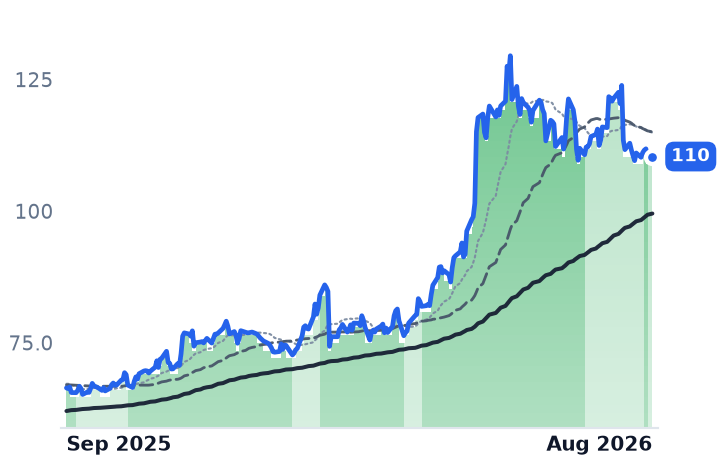
CSCO | Cisco Systems | Enterprise Networking Infrastructure | 🟢 Cont. Bull | −4.7% | +66.2% |
ANET | Arista Networks | Cloud Networking | 🟢 Cont. Bull | +5.8% | +43.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HPE | $69.2B | 47.9x | 15.2x | 1.8x | 1.5x | 5.4x | 4.7x | 21.2x | 5.8% |
DELL | $308.2B | 36.3x | 24.6x | 2.3x | 1.8x | 12.1x | 9.3x | 22.2x | 3.1% |
NTAP | $36.7B | 29.1x | 20.7x | 5.3x | 4.9x | 7.5x | 6.9x | 19.1x | 5.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CSCO | $442.9B | 33.4x | 21.9x | 7.0x | 6.1x | 10.8x | 9.4x | 23.2x | 3.1% |
ANET | $237.5B | 58.8x | 45.9x | 22.5x | 18.7x | 35.8x | 29.8x | 46.1x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HPE | Revenue | +30.5% | +11.6% | +5.8% |
| EPS | +81.3% | +18.7% | +10.1% | |
DELL | Revenue | +16.2% | +55.3% | +14.9% |
| EPS | +27.3% | +89.4% | +21.3% | |
NTAP | Revenue | +4.3% | +10.1% | +5.7% |
| EPS | +10.4% | +13.0% | +11.2% | |
CSCO | Revenue | +11.1% | +16.2% | +7.1% |
| EPS | +12.9% | +19.7% | +9.2% | |
ANET | Revenue | +42.4% | +30.0% | +23.9% |
| EPS | +42.4% | +27.2% | +22.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Hewlett Packard Enterprise reports its fiscal third quarter after the close on Wednesday, September 2, and the shares have spent three weeks losing ground into it. The company sells ProLiant and Cray servers, Alletra storage, Aruba and Juniper networking equipment, and rents infrastructure by the unit consumed under the GreenLake brand. It has guided the quarter to revenue of $11.5bn to $12.1bn and non-GAAP earnings of $0.88 to $0.93 a share.
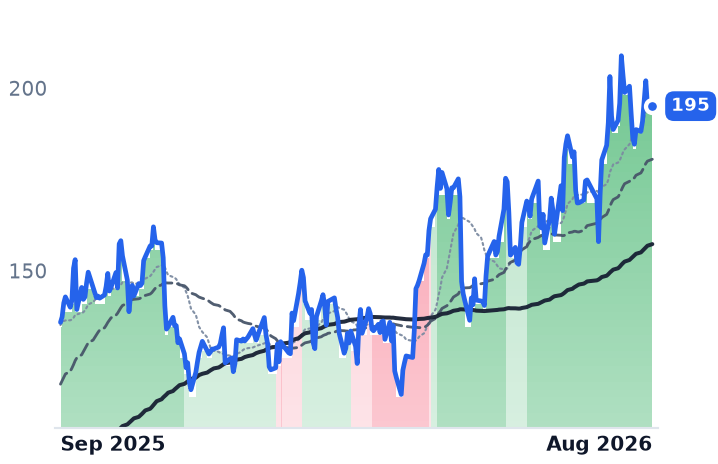
The stake is which engine investors have been paying for. HPE closed at $52.74 on Monday, up 145.6% over six months and 88.8% since late April, when its 50-day average crossed above its 200-day and stayed there. This was not a quiet grind: the single largest session was a nearly 24% jump on June 2, the day after the company's own second-quarter print, and twelve sessions inside the advance moved 4% or more in one direction or the other. The repricing followed disclosure. The question is what the disclosure actually contained.
The box repriced upward
The strongest finding contradicts the standard bear case on AI servers. Revenue in the April quarter rose 40.7% to $10.68bn and gross margin expanded almost nine points to 36.5%. Inside that, the newly merged Cloud & AI segment — server, hybrid cloud and financial services, combined into one line effective at the start of fiscal 2026 — earned a 12.4% operating margin on $7.71bn of revenue, against 6.6% a year earlier. Systems built around scarce accelerators and scarce memory are not shipping at pass-through prices.
They are not shipping at last year's terms either. Chief executive Antonio Neri told investors in March that HPE had "amended our quoting terms with the right to reprice existing orders for commodity cost increases between quoting and shipment," with memory and storage now more than half the price of a server. Dell, the closest comparable, went the other way at the gross line: its quarter ended May 1 grew revenue 87.5% while gross margin fell to 17.8%. HPE defended price; Dell defended volume.
Juniper supplied the growth, not the margin
Networking revenue of $2.7bn grew 148.2%, and almost none of it is organic. Stripping the acquisition, normalized networking growth was about 10%, with campus-and-branch orders in the upper-20% range. The segment's operating margin fell to 21.6% from 25.0% — acquired mix lifted the revenue line and diluted the rate. What the deal bought is position: Dell'Oro Group reports that combined HPE-Juniper campus switching revenue is now roughly level with Huawei's, and that HPE is the only vendor besides Cisco with a full line-up across campus, data center, security and routing.
Cost action is doing visible work too. HPE has cut headcount by more than 9% since its Catalyst program began and booked roughly $1.4bn of gross proceeds from closing the H3C sale. "Workforce transformation continues to drive the majority of our savings, and GenAI enabled process simplification now represents nearly 20% of our fiscal 26 initiative savings," finance chief Marie Myers told analysts on June 1. Net leverage is down to 2.3x, with the 2x target now expected a year early.
The meter is the laggard
GreenLake is the part of HPE that most resembles the software businesses it is priced against, and it is growing slowest. The annualized run rate exited fiscal 2025 at $3.2bn, up 63% with Juniper's contribution inside it, against a reaffirmed $3.5bn exit target for fiscal 2026 — roughly 9% growth in a year the company guides revenue up 29% to 33%. The metric is also constructed rather than contracted: HPE defines it as a quarter's GreenLake, software-consumption and related financial-services revenue — including rental income from operating leases and interest from finance leases — multiplied by four. Folding hybrid cloud into Cloud & AI removed the line where GreenLake's own segment margin used to be visible.
What the advance has earned
On forward earnings HPE is the cheapest of its group at 15.2x, against Dell at 24.6x and NetApp at 20.7x, on consensus fiscal 2026 earnings of $3.44 a share. Trailing earnings are unusable — fiscal 2025 net income was $57m on $34.3bn of revenue after deal and restructuring charges. Charge the roughly $14bn of Juniper financing and the discount evaporates: 21.2x enterprise value to trailing EBITDA, against Dell's 22.2x and NetApp's 19.1x. The share count is 8.3% larger than a year ago.
So the advance is paid for, but not by the story the GreenLake brand implies. Repriced systems, Juniper scale, a 9% smaller workforce and a divestiture explain the earnings; the consumption meter explains almost none of it, and the equity multiple only looks generous while the debt is ignored. Consensus already assumes the fade, with fiscal 2027 revenue growth of 11.6% against 30.5% this year — close to the 8% to 12% framework HPE itself published.
Wednesday tests conversion rather than demand. HPE entered the quarter with $5.9bn of artificial-intelligence systems backlog, a record, and has said it assumed no incremental memory supply this year beyond existing allocations. Orders it cannot fill are somebody's revenue next year, and possibly somebody else's.