

AvePoint Guided to 26% Growth; Currency Supplies Six of Those Points
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
AvePoint's units and its currency are telling different stories. The managed-service-provider channel now supplies 59% of annual recurring revenue and drove two-thirds of the quarter's additions, and customers paying more than $100,000 a year rose 26% to 911 — the best growth in over three years.
But the raised full-year guide of 26% recurring-revenue growth becomes 20% once exchange rates are stripped out, and management framed the change as a small operational raise offset by a larger currency headwind. Meanwhile the platform AvePoint sells around has shipped a competitor: Microsoft Agent 365 became generally available on 1 May at $15 per user a month. AvePoint's own agent-governance product only got a standalone price list in July, with no revenue attached to it yet.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AVPT | AvePoint | Business Software & Automation | 🌱 Emerging Bull | +4.5% | −14.0% |
| Compared against · context, not the story | |||||
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +4.7% | +1.5% |
SPSC | SPS Commerce | Business Software & Automation | 🔴 Cont. Bear | +12.8% | −20.1% |
CCC | CCC Intelligent Solutions | Business Software & Automation | 🌱 Emerging Bull | +19.1% | −23.4% |
EVCM | EverCommerce | Business Software & Automation | ⚠️ Emerging Bear | −25.7% | −20.9% |
PATH | UiPath | Business Software & Automation | 🔴 Cont. Bear | +42.7% | +70.9% |
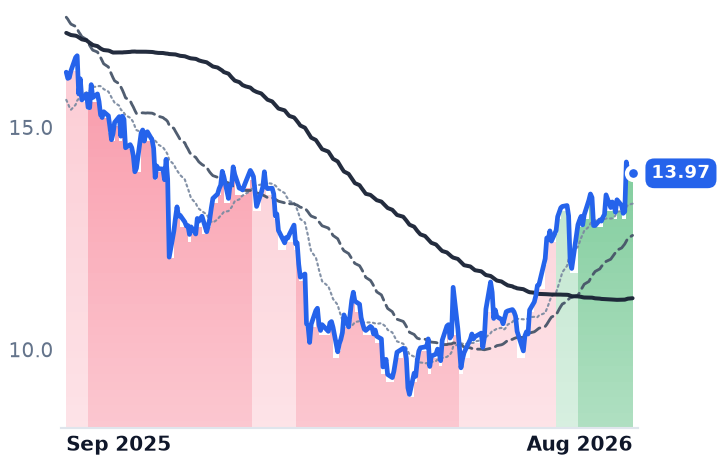
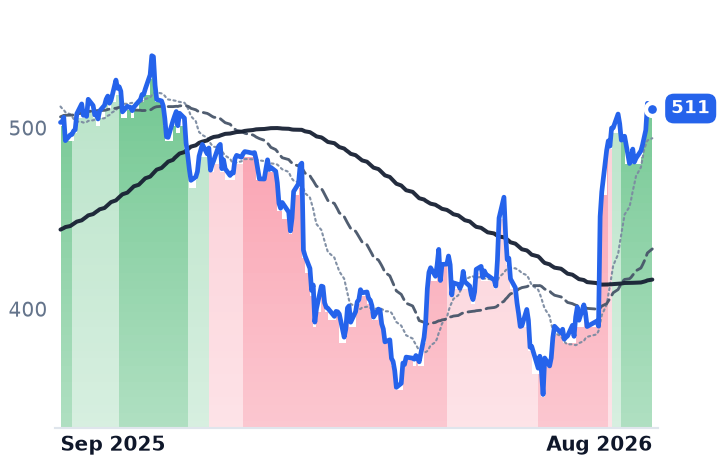
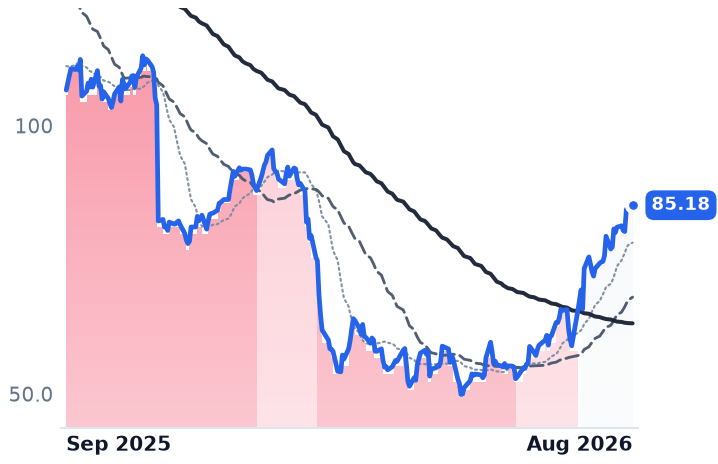
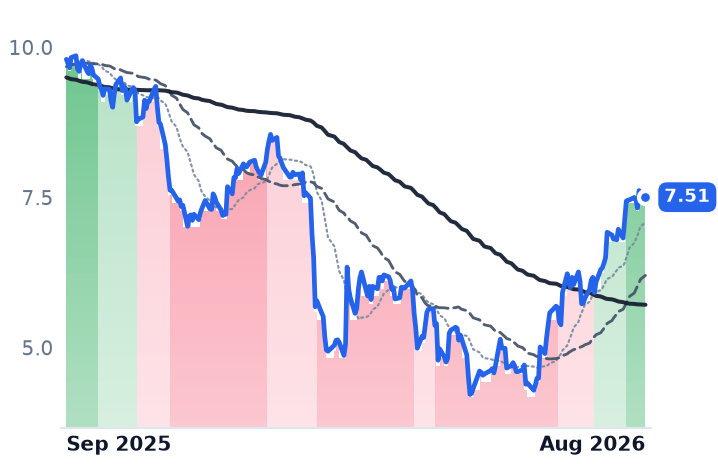
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AVPT | $3.0B | 41.8x | 31.1x | 6.4x | 5.8x | 8.7x | 7.9x | 35.7x | 3.4% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
SPSC | $2.9B | 39.0x | 16.5x | 3.8x | 3.7x | 5.4x | 5.3x | 15.0x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCC | $4.1B | 105.6x | 15.5x | 3.7x | 3.5x | 5.0x | 4.8x | 16.9x | 7.5% |
EVCM | $1.8B | 53.7x | 13.6x | 2.9x | 2.9x | 3.9x | 3.8x | 16.1x | 5.3% |
PATH | $9.7B | 30.1x | 23.2x | 5.8x | 5.4x | 7.0x | 6.5x | 56.8x | 3.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AVPT | Revenue | +22.9% | +20.5% | +19.7% |
| EPS | +33.4% | +10.4% | +28.6% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
SPSC | Revenue | +5.1% | +6.3% | +7.2% |
| EPS | +18.8% | +8.6% | +13.3% | |
CCC | Revenue | +10.1% | +8.9% | +8.2% |
| EPS | +25.4% | +16.1% | +13.7% | |
EVCM | Revenue | +4.6% | +4.6% | +4.5% |
| EPS | +677.9% | +5.4% | +4.9% | |
PATH | Revenue | +11.4% | +11.5% | +8.4% |
| EPS | +40.5% | +16.2% | +15.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
AvePoint's June-quarter numbers have been public since 6 August. What has not been read out of them is how much of the raised full-year outlook is exchange rates. The company — which sells governance, backup, migration and now artificial-intelligence readiness for data that lives inside other vendors' clouds, mostly Microsoft 365 — lifted its full-year recurring-revenue guide to a range of $522.1m to $528.1m, 26% growth at the midpoint. Adjusted for currency, that guide is 20%.
The six-point gap matters because the rest of the quarter argues that AvePoint's unit growth is genuine, and because the platform it depends on has just entered its newest product line. On 1 May, Microsoft made Agent 365 generally available, a control plane for observing and governing artificial-intelligence agents, priced at $15 per user a month standalone and included free in a $99-per-user Microsoft 365 tier. AvePoint's competing product, AgentPulse, only became a separately priced per-seat item in July.
The units are real
Strip the currency out and the customer file still improves. Net new recurring revenue of $29.9m was a record, up 35% year on year and the thirteenth straight quarter of double-digit growth in that measure. Customers above $100,000 of annual recurring revenue reached 911, up 26%, with the $250,000, $500,000 and $1m cohorts each growing at 30% or better. The managed-service-provider channel — roughly 2,000 partners reselling into the midmarket — now carries 59% of total recurring revenue against 56% a year earlier, and supplied 67% of the quarter's additions.
Against that, reported revenue growth is slowing: 28.6% in the December quarter, 26.0% in March, 22.0% in June to $124.5m. Gross margin slipped 94 basis points to 73.1%, which management attributed to channel and services mix rather than the cost of delivering artificial intelligence — software product margins held at 83%. Gross retention is a modest 89%, with net retention at 110%; migration work, which customers finish and stop paying for, costs about two points of that.
What the raise actually was
Management described the guidance change as roughly $1m of operational improvement set against $2m of incremental currency headwind on recurring revenue, and a $3.7m revenue beat against $5.6m of incremental currency headwind on the revenue line. Europe, the Middle East and Africa grew 34% reported and 27% in constant currency — the widest gap of any region. "Our excellent second quarter results reflect the growing demand for trusted AI, as we accelerated topline growth, outperformed all guided metrics, and delivered record net new ARR," chief executive Tianyi Jiang said in the 6 August release. Investors disagreed: the shares fell 4.7% the next session.
On the call Jiang argued AvePoint works hand-in-hand with Agent 365 but goes deeper — delegated administration, cross-cloud coverage, tracking what agents cost — and that many customers hold mixed licences rather than the $99 bundle. The cross-cloud claim is the load-bearing one, and it is the part Microsoft has not finished: Agent 365's discovery of agents running on Amazon Bedrock and Google Cloud is still in public preview. AvePoint publishes no split of revenue by underlying platform, so how much of the base sits on Microsoft tenants cannot be checked from its filings.
The price and the multiple
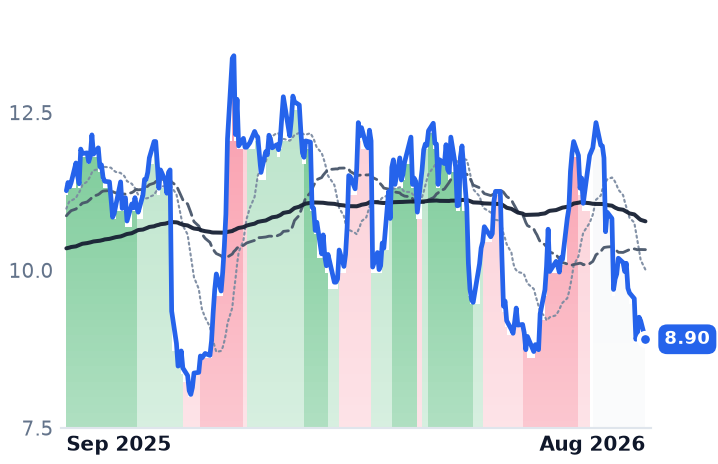
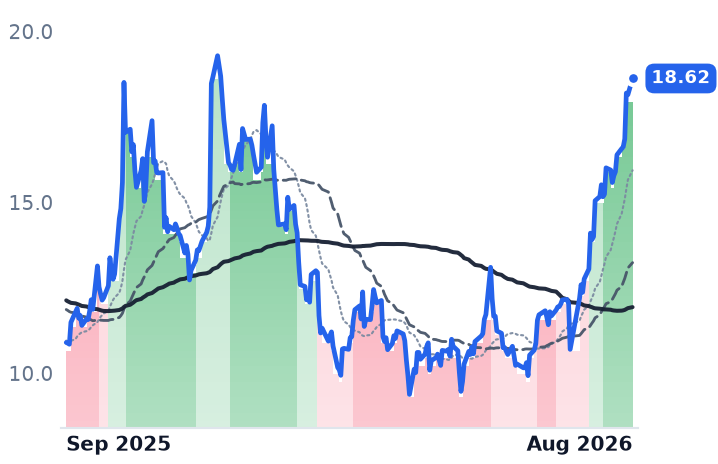
Shares rose 4.5% over the past thirty days while CCC Intelligent Solutions gained 19% and SPS Commerce nearly 13% — AvePoint under-participated in the broad rebound in long-duration software since late July, and is down 14% over twelve months. The stock trades at 8.65x trailing gross profit and 7.90x forward, against 12.3x a year ago — a de-rating of roughly a third while gross profit grew 20.5%. Reported earnings are no help here: June-quarter net margin of 22.1% is nearly three times the 8.2% operating margin, on items below the operating line.
The verdict splits. The seat count, the logo count and the partner channel earn the growth, and the three-month advance is mostly the rate-driven software rebound rather than anything AvePoint disclosed. What the business has not yet earned is the headline number: six of the guided twenty-six points are currency, which reverses if the dollar does, and the fastest-growing part of the pipeline now shares a category with a product the platform owner bundles for free at the top tier.
AgentPulse got its own price list in July. The first quarter that shows whether anyone pays it separately has not been reported.